


Wyndham Hotels & Resorts (WH) Launches Dolce Nova, Is The Stock Too Pricey?
Wyndham Hotels & Resorts launches Dolce Nova brand
Wyndham Hotels & Resorts (WH) has introduced Dolce Nova, an upper upscale extension of its Dolce Hotels & Resorts line, aimed at travelers seeking experience led, personalized stays and a stronger focus on wellbeing.
Recent trading tells a mixed story. Wyndham Hotels & Resorts has a 1 day share price return of 1.47% and a 7 day share price return of 0.80%. However, the 90 day share price return has fallen 17.85% while the 1 year total shareholder return is down 14.85%, which points to fading momentum despite the Dolce Nova launch and other brand activity.
Scan beyond Wyndham Hotels & Resorts and compare its Dolce Nova pivot with a curated group of hospitality and consumer service stocks in our 16 high quality undiscovered gems focused on experience led travel and strong fundamentals.
Wyndham Hotels & Resorts now trades well below recent highs while rolling out a higher end concept in Dolce Nova. Do current expectations already reflect the risks, or does the recent slide leave room for upside based on valuation alone?
Most Popular Narrative: 31% Undervalued
Against a last close of $69.17, the most followed narrative pegs Wyndham Hotels & Resorts at a fair value near $100. This frames Dolce Nova as only one part of a much broader earnings and cash flow story built around fees, tech, and loyalty.
Enhanced technology initiatives, including the rollout of AI-driven guest engagement, centralized Wi-Fi, and integrated booking/loyalty platforms, address growing consumer demand for branded, consistent asset-light lodging and should increase direct bookings, lower distribution costs, and support margin and earnings expansion over the long term.
See why 2 investors see Wyndham Hotels & Resorts as 31% undervalued.
Result: Fair Value of $100.18 (UNDERVALUED)
Still, the Wyndham Hotels & Resorts story can be knocked off course if weaker U.S. RevPAR or brand overlap across its large portfolio pressures fees and margins.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View: Multiples Paint A Tougher Picture For Wyndham Hotels & Resorts
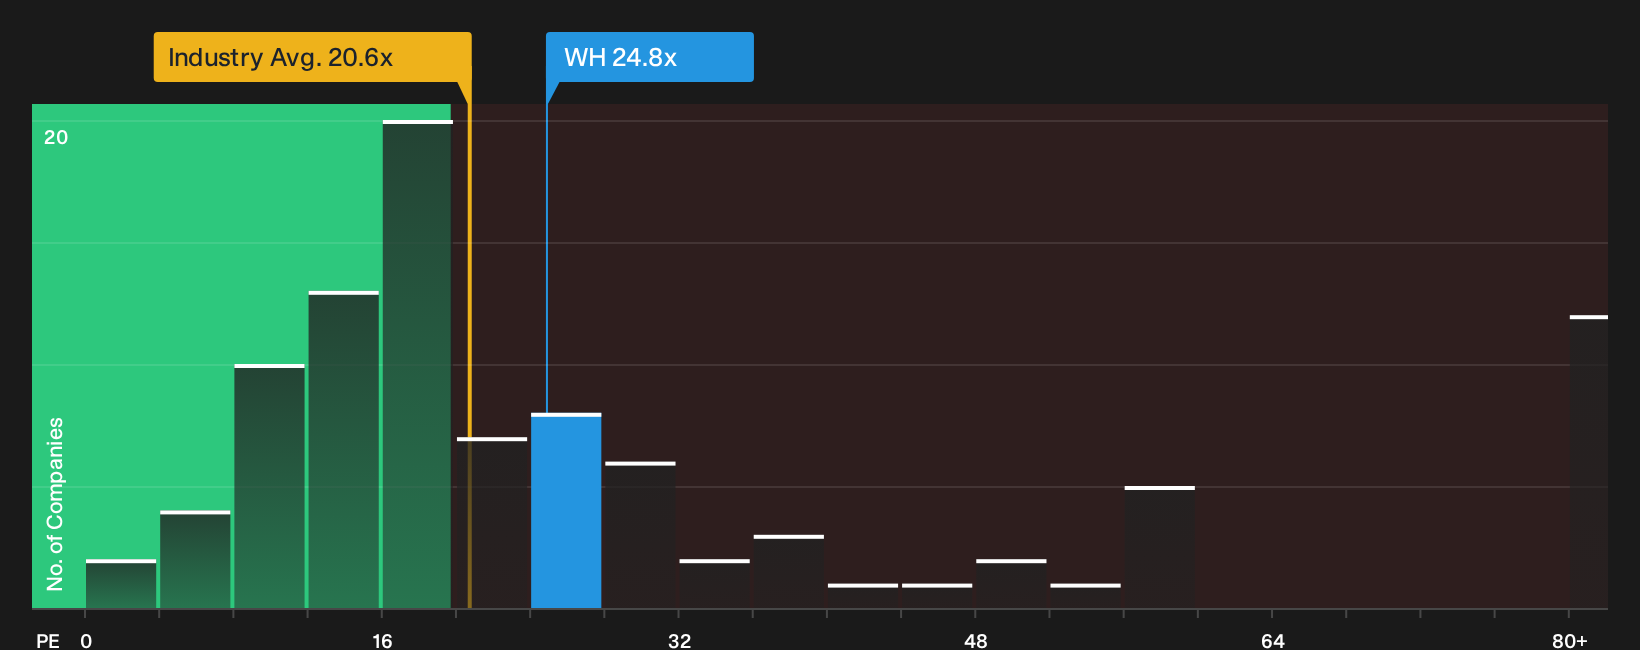
The narrative around Wyndham Hotels & Resorts leans heavily on a fair value near $100, yet the simple P/E check tells a more cautious story. At 24.8x earnings, the stock trades above both the US Hospitality industry on 20.6x and its peer average of 23.7x, and even above its own 22.5x fair ratio. That gap suggests investors are already paying a premium, which can limit upside if expectations cool.
For a closer look at how this P/E premium stacks up against the market and the model fair ratio, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Wyndham Hotels & Resorts can feel confusing, so move quickly, pull up the numbers yourself, weigh both sides, and then test your view against the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Wyndham Hotels & Resorts?
If Wyndham Hotels & Resorts has you rethinking your watchlist, broaden the view and line up a few fresh candidates before the next big move hits.
- Target undervalued opportunities that combine quality with potential mispricing by running your filters through the 29 high quality undervalued stocks.
- Prioritise resilience and aim for more peace of mind by sorting candidates with the 30 resilient stocks with low risk scores built around sturdier business profiles.
- Spot fresh prospects that many investors may be overlooking by scanning the list of solid balance sheet and fundamentals (23 results) and focusing on stronger financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com