


Rocket Lab (RKLB) Stock May Be 43% Undervalued Following $1.9B Equity Offering
Rocket Lab has been on a remarkable three year run, yet the real question for anyone looking at the stock today is whether its current price is adequately supported by the cash the business can generate over time.
- Rocket Lab shares have delivered a very large 3 year return of about 14x, which puts a lot of future cash flow expectations under the microscope.
- The recent US$1.944b equity raise to fund the Iridium acquisition reduces reliance on debt and may shift the timing and mix of future cash flows between funding growth and returning capital to shareholders.
- Prefer to judge Rocket Lab on book value? See why Rocket Lab's 11.6x P/B tells a different valuation story.
The issue now is whether Rocket Lab's current share price of US$67.82 is reasonable when judged against the intrinsic value suggested by its cash flows using a Discounted Cash Flow (DCF) approach.
If you want a quick benchmark for Rocket Lab's three year run and cash flow story, you can compare it to other space and defense plays using our 30 resilient stocks with low risk scores.
Is Rocket Lab a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around what Rocket Lab might generate in cash for shareholders over time. Latest twelve month free cash flow shows a loss of about US$370.5 million, so the whole framework leans heavily on the idea that today’s cash burn eventually flips into meaningful surplus.
Analysts and extrapolated estimates in this DCF point to free cash flow moving from losses to positive territory and then growing, with projected annual figures reaching into the low single digit US$ billions over the next decade. That trajectory helps explain why the model’s intrinsic value estimate sits substantially above the current share price of US$67.82. Because the US$1.944b equity raise fully funded the Iridium deal and reduced reliance on bridge debt, the cash flow story the DCF is using now depends more on execution than on balance sheet strain. Find out what Rocket Lab could be worth using our Discounted Cash Flow (DCF) estimate.
The Rocket Lab Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off by laying out the specific growth, margin and earnings paths Rocket Lab would need for the shares to be worth materially more or less than today’s price. Each one ties a fair value to a clear storyline about the company’s potential catalysts and key risks so you can track over time which version of events seems to be playing out.
Rocket Lab inspires sharply different narratives, with some holders seeing a big runway ahead while others think expectations already stretch too far.
Bull case: 31% undervalued
"Rocket Lab USA seeks to vertically integrate itself throughout the $800 billion space 'backbone' in order to attract the customers operating within that $1 trillion top component…"
Discover why this Narrative puts Rocket Lab at 31% undervalued.
Bear case: 317% overvalued
"The entire valuation is 'priced for perfection,' which means any delay causes volatility…"
Explore why this Narrative puts Rocket Lab at 317% overvalued.
One more Rocket Lab signal worth putting on your radar
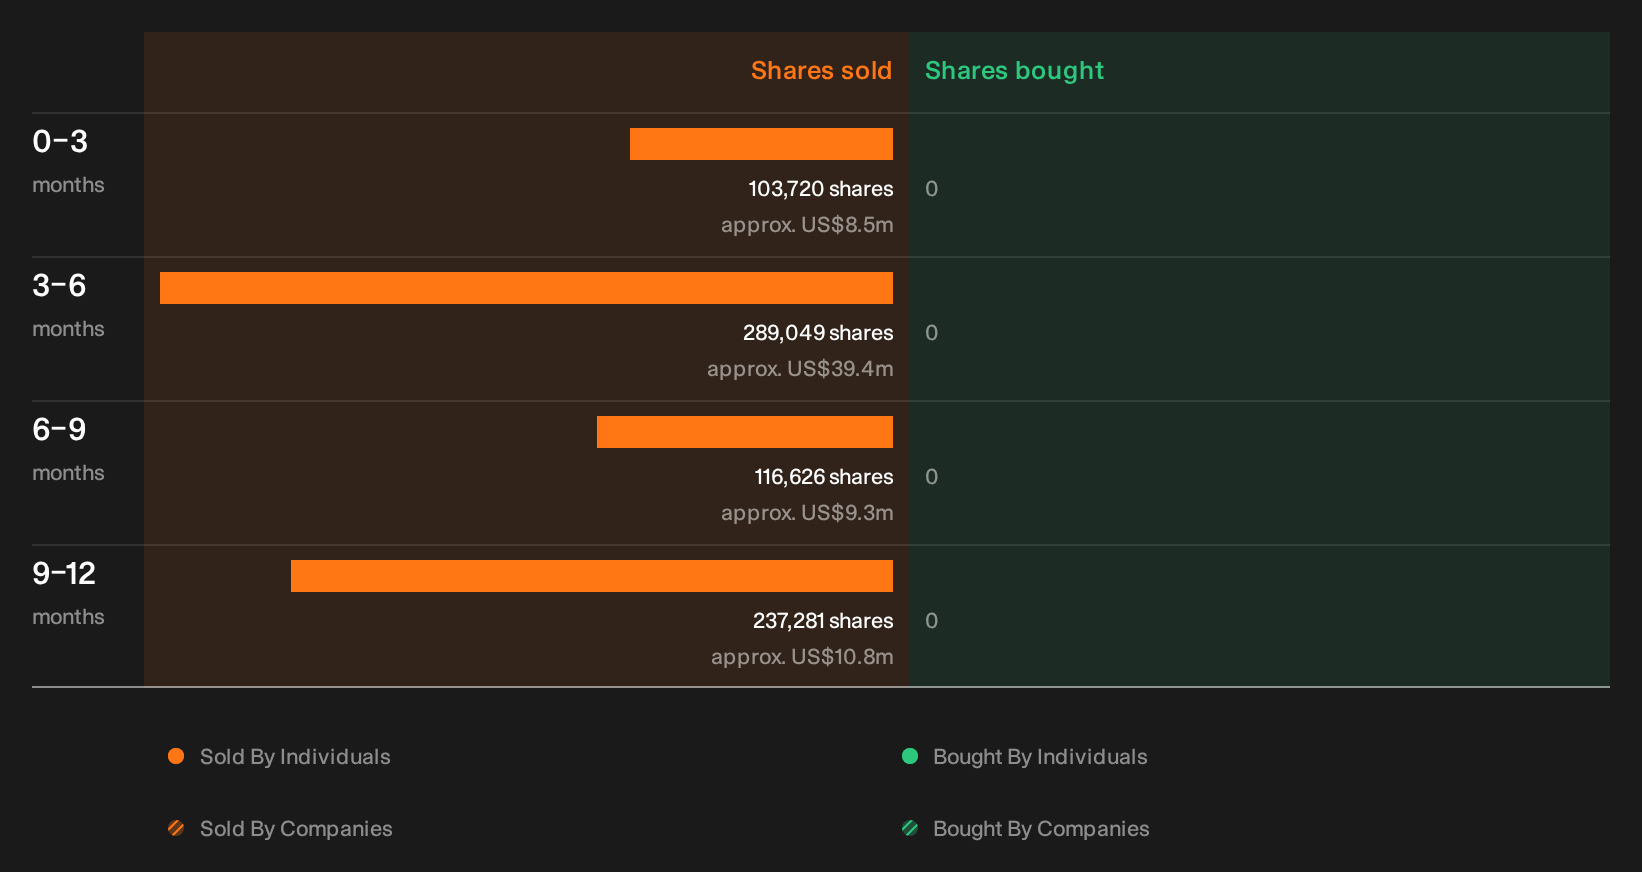
There is one piece of the Rocket Lab story this valuation work has not touched yet, which is the recent trading activity by people inside the business, including who sold, how much, and what that might suggest. See the recent insider selling flagged for Rocket Lab.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com