


Tyson Foods (TSN) Could Be 23% Undervalued Following Beef Settlement Notice
Tyson Foods (TSN) is back in focus after a court authorized an amended notice in an ongoing beef price fixing class action settlement, extending key deadlines and outlining a US$82.5m payment commitment.
Against that legal backdrop, Tyson Foods shares trade at US$52.26, with the 1 month share price return down 9.88% and the year to date share price return down 9.96%. The 1 year total shareholder return is roughly flat and the 3 year total shareholder return of 9.34% contrasts with a 5 year total shareholder return that is down 19.48%, pointing to momentum that has softened in the short term after a patchier longer run.
Scan how Tyson Foods compares with other meat processors and packaged food players by reviewing list of solid balance sheet and fundamentals (23 results) tied to resilient earnings and legal overhangs such as this settlement context.
Tyson Foods trades roughly 23% below the average analyst price target after a weak recent run and a fresh legal bill on the table. Is that discount compensation for risk, or a sign the market is overly cautious?
Most Popular Narrative: 21% Undervalued
Tyson Foods is framed by the most followed narrative as worth $66.08 per share, compared with the recent close at $52.26. This puts the focus squarely on whether the earnings rebuild justifies that gap.
Momentum in prepared and value-added foods, driven by a robust innovation pipeline and product launches targeting convenience and protein-oriented lifestyles, is shifting the product mix toward higher-margin categories and is expected to improve net margins and top-line growth.
Continuous operational efficiencies, supply chain optimization, and manufacturing improvements are delivering tangible cost savings, higher fill rates, and reduced waste, which should support net margin expansion and greater earnings stability.
See why 43 investors see Tyson Foods as 21% undervalued.
Result: Fair Value of $66.08 (UNDERVALUED)
Still, the Tyson Foods narrative could be knocked off course if beef losses linger longer than analysts model and if raw material costs continue to squeeze Prepared Foods margins.
Find out about the key risks to this Tyson Foods narrative.
Another View: Tyson Foods On Earnings Multiples
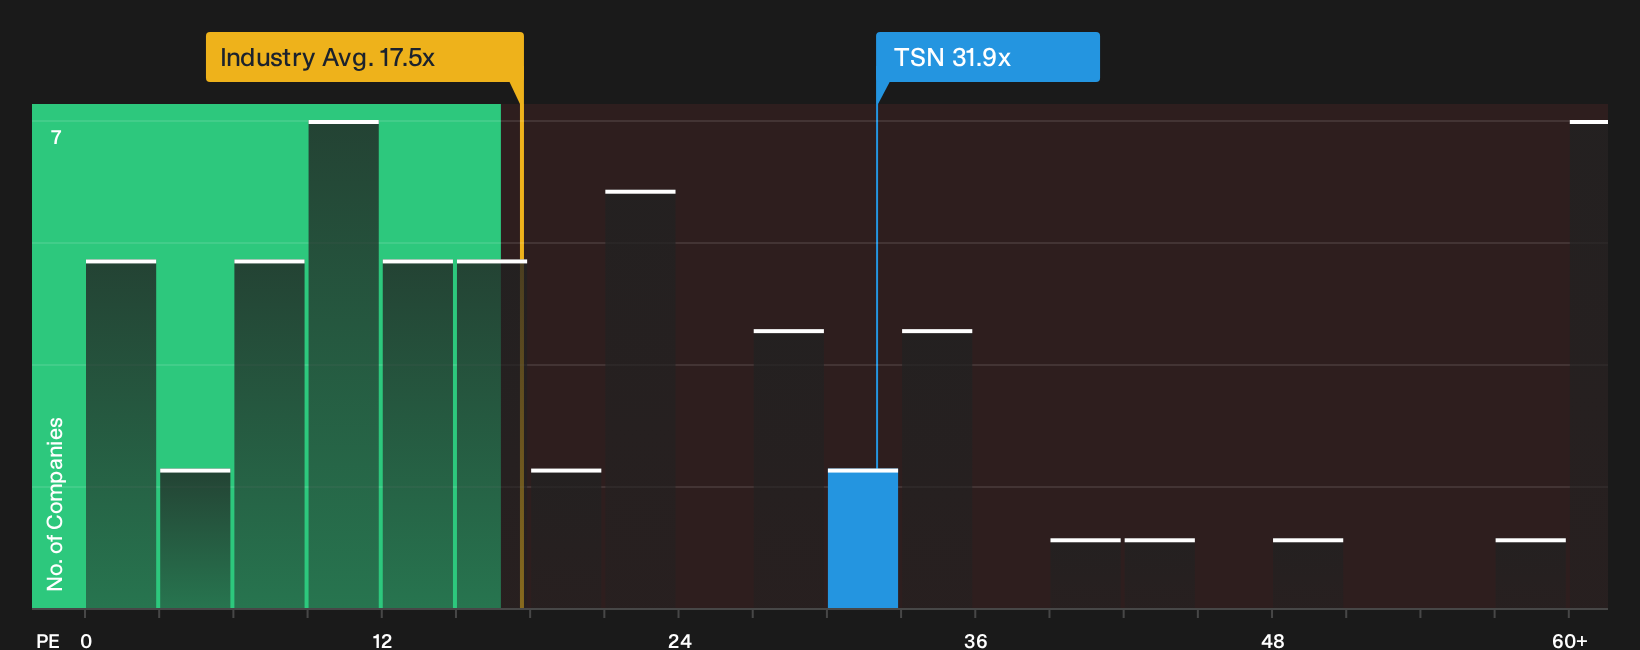
That fair value of $66.08 leans heavily on future cash flows. On a simple P/E, Tyson Foods tells a different story. The shares trade on about 31.9x earnings versus roughly 17.5x for the wider US Food group, while the fair ratio is 47x.
This mix means the stock appears expensive compared with peers, yet cheaper than the level implied by the fair ratio. For anyone weighing that gap, the key question is whether earnings change enough for the higher multiple to seem justified.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can be confusing, especially when Tyson Foods carries both concern and optimism in the data. Act while the facts are fresh, and weigh both sides of the story by reviewing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tyson Foods?
If Tyson Foods has sharpened your thinking on value, do not stop here. Broaden your watchlist with fresh ideas filtered for quality, price, and resilience.
- Target potential mispricing by scanning companies that pass our quality and valuation filters through the 29 high quality undervalued stocks.
- Seek more predictable cash returns by reviewing income opportunities through the 6 dividend fortresses.
- Focus on protecting your capital by concentrating on financially robust businesses highlighted in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com