


Precigen (PGEN) Stock Looks Above Fair Value After Its Big Run
Precigen has seen its stock price move sharply in recent years, which naturally puts the focus on whether that share move lines up with what the company is generating in sales. With the stock now closing at US$7.87, the question for investors is how much current revenue performance can support that valuation.
- Over the past 3 years the share price has delivered a very large 462.1% return, so any view on Precigen now hinges on how much of that gain its sales can credibly underpin.
- The business model relies heavily on turning its biotech pipeline into commercial products, which can influence both the pace of future revenue and the timing of any cash inflows that investors expect to see.
- There is a second opinion on Precigen worth weighing. See what analysts think Precigen's shares could be worth.
The stock's next move may depend on whether Precigen's current share price is justified by its sales when compared with the Fair Ratio benchmark.
If you want a second reference point while you weigh Precigen at US$7.87 against its sales, it can help to compare it with other companies using the 29 high quality undervalued stocks.
Does Precigen Look Pricey on Sales?
P/S is a useful lens for Precigen because the market is mainly paying for its revenue base and pipeline potential rather than current profits. At roughly 32.9x P/S, the stock trades at a much richer level than the broader Biotechs group, which sits around 12.6x. The gap to the peer average of about 8.0x is even wider, so buyers are putting a high tag on each dollar of Precigen's sales.
The Fair Ratio model, which blends factors like the company’s risk profile, margins and size, points to a lower P/S than where Precigen is currently priced. The difference is large enough that the framework is effectively flagging the shares as overvalued on this metric. The model heavily discounts recent losses and uncertainty around future revenue quality, rather than offering a tight estimate of fair worth. For anyone considering the stock at US$7.87, that means the burden of proof sits with future execution to justify such a premium P/S. Explore the numbers behind Precigen's P/S valuation.
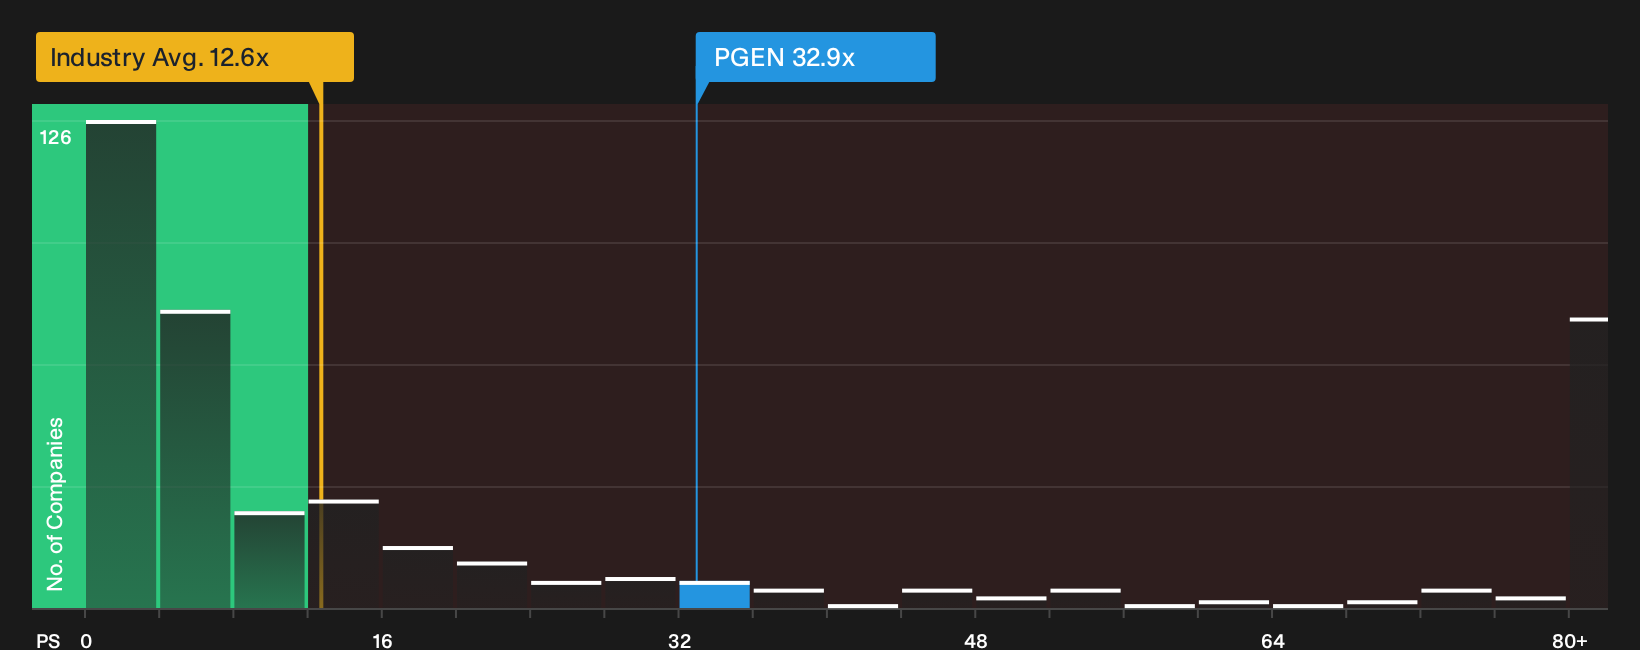
The Precigen Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the valuation puzzle for Precigen leaves off by explaining which paths for revenue, margins and earnings would need to occur for the shares to be worth significantly more or less than today’s price. Each narrative presents fair value as a thesis about how the business could unfold over time, allowing you to see how that view holds up as new information arrives on the Community page.
One of the top community narratives on Precigen: 46% undervalued
"Bullish analysts see the seven years of FDA orphan-drug market exclusivity for Papzimeos in adult recurrent respiratory papillomatosis as a key support…"
Discover why this Narrative puts Precigen at 46% undervalued.
One more Precigen signal to consider before making a move
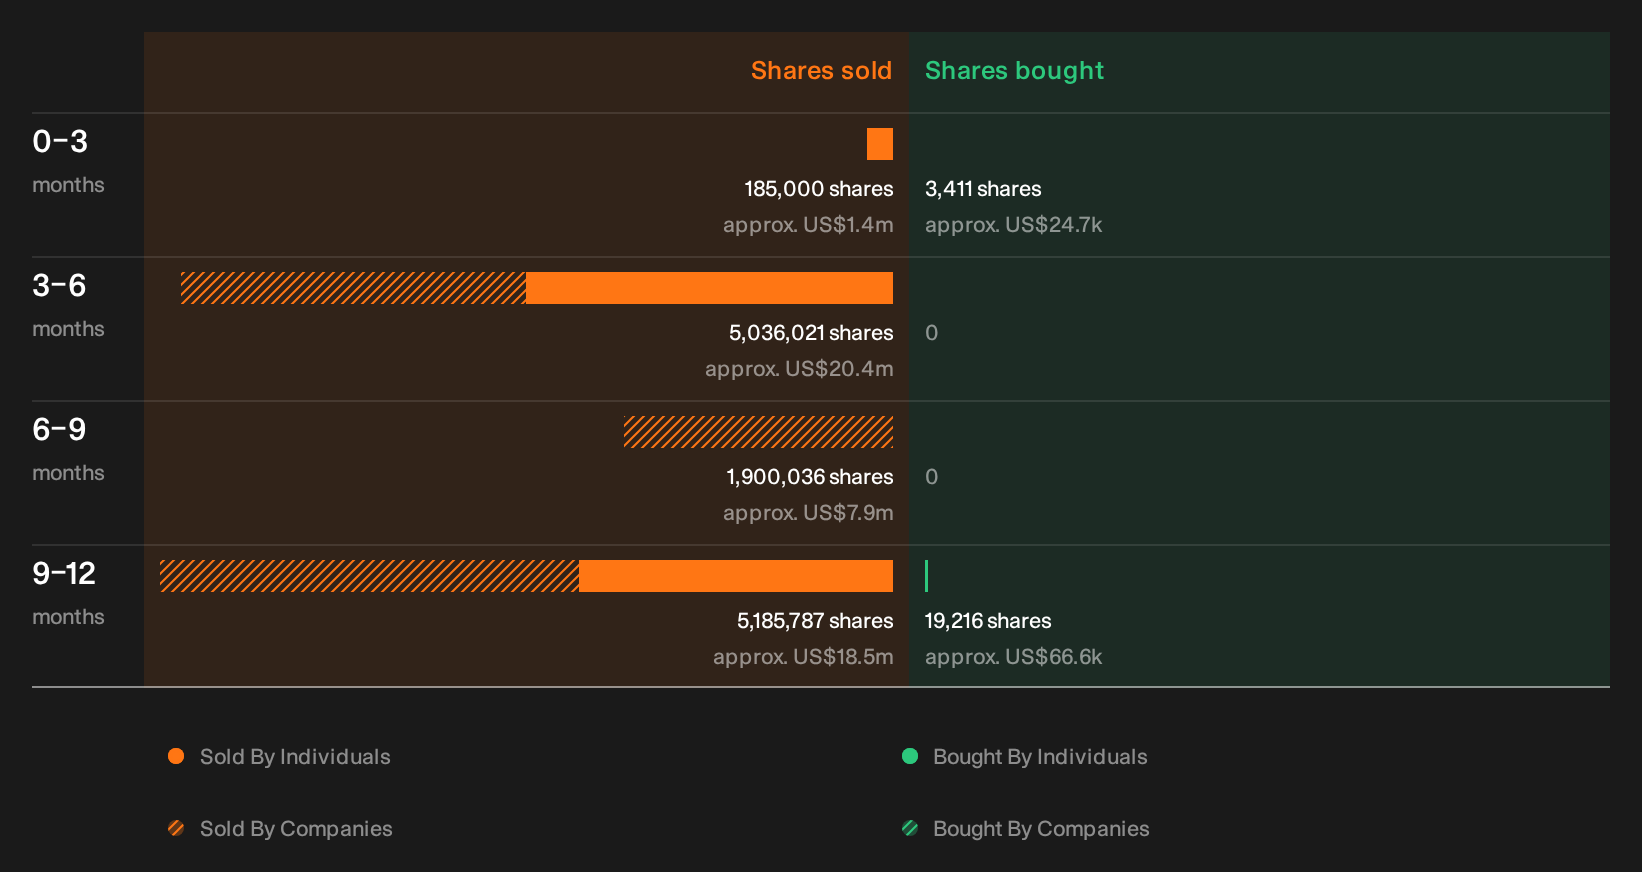
Before you act on any view of Precigen, it is worth checking what recent insider share activity has looked like, who has been selling and in what amounts, and what that might mean for alignment with outside investors. See the recent insider selling flagged for Precigen.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com