


Quarterly Dividend Declared Could Matter For Charter Hall Retail REIT Shares
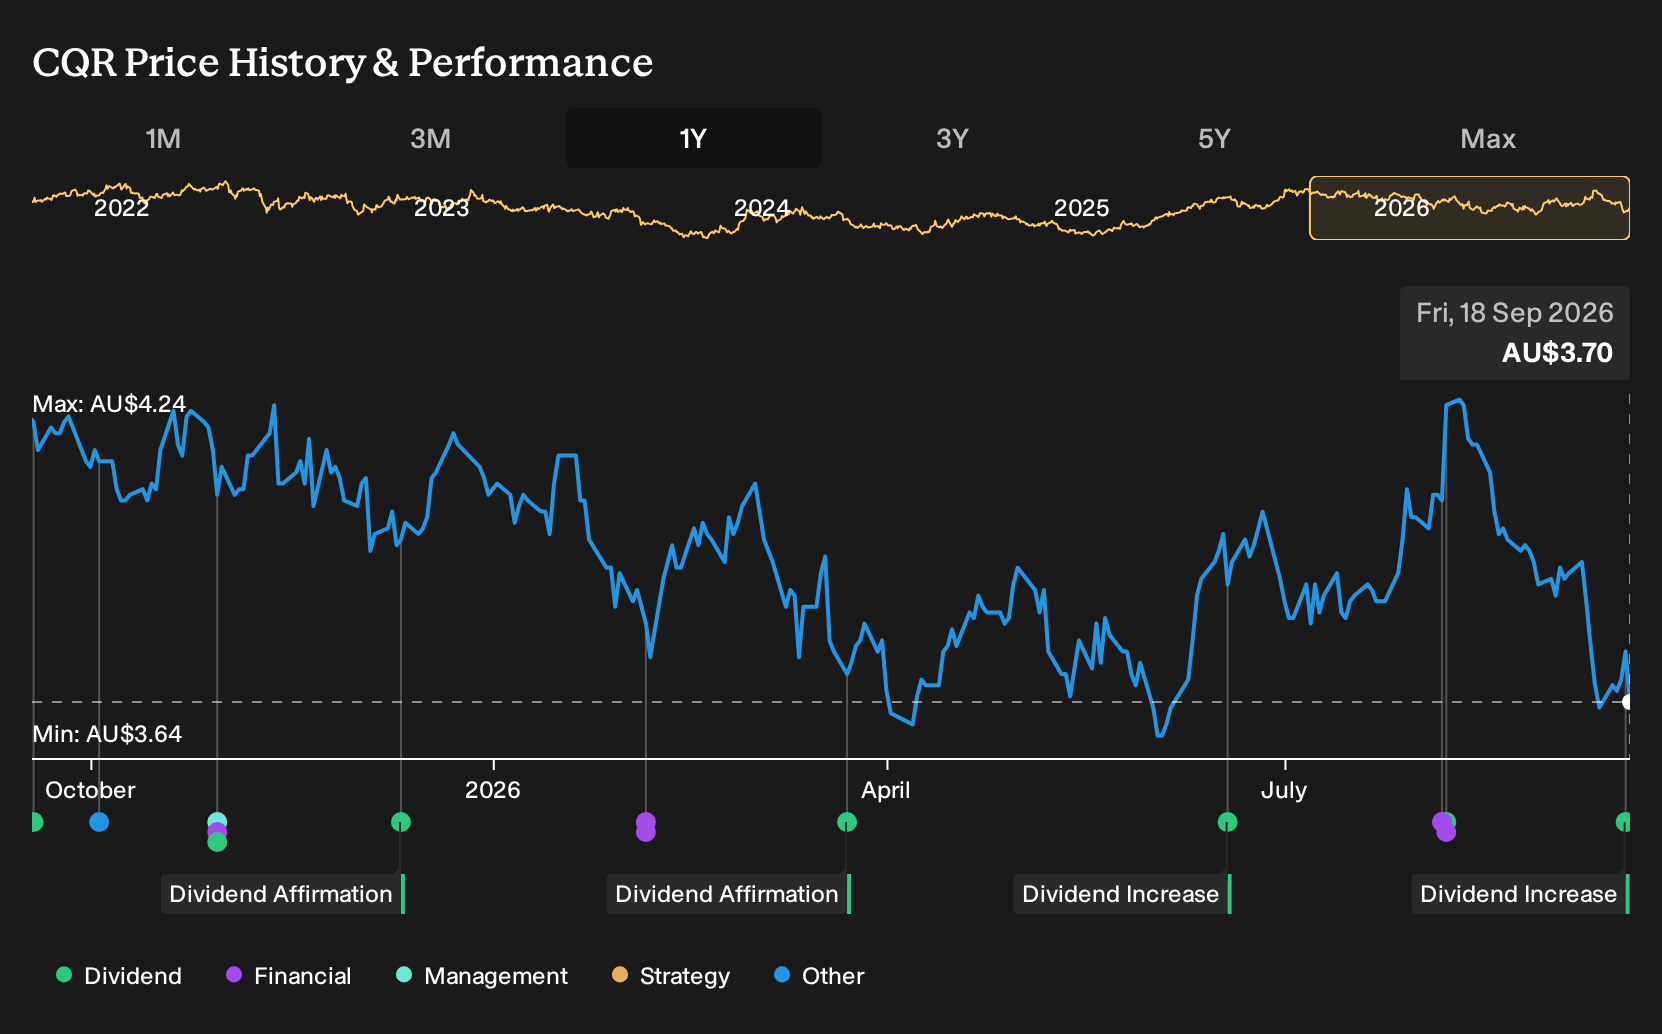
- Charter Hall Retail REIT declared an ordinary unfranked quarterly distribution of A$0.066 per unit for the September 2026 quarter, with an ex date of 29 September, a record date of 30 September, and payment scheduled for 27 November 2026.
- The unfranked structure of the A$0.066 distribution matters for many investors, since after tax cash yield and suitability for different portfolios can depend heavily on whether a REIT pays franked or unfranked income.
- We will now look at how this fresh A$0.066 unfranked distribution shapes the broader Charter Hall Retail REIT investment narrative for income focused holders.
Scan beyond Charter Hall Retail REIT by reviewing hand picked income ideas in the 4 dividend fortresses that echo this A$0.066 quarterly payout focus.
What Is Charter Hall Retail REIT's Investment Narrative?
To own Charter Hall Retail REIT, you need to buy into a simple idea. Everyday convenience retail in Australia still needs well located bricks and mortar, and a specialist landlord that can keep those assets leased, maintained and financed. The A$0.066 unfranked quarterly distribution fits that story. It signals management is comfortable sending cash back to holders right now, even after a period where revenue fell 4.3% and earnings declined 15.2% on an annual basis.
In the short term, this payout looks more like a continuation than a clear new catalyst. The unit price is down about 9.5% year to date, with CQR trading on a 5.5x P/E and roughly 24.6% below one internal fair value estimate. That context points to ongoing concern about earnings forecasts, debt coverage and a dividend track record that has been flagged as unstable. Income investors are being paid to wait, but the bigger question is how that income interacts with...
There's only one way to know the right time to buy, sell or hold Charter Hall Retail REIT. Head to Simply Wall St's company report for the latest analysis of Charter Hall Retail REIT's Fair Value.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Charter Hall Retail REIT research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Charter Hall Retail REIT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charter Hall Retail REIT's overall financial health at a glance.
Looking For More Investment Ideas Beyond Charter Hall Retail REIT?
If this Charter Hall Retail REIT update has sharpened your income focus, it can help to set it against a wider watchlist and see how other businesses stack up on yield, value and balance sheet strength using the Simply Wall St Screener.
- For investors who want dependable cash flows, scan for income ideas with resilient payouts using our 4 dividend fortresses that share a similar focus on distributions.
- If value is your priority, compare Charter Hall Retail REIT to companies that pair strong fundamentals with what may be undemanding pricing by reviewing the 5 high quality undervalued stocks.
- For a focus on resilience, filter for businesses with robust finances and low risk profiles through the 7 resilient stocks with low risk scores and see how they complement an income oriented portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com