


Is Exosens (ENXTPA:EXENS) Undervalued On Raised 2026 Guidance?
Exosens raises 2026 guidance and sharpens investor focus
Exosens (ENXTPA:EXENS) lifted its full-year 2026 earnings guidance and now projects revenue between €558 million and €570 million, compared with an earlier range of €520 million to €540 million.
The upgraded outlook has quickly fed into the market reaction, with Exosens’ 1-day share price return of 8.37% lifting the stock to €58.9 and partly reversing a 30-day share price decline of 5.38% and a 90-day share price fall of 2.00%.
Even with that recent pullback, overall momentum remains positive. The year-to-date share price return sits at 17.80% and the 1-year total shareholder return is 42.24%, suggesting investors have been reassessing both growth potential and risk after the stronger 2026 guidance and earlier updates around demand in drones, surveillance, and nuclear instrumentation.
Scan how Exosens fits into the broader defence and imaging theme by comparing it with a hand-picked 95 robotics and automation stocks benefiting from automation, sensing, and surveillance demand.
Exosens now looks like a stronger operation after the guidance lift and recent share price jump. The real question is whether that quality is already fully baked into today’s €58.9 price.
Most Popular Narrative: 12% Undervalued
The most followed Exosens valuation story pegs fair value at €67.13, comfortably above the latest €58.9 close. This frames the recent guidance upgrade against a still discounted share price in that model.
The significant increases in global defense spending, especially the raised NATO target to 3.5% of GDP, combined with Exosens' leadership in night-vision and amplification technologies, position the company to benefit from a multi-year surge in demand for high-end defense sensing equipment, likely driving sustained high revenue growth and improved order visibility.
Accelerating adoption of advanced sensing and photonic solutions in autonomous systems, drones, and broader industrial digitization trends underpin growing, diversified end-markets for Exosens, expanding its addressable markets and supporting long-term top-line growth.
See why 6 investors see Exosens as 12% undervalued.
The narrative applies a 7.60% discount rate to those projected cash flows and concludes that, if the expected demand in defense, drones, and industrial sensing plays out, Exosens could justify that €67.13 mark as a central valuation anchor relative to today’s price.
Result: Fair Value of €67.13 (UNDERVALUED)
Still, that underpriced story can unravel fast if defense budgets reset or recent lower margin acquisitions drag more heavily on group profitability.
Find out about the key risks to this Exosens narrative.
Another View: What Exosens’ P/E Ratio Is Telling You
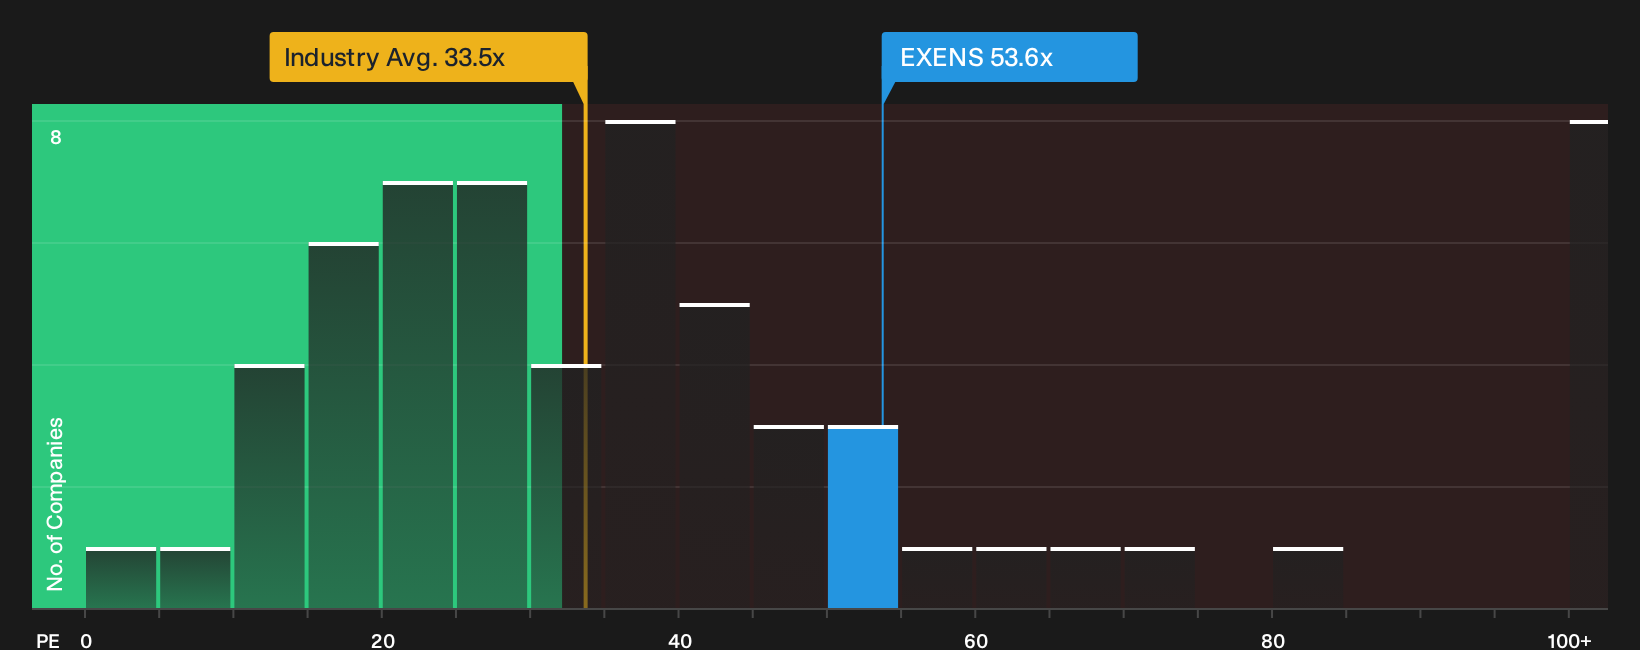
The SWS DCF model points to value upside for Exosens, yet the simple P/E check sends a very different message. At 53.6x earnings, the stock trades well above the European Aerospace & Defense average of 33.7x and a fair ratio estimate of 26.8x. This raises the risk that expectations are already stretched.
That kind of premium multiple can work in your favor if growth and margins track the optimistic narrative, but it also leaves less room for disappointments before the share price adjusts. The question is whether you see today’s earnings power as strong enough to keep justifying that gap over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed message or clear opportunity? If you want to move quickly and judge the balance of concern and optimism for yourself, start with the 2 key rewards and 1 important warning sign.
Looking for more Exosens-sized investment ideas?
If Exosens has sharpened your appetite for opportunity, do not stop here. Use the screener to uncover other candidates that match your preferred balance of potential and risk.
- Target potential mispricings by scanning a focused pool of 173 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying strength.
- Prioritise resilience first by filtering for 227 resilient stocks with low risk scores that may help anchor your portfolio when sentiment turns and volatility picks up.
- Hunt for possible future leaders at an early stage by tracking a 617 high quality undiscovered gems that many investors might be overlooking right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com