


Discovering Auntea Jenny Shanghai Industrial And 2 Other Asian Small Cap Gems
Amidst global market volatility driven by geopolitical tensions and rising oil prices, Asian small-cap stocks have emerged as intriguing prospects for investors seeking growth opportunities. In this environment, identifying companies with strong fundamentals and the ability to navigate economic uncertainties is crucial, making Auntea Jenny Shanghai Industrial and two other promising small-cap gems in Asia worth exploring.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Goodbaby International Holdings | 6.30% | -1.33% | 24.07% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
Auntea Jenny (Shanghai) Industrial (SEHK:2589)
Simply Wall St Value Rating: ★★★★★☆
Overview: Auntea Jenny (Shanghai) Industrial Co., Ltd. operates in the restaurant industry and has a market capitalization of HK$7.48 billion.
Operations: The company's primary revenue stream is from its restaurant segment, generating CN¥5236.63 million.
Auntea Jenny (Shanghai) Industrial has shown impressive growth, with earnings climbing 70.2% over the past year, outpacing the Hospitality industry’s 15.9%. The company reported a net income of CNY 321 million for the first half of 2026, up from CNY 203 million a year earlier. Trading at about 72% below its estimated fair value, it offers good relative value compared to peers. Despite recent share price volatility, Auntea Jenny's high-quality earnings and robust cash flow position it well in the market. Additionally, an interim dividend increase reflects confidence in its financial health and future prospects.
- Delve into the full analysis health report here for a deeper understanding of Auntea Jenny (Shanghai) Industrial.
Learn about Auntea Jenny (Shanghai) Industrial's historical performance.

DeHua TB New Decoration MaterialLtd (SZSE:002043)
Simply Wall St Value Rating: ★★★★★★
Overview: DeHua TB New Decoration Material Co., Ltd specializes in the production and sale of furniture boards both domestically and internationally, with a market capitalization of CN¥8.84 billion.
Operations: DeHua TB primarily generates revenue from its Decorative Material Business, contributing CN¥8.08 billion, followed by the Custom Home Business at CN¥1.33 billion.
DeHua TB New Decoration Material Co., a small player in the Asian market, has shown a notable reduction in its debt to equity ratio from 56.3% to 0.3% over five years, indicating strong financial management. The company reported half-year sales of CNY 3.99 billion and revenue of CNY 4.27 billion, reflecting growth compared to last year’s figures. Despite this progress, net income slightly decreased to CNY 247 million from CNY 268 million previously, with basic earnings per share at CNY 0.3 down from CNY 0.33 last year, suggesting some challenges in maintaining profitability amidst expansion efforts.

SIGMAXYZ Holdings (TSE:6088)
Simply Wall St Value Rating: ★★★★★☆
Overview: SIGMAXYZ Holdings Inc. operates as a consulting services provider in Japan, with a market capitalization of approximately ¥46.62 billion.
Operations: SIGMAXYZ Holdings generates revenue primarily through its consulting business, which reported earnings of ¥23.20 billion. The company's financial performance is influenced by its ability to manage costs effectively while optimizing net profit margins.
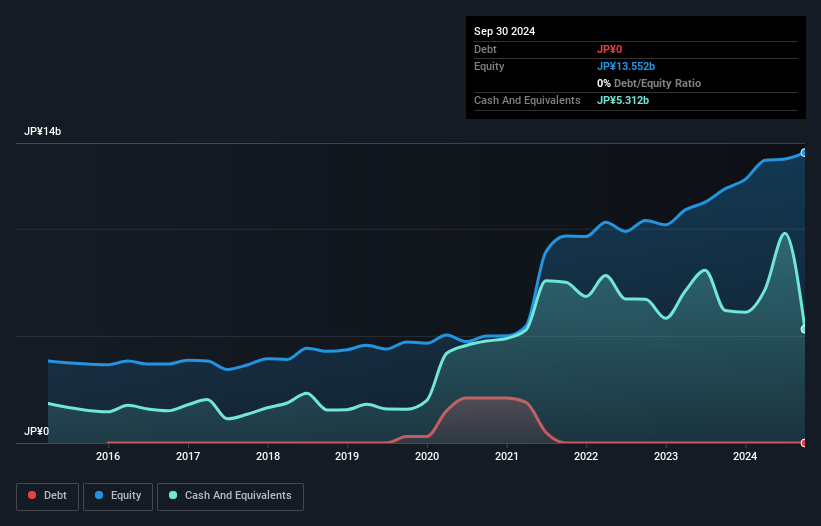
SIGMAXYZ Holdings, a promising player in Asia's market landscape, seems undervalued as it trades at 64.6% below its estimated fair value and offers good relative value against peers. Despite a dip in earnings growth by 12.2% last year, the company forecasts an annual growth of 11.91%, indicating potential upside. The debt-to-equity ratio has risen from 5.6% to 39.2% over five years; however, cash reserves exceed total debt, ensuring financial stability and positive free cash flow status remains intact. Recent share repurchase activity involved buying back 313,100 shares for ¥172 million between May and June this year.
- Click here to discover the nuances of SIGMAXYZ Holdings with our detailed analytical health report.
Gain insights into SIGMAXYZ Holdings' past trends and performance with our Past report.
Summing It All Up
- Click this link to deep-dive into the 118 companies within our Asian Undiscovered Gems With Strong Fundamentals screener.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com