


ASX Penny Stocks To Consider In September 2026
The Australian market is poised for a stronger opening, buoyed by a positive rebound in US equities despite recent interest rate hikes by the Federal Reserve. As investors navigate these shifting dynamics, penny stocks—typically smaller or newer companies—remain an intriguing option for those looking beyond the more prominent names. While often considered a throwback term, penny stocks can offer unique opportunities when they possess strong balance sheets and solid fundamentals, making them worth considering as potential hidden gems in today’s market landscape.
We're going to check out a few of the best picks from our screener tool.
Auric Mining (ASX:AWJ)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Auric Mining Limited is involved in the exploration, development, mining, and production of gold in Australia with a market cap of A$48.64 million.
Operations: Auric Mining Limited has not reported any specific revenue segments.
Market Cap: A$48.64M
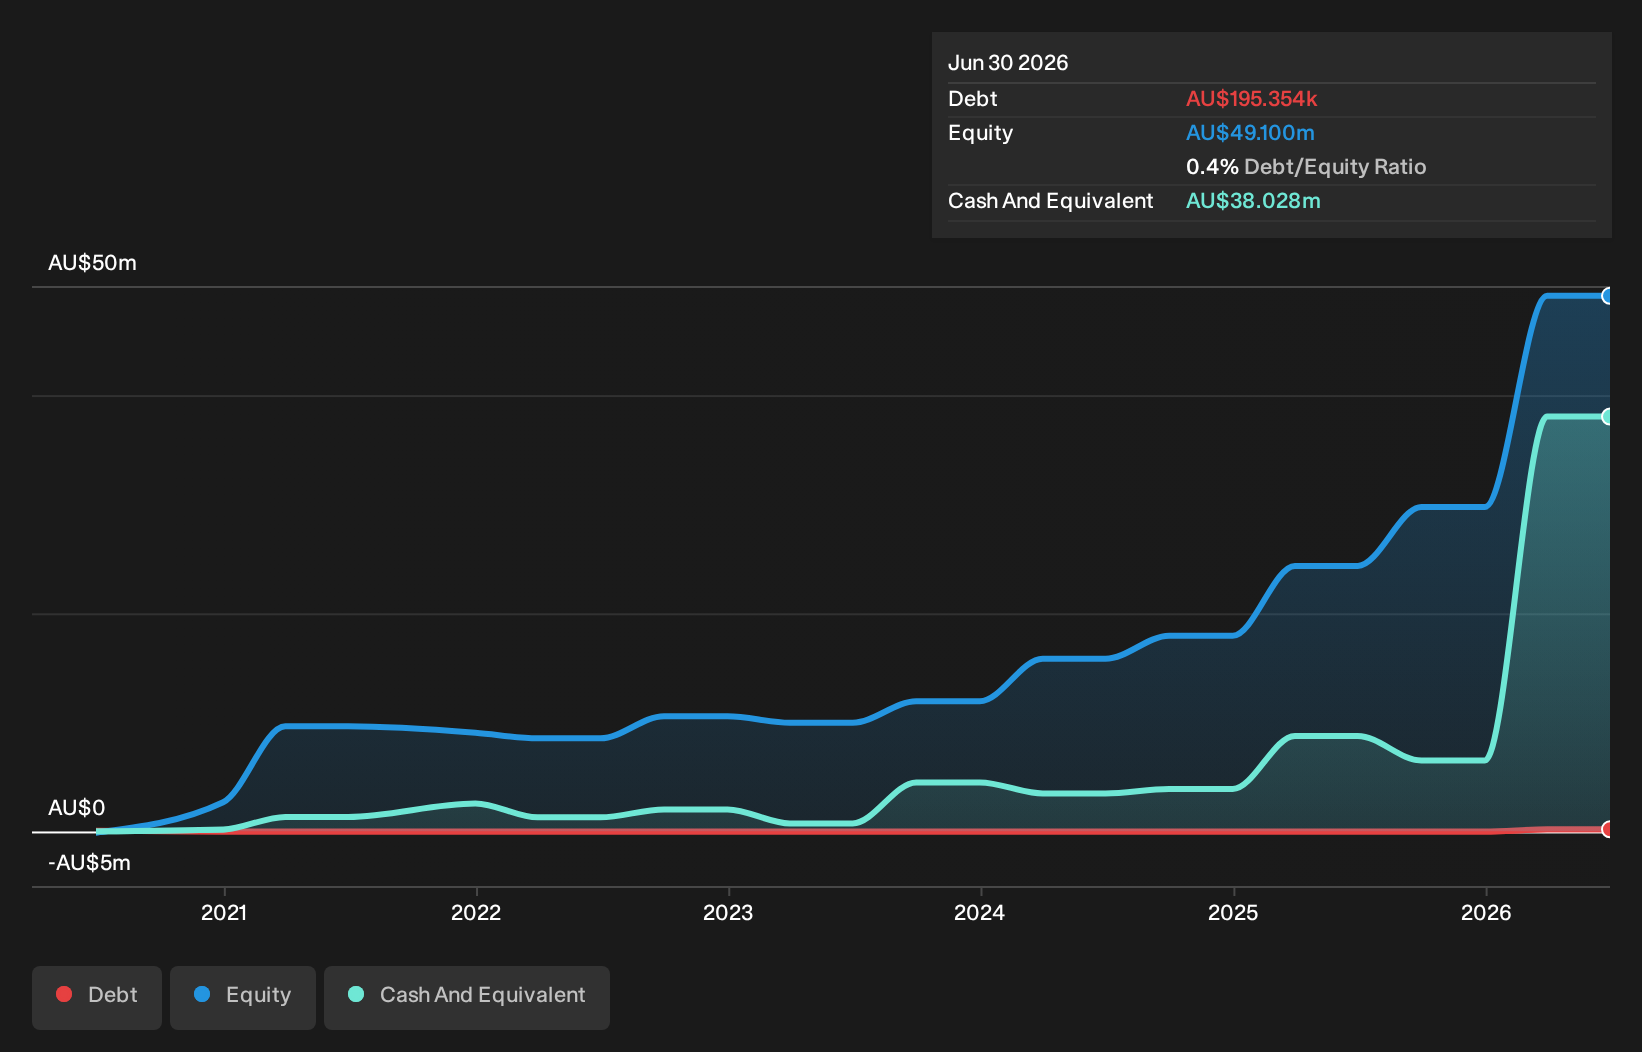
Auric Mining Limited, with a market cap of A$48.64 million, has demonstrated significant financial improvements and stability. The company reported A$44.32 million in sales for the half year ending June 30, 2026, marking a turnaround from a net loss to a net income of A$19.26 million compared to the previous year. Auric's short-term assets significantly exceed its liabilities, and it maintains more cash than debt. Its earnings growth over the past year was exceptionally high at 1070%, surpassing industry averages and reflecting an outstanding return on equity of 50.1%. However, management's limited experience may present challenges ahead.
- Click to explore a detailed breakdown of our findings in Auric Mining's financial health report.
- Explore Auric Mining's analyst forecasts in our growth report.
Shaver Shop Group (ASX:SSG)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Shaver Shop Group Limited operates as a retailer of personal care and grooming products across Australia and New Zealand, with a market cap of A$174.25 million.
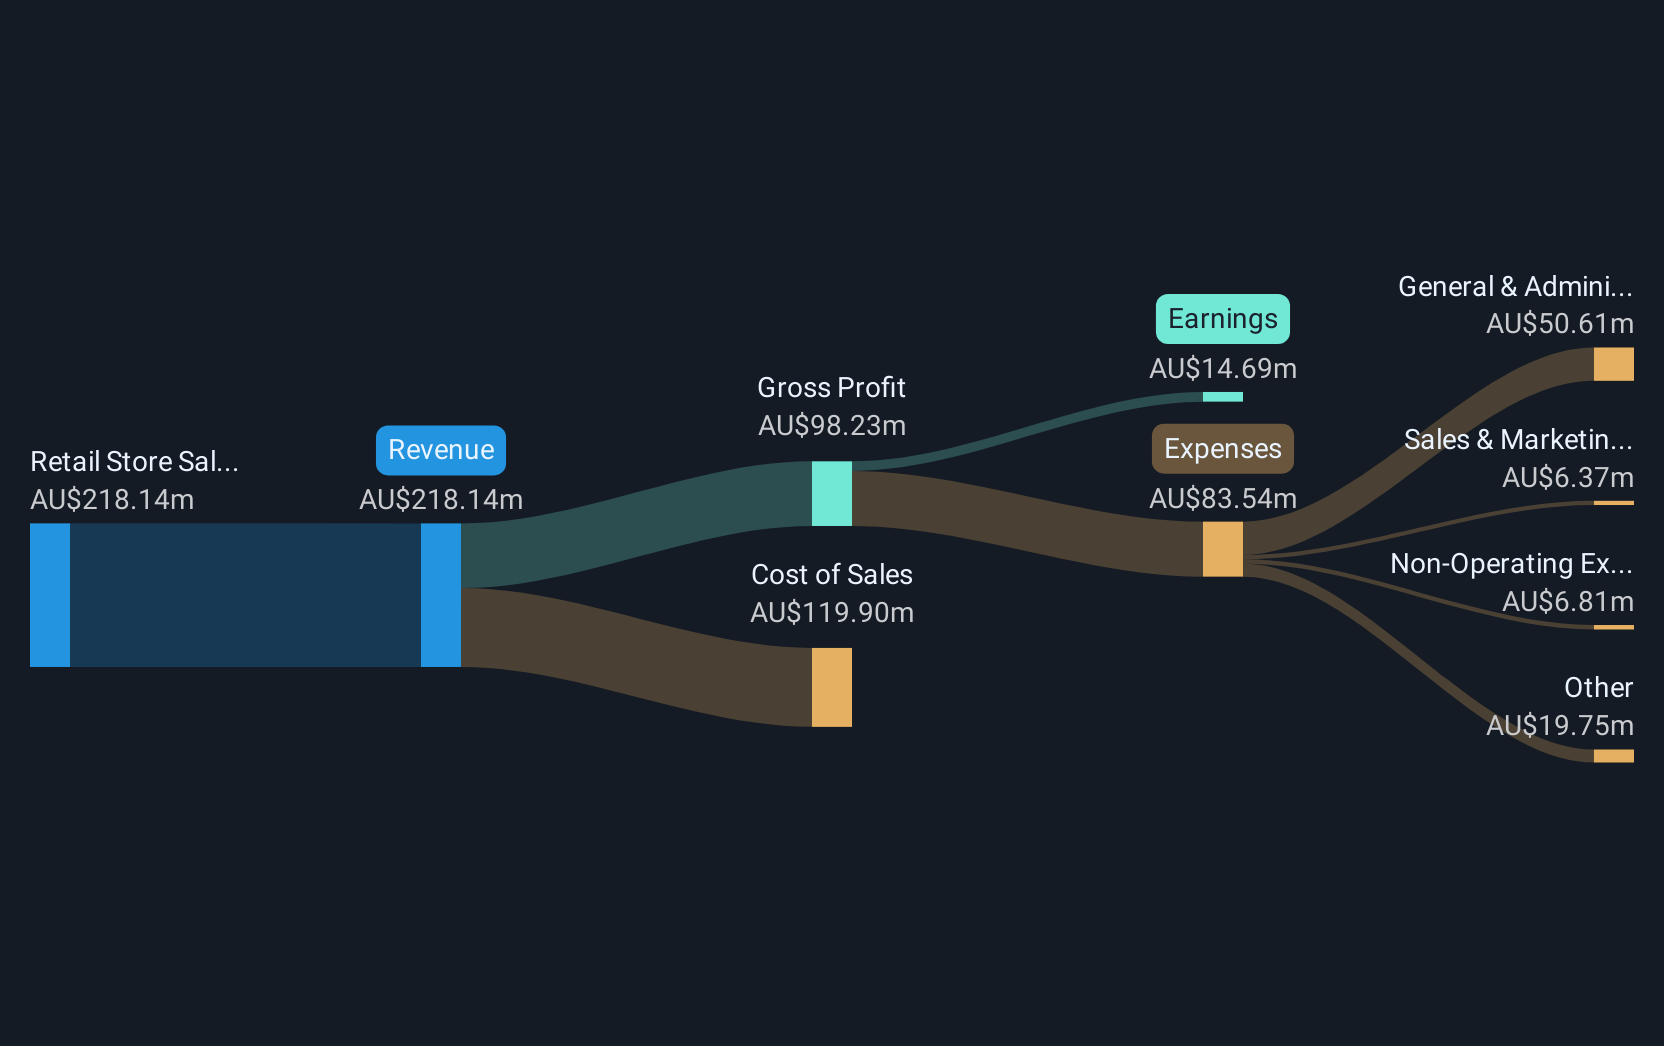
Operations: The company generates revenue primarily through retail store sales of specialist personal grooming products, amounting to A$225.10 million.
Market Cap: A$174.25M
Shaver Shop Group Limited, with a market cap of A$174.25 million, operates debt-free and maintains stable financials with short-term assets exceeding liabilities. Despite a slight decline in net profit margins from 6.8% to 6.6%, the company reported steady sales growth to A$225.10 million for FY26. However, earnings have declined by an average of 3.5% annually over five years, and recent insider selling may raise concerns for potential investors in penny stocks seeking stability and growth prospects. The board's seasoned tenure provides governance strength amid ongoing strategic adjustments following executive changes this year.
- Click here to discover the nuances of Shaver Shop Group with our detailed analytical financial health report.
- Evaluate Shaver Shop Group's prospects by accessing our earnings growth report.
Zicom Group (ASX:ZGL)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Zicom Group Limited, with a market cap of A$34.49 million, manufactures and sells marine deck machinery, fluid regulating and metering stations, transit concrete mixers, foundation and geotechnical equipment, as well as precision engineered and automation equipment.
Operations: The company's revenue is derived from three main segments: Construction Equipment (SGD 39.43 million), Green Energy, Gas & Marine Equipment (SGD 22.01 million), and Precision Engineering & Technologies (SGD 33.39 million).
Market Cap: A$34.49M
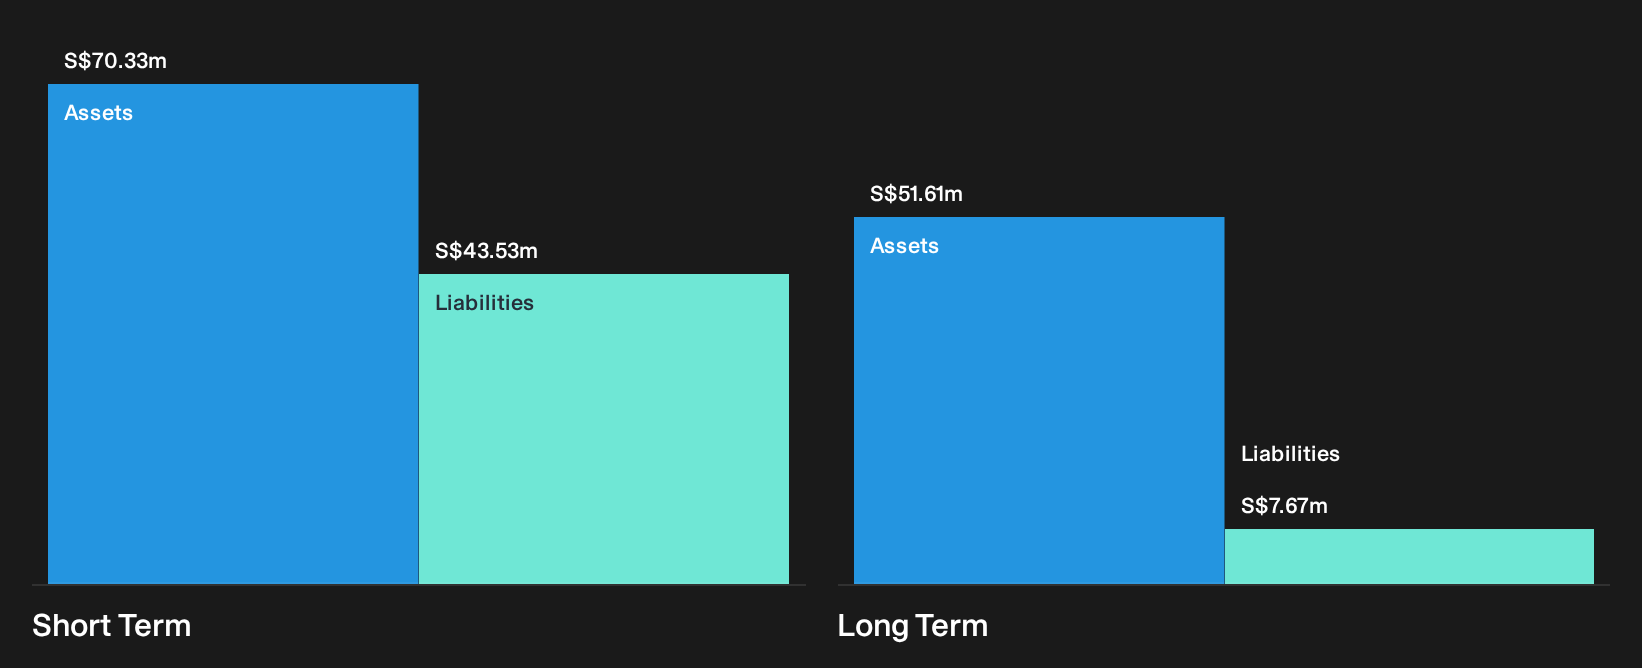
Zicom Group Limited, with a market cap of A$34.49 million, has demonstrated financial prudence by reducing its debt to equity ratio from 29.7% to 16.6% over five years and maintaining more cash than total debt. The company's short-term assets significantly exceed both short and long-term liabilities, indicating strong liquidity. However, recent earnings have declined sharply by 31.3%, with revenue dropping to SGD 95.11 million from SGD 135.77 million the previous year, impacting net income adversely as well. Despite high-quality past earnings and no shareholder dilution recently, volatility remains a concern for potential investors in penny stocks seeking stability.
- Unlock comprehensive insights into our analysis of Zicom Group stock in this financial health report.
- Assess Zicom Group's previous results with our detailed historical performance reports.
Key Takeaways
- Get an in-depth perspective on all 395 ASX Penny Stocks by using our screener here.
- Curious About Other Options? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com