


What Wrangler Blue Bell Launch Means For Kontoor Brands Shares
- Wrangler, part of Kontoor Brands, launched the premium Blue Bell Collection in September 2026. This limited capsule features raw Japanese selvedge denim, full grain suede, shearling outerwear, and heritage inspired details priced between $399.99 and $1,399.99.
- The collection leans into Wrangler’s Blue Bell workwear roots while moving firmly upmarket. It signals a push toward higher price points, craftsmanship focused storytelling, and potentially richer product mix within Kontoor Brands’ denim and outerwear portfolio.
- We will now look at how Kontoor Brands’ investment narrative could be affected by Wrangler’s premium Blue Bell heritage capsule.
Kontoor Brands Investment Narrative Recap
To own Kontoor Brands, you need to believe legacy labels like Wrangler and Lee can keep earning their place in wardrobes while Helly Hansen and premium capsules add new layers of demand. The key near term swing factor is whether earnings growth can continue even as analysts expect top line pressure and revenue contraction over the next few years.
The biggest operational risk right now sits in that gap between earnings relying on margin work and brands that still face fashion and channel shifts. The Blue Bell launch looks directionally consistent with a richer mix story, but by itself it is unlikely to materially change the core risk around slower or declining volumes.
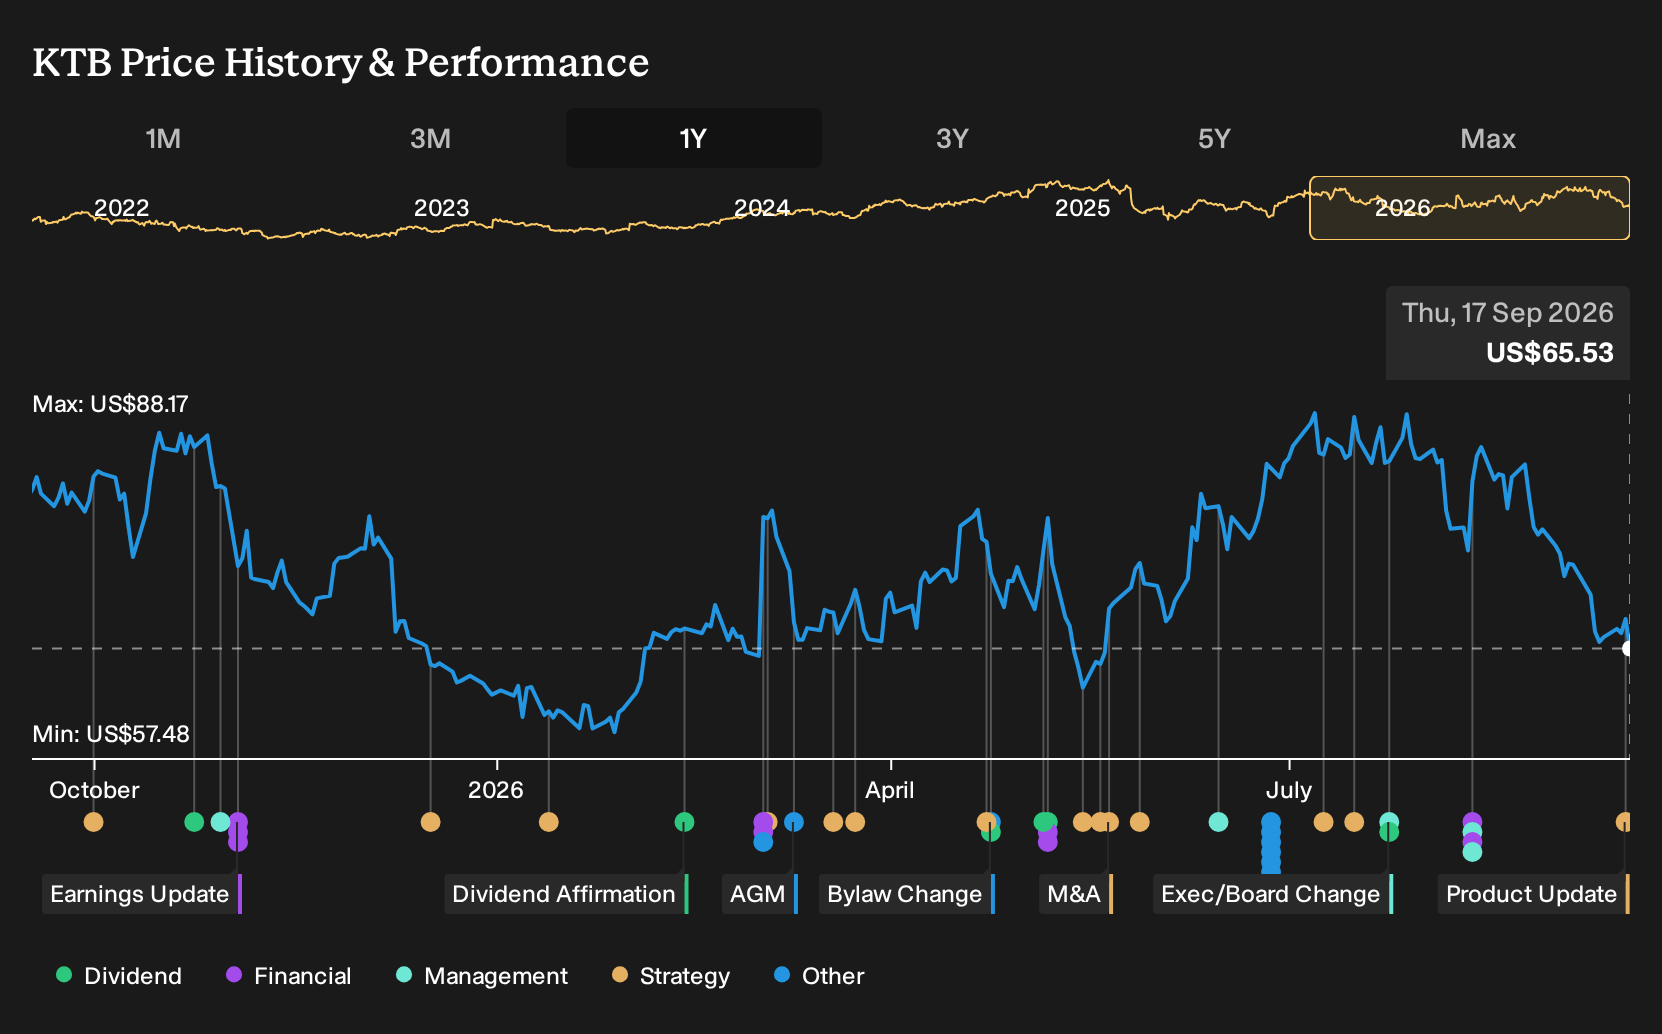
The recent Blue Bell Collection announcement is most relevant because it ties directly into Kontoor Brands aiming for higher quality earnings from a more premium assortment. Wrangler is leaning on heritage and craftsmanship, and the business is already showing 37.4% earnings growth over the past year and trading on a P/E of 12.9x.
For you as a shareholder, the question is execution. Limited high ticket capsules and Helly Hansen expansion need to offset pressure where analysts expect revenue to decline 17.5% a year while earnings are forecast to grow about 11% annually. That tension between mix and volume is the real catalyst to watch.
Kontoor Brands Forecast Mix Versus Volume
Kontoor Brands' analyst playbook leans heavily on margin work rather than expanding the top line. Revenue is projected to decline 7.7% each year over the next three years, while profit margins are assumed to lift from 8.1% today to 14.5% by 2029. That framing matters when you think about Wrangler's Blue Bell capsule, because a premium push fits a world where higher price points and richer gross profit have to offset lower unit volumes.
On the earnings side, the consensus points to US$393.2 million by 2029 against US$276.6 million today. That is roughly a US$116.6 million step up in profit, even with shrinking sales, which implies a mix of higher margin assortments, cost work and some help from Helly Hansen integration. For you as an investor, the question is whether heritage driven premium lines like Blue Bell can be scaled without losing the mass reach that supports current earnings power.
To reconcile all of this with the current share price, analysts are effectively asking you to underwrite a richer margin structure on a smaller revenue base. The model assumes a P/E move from 16.6x today to 17.2x on those 2029 earnings, which is still below the 19.3x multiple used for the broader US Luxury peer group. Premium denim capsules, targeted outerwear and tighter distribution would need to play into that story by pushing average prices higher while keeping brand health intact.
Wrangler's Blue Bell launch fits that narrative as a proof point. It leans into heritage, craftsmanship and limited runs in a way that can support higher ticket prices, which aligns with analysts expecting profit margins to expand even as sales are forecast to contract. In that context, the capsule is less about sheer revenue and more about testing how far Kontoor Brands can stretch the Wrangler franchise upmarket without eroding its workwear credibility.
Kontoor Brands' analyst narrative points to revenues of US$2.7b and earnings of US$393.2 million by 2029. This sits alongside a projected yearly revenue decline of 7.7% and implies an earnings increase of about US$116.6 million from current earnings of US$276.6 million.
Uncover why Kontoor Brands' fair value indicates a 47% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Kontoor Brands very differently. They were already modeling revenues of US$2.9b and earnings of US$392.0 million by 2029, with a P/E of 23.8x on those profits. If premium capsules like Blue Bell resonate, or disappoint, those upbeat forecasts could shift, so you should weigh both narratives.
Explore 3 other Kontoor Brands fair value estimates, including one that suggests potential upside of up to 74% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kontoor Brands research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kontoor Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kontoor Brands' overall financial health at a glance.
Looking For More Kontoor Brands Style Ideas?
If the Wrangler Blue Bell capsule has you thinking about what else might be hiding in plain sight, it can help to line Kontoor Brands up against other opportunities with different strengths and risk profiles using the Simply Wall St Screener.
- For investors who prioritize strong fundamentals and cash buffers, start with a list of solid balance sheet and fundamentals (23 results) that can better withstand rough patches.
- If dependable income is your focus, scan a curated set of 6 dividend fortresses that might complement a position in Kontoor Brands.
- To widen the search beyond well covered tickers, broaden your watchlist with a 16 high quality undiscovered gems that could sit earlier in the story arc.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com