


Is Ipsos (ENXTPA:IPS) Reasonable After The Horizons Plan Push?
Ipsos shares have drifted over the past few years, while the business pushes ahead with its Horizons plan under new leadership. The question now is whether the current price around €34.66 still lines up with what the company earns.
- The stock has declined 12.0% over the past three years, which puts the focus squarely on whether the earnings profile justifies staying invested.
- Kelly Beaver’s push to accelerate the Horizons strategic plan, with a heavier emphasis on global solutions, artificial intelligence and data integration, may support different expectations for Ipsos’s future profit mix and timing.
- The analysts covering Ipsos have run their own numbers. See what analysts think Ipsos's shares could be worth.
The stock's next move may depend on whether Ipsos’s current market price is supported by its earnings power today and the profit path investors are factoring in.
If you want to stress test the same earnings question that hangs over Ipsos against a wider field, line it up beside 173 high quality undervalued stocks.
Is Ipsos Still Cheap on Earnings?
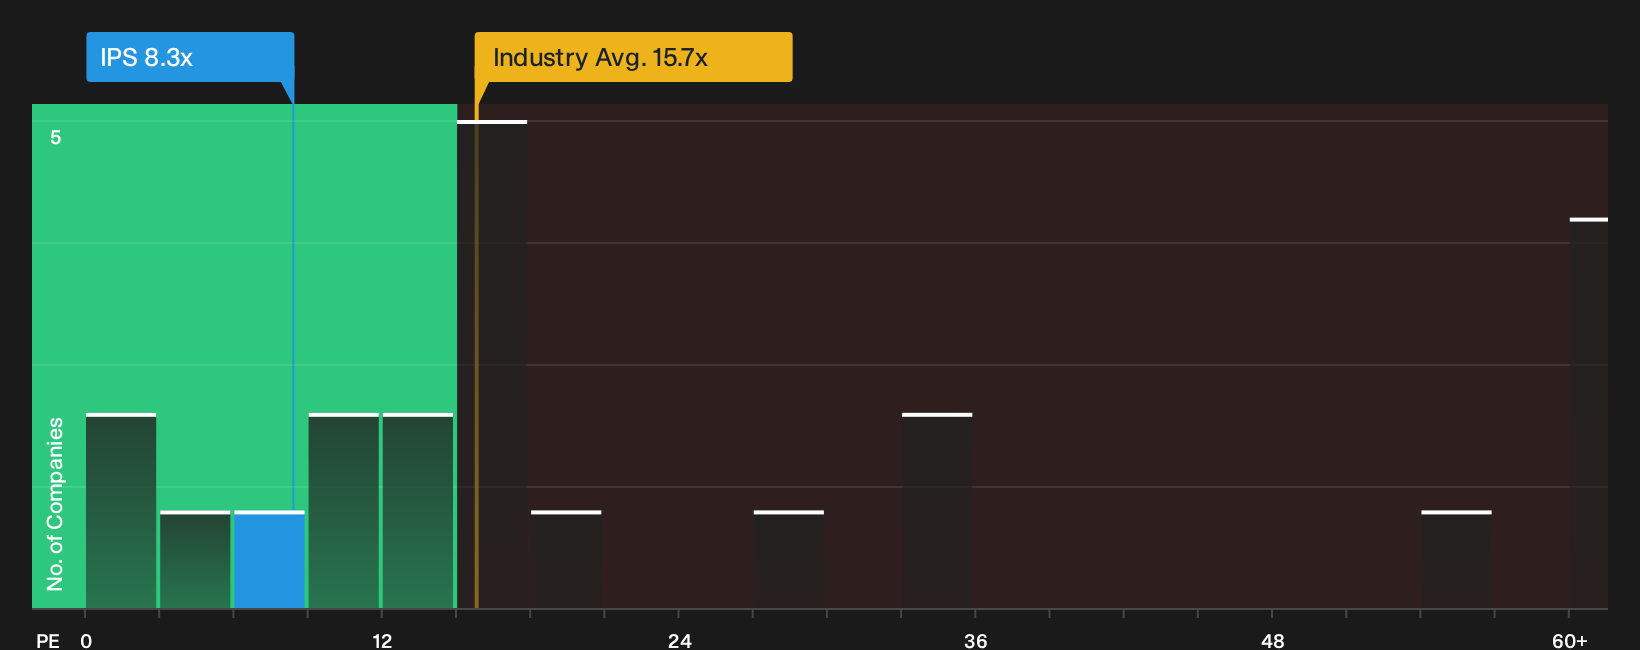
The P/E ratio suits Ipsos because earnings still sit at the center of how investors judge its progress under the Horizons plan. At roughly 8.3x earnings, Ipsos trades below the media industry average of about 14.9x and also under the peer group near 11.0x. Within this framework, the fair benchmark that blends its sector, profitability profile and risk suggests the current P/E aligns more with a discounted label than a premium one.
Because Kelly Beaver is placing greater emphasis on global solutions, AI and data integration after a softer year, the gap between Ipsos’s 8.3x multiple and those wider reference points indicates that the market is cautious about how quickly those efforts translate into earnings. If that caution proves too harsh, the present P/E could imply the stock is undervalued on this earnings yardstick. Explore the numbers behind Ipsos's P/E valuation.
The Ipsos Narrative: What Would Justify Today's Price?
Narratives on Ipsos pick up where the P/E question leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to end up worth materially more or less than today’s price. Each scenario links a fair value estimate to a clear storyline about Ipsos' potential catalysts and key risks, so you can track over time which version of events seems to be playing out in the real world on Simply Wall St's Community page.
One of the top community narratives on Ipsos: 11% undervalued
"While Ipsos is making strategic investments in AI-driven research tools, the growing adoption of AI and automation by clients themselves may ultimately reduce reliance on traditional external market research..."
Discover why this Narrative puts Ipsos at 11% undervalued.
One more Ipsos check that sits beyond the P/E
Price and earnings only tell part of the story for Ipsos, because our broader review has highlighted specific concerns that deserve your attention before you rely on the valuation alone. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com