


Will Quarterly Earnings Change ABM Stock Narrative
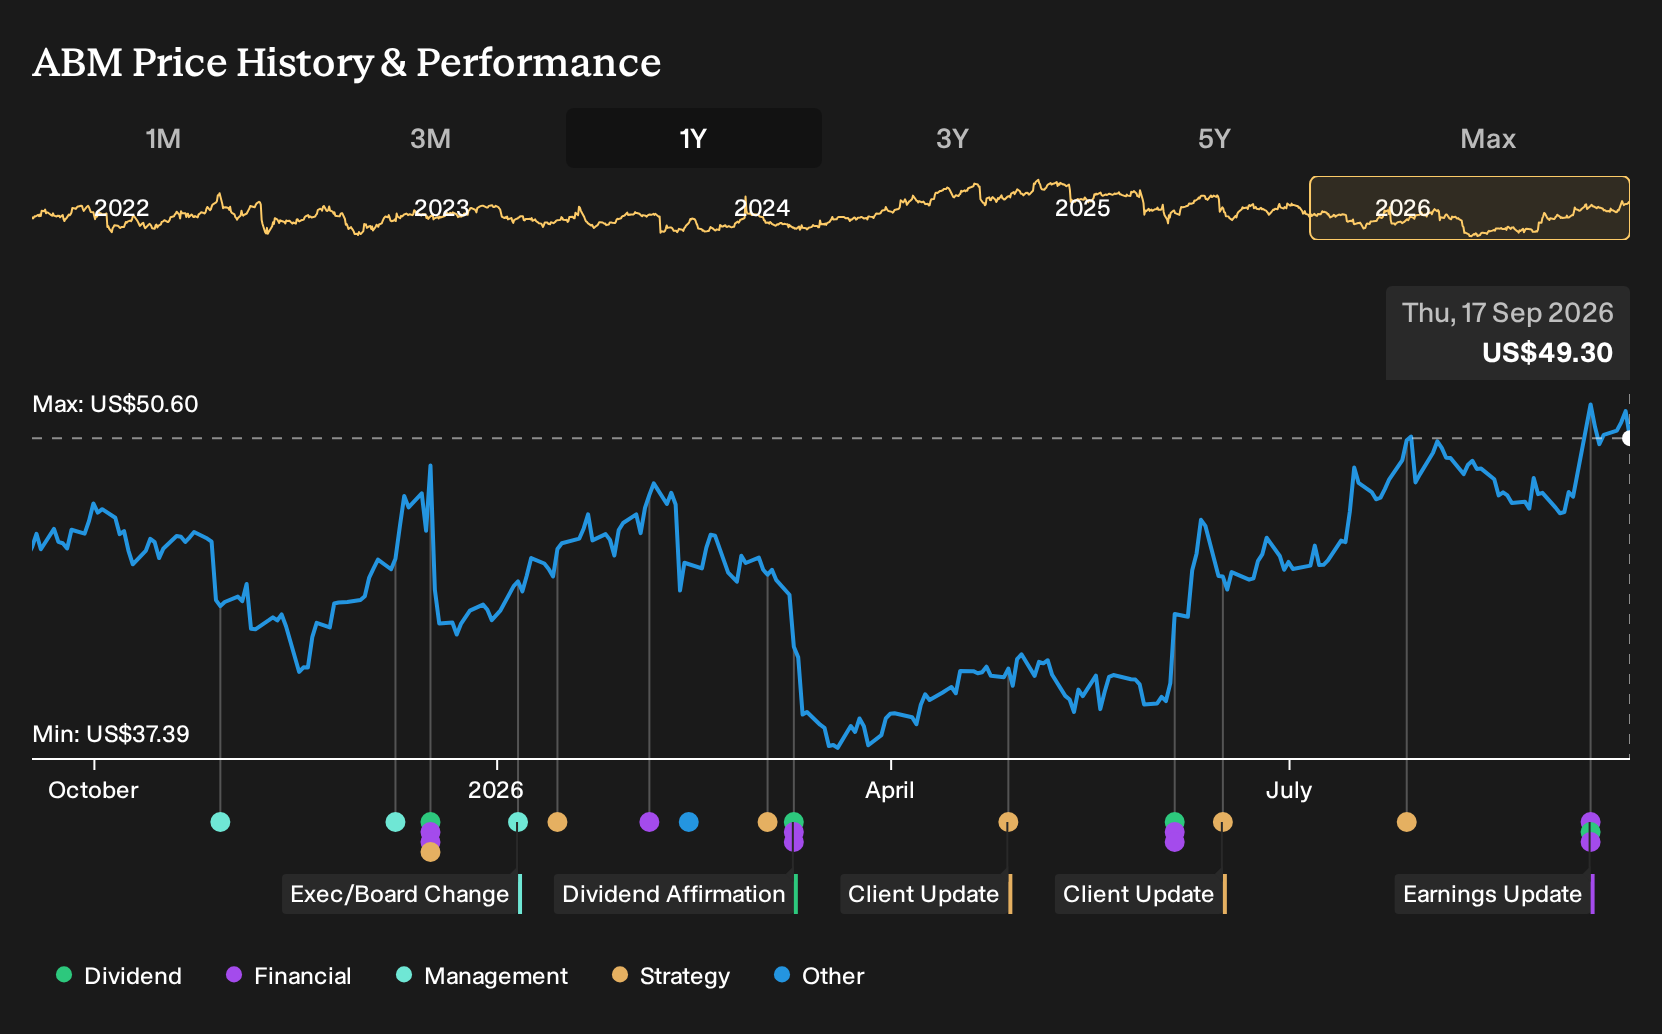
- ABM Industries reported third quarter 2026 sales of US$2,317.1 million and net income of US$49.7 million, with earnings per share from continuing operations of US$0.84. The company also confirmed that full year 2026 revenue is still expected toward the upper end of its prior 4% to 5% growth range.
- The company has completed a multi year repurchase of 11,720,000 shares for US$512.79 million and affirmed a quarterly dividend of US$0.29 per share payable in November 2026. Together, these actions highlight how ABM Industries is balancing shareholder returns with its facility services growth ambitions.
- We will look at how ABM Industries' investment narrative aligns with the confirmed top end revenue outlook after its latest earnings release.
Scan how ABM Industries’ latest earnings, buyback completion, and dividend policy compare with other cash generative operators by reviewing our curated list of solid balance sheet and fundamentals (23 results).
ABM Industries Investment Narrative Recap
For ABM Industries, the big picture investors would need to accept is that demand for outsourced facility, infrastructure, and mobility services remains steady enough to support mid single digit revenue growth and incremental margin progress. The third quarter results, with US$2,317.1 million in sales and US$49.7 million in net income, indicate an operation that is still scaling its existing platform.
The confirmed expectation that 2026 revenue will track toward the top of the 4% to 5% range keeps the near term catalyst centered on execution of large contracts while managing cost pressures in Business & Industry and Manufacturing & Distribution. Margin compression from pricing concessions and shorter term work remains the key risk if competitive intensity stays high.
The most relevant recent data point is the third quarter earnings release. ABM Industries reported year on year increases in sales and earnings per share from continuing operations for both the quarter and the first nine months, with basic EPS from continuing operations at US$0.84 for the quarter and US$2.22 for the nine month period.
These figures are consistent with the reaffirmed revenue outlook toward the upper end of 4% to 5% growth for fiscal 2026. This keeps investors focused on whether contract wins and cost savings can offset ongoing margin headwinds in challenged office markets. Execution on restructuring and pricing discipline will likely influence how quickly any operational changes appear in reported profitability.
ABM Industries' current earnings are US$166.4 million and analysts are assuming revenue will grow by 3.3% per year, with forecasts pointing to US$10.1b in revenue and US$272.9 million in earnings by 2029. This implies an increase of about US$106 million from earnings today.
Uncover why ABM Industries' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean on a different catalyst. They focus on ABM Industries’ push into microgrids, data centers and chip fabs, which fed forecasts back in March 2026 for revenue of about US$10.0b and earnings near US$284.8 million by 2029. Those estimates did not yet factor in this quarter’s buyback completion or guidance confirmation, so you may see those narratives shift as new information lands.
Explore another ABM Industries fair value estimate, including one that suggests as much as 90% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ABM Industries research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ABM Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABM Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond ABM Industries?
Once you have a view on ABM Industries, it can help to widen the net and compare it with businesses that show different combinations of value, resilience, and income potential using the Simply Wall St Screener.
- If value is the priority, scope out companies that combine quality fundamentals with share prices that still look compressed through the 29 high quality undervalued stocks.
- If capital preservation comes first, focus on businesses with sturdier financial positions and lower risk profiles using the 11 resilient stocks with low risk scores.
- If regular income matters most, filter for companies offering higher dividend yields and consistent payout histories via the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com