


AXA (ENXTPA:CS) Stock Looks Fully Priced As Its 159% Run Continues
AXA has delivered strong share-price gains in recent years, which puts a spotlight on whether the current valuation can still be backed up by its earnings power. With the stock trading around €45.06 at the last close, investors are increasingly asking how much of the insurer's earnings story is already reflected in that price.
- Over the past 5 years AXA has returned 158.9%, which makes the question of what earnings justify today's level far more important for anyone considering the stock now.
- Management is focusing on AI driven efficiency and organic growth plans that may support future profitability, so expectations around margins and capital generation now play a key role in how the earnings multiple is interpreted.
- There is a second opinion on AXA worth weighing. See what analysts think AXA's shares could be worth.
The issue now is whether AXA's current share price can be explained by the earnings it generates today and what investors expect those profits to look like over time.
If you are weighing AXA's earnings driven story against similar opportunities, it can help to compare it directly with 77 profitable AI stocks that aren't just burning cash.
Has AXA Run Too Far on Earnings?
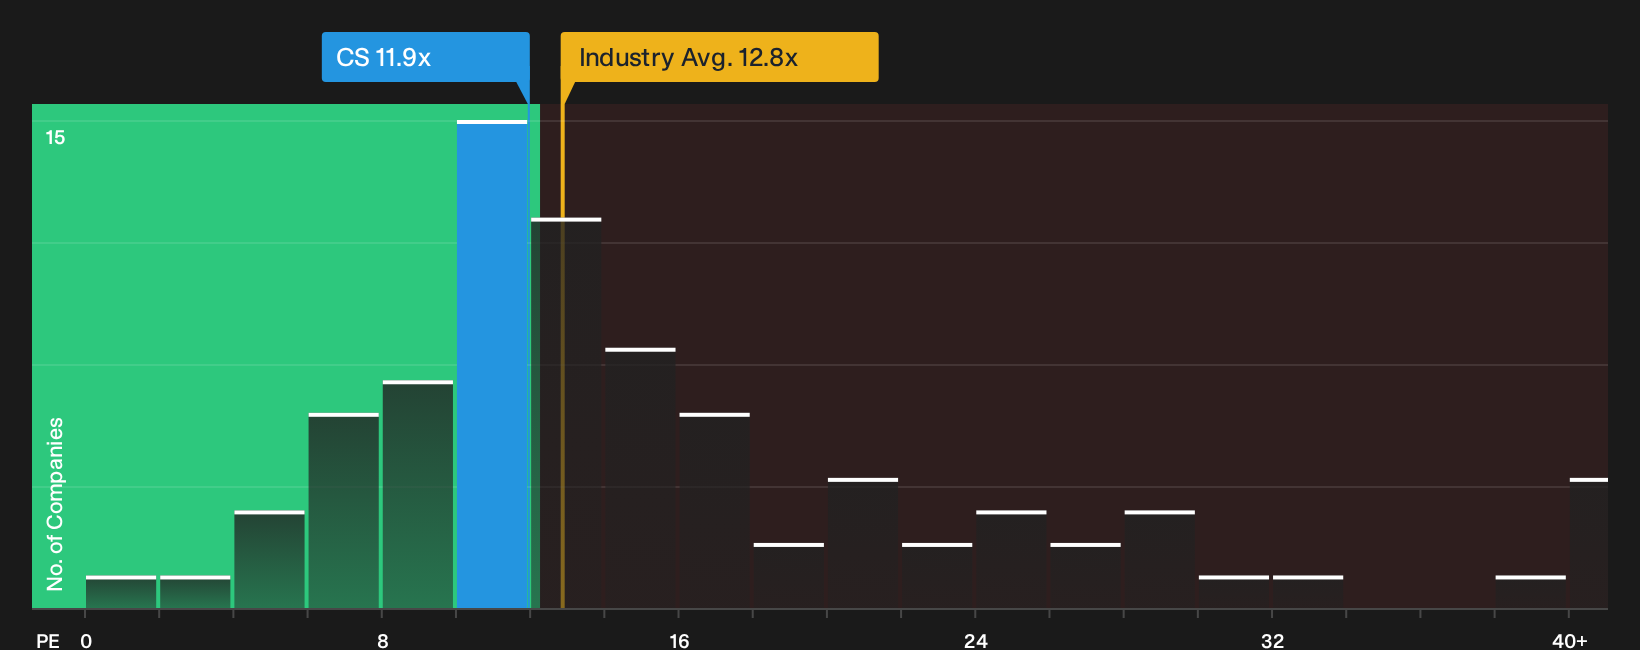
A P/E ratio usually suits an insurer like AXA, because earnings are the main anchor for what shareholders actually receive over time. AXA currently trades on a P/E of about 11.9x, which is slightly above the Insurance industry average of roughly 11.8x and a bit below the peer group at around 13.1x.
On the fair-value model that adjusts for AXA's own growth outlook, profitability and risk profile, the current P/E sits above the level that framework would point to, so the shares screen as overvalued on this metric. Because management is leaning hard into AI and efficiency programs that are already flagged in recent announcements, a lot of that potential earnings uplift may already be embedded in this multiple. Explore the numbers behind AXA's P/E valuation.
The AXA Narrative: What Would Justify Today's Price?
Narratives on AXA pick up where the valuation question leaves off, by spelling out the specific paths for growth, profitability and earnings that would need to play out for the shares to look meaningfully higher or lower than today. Each view links its number to a concrete stance on how AXA's growth, margins and risk profile might evolve, giving you a reference point that can be checked again as fresh information comes through.
Community views on AXA are split between those who see fresh upside in the AI and climate themes and others who think execution assumptions already stretch the story.
Bull case: 32% undervalued
"Group wide investment in artificial intelligence to refine pricing, claims handling and fraud detection, supported by a very large internal data set…"
Discover why this Narrative puts AXA at 32% undervalued.
Bear case: 6% overvalued
"Some bearish views may focus on valuation risk if current P/E multiples already reflect optimistic assumptions on earnings and discount rates…"
Explore why this Narrative puts AXA at 6% overvalued.
One more AXA angle worth checking before you move on
All the numbers still sit on top of one crucial factor: the people steering AXA and the way their pay is structured, and that piece has not been unpacked here. See who runs AXA and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com