


Migdal Insurance And Financial Holdings (TASE:MGDL) Could Be 2% Undervalued Following Its Rally
Migdal Insurance and Financial Holdings (TASE:MGDL) has drawn fresh attention after recent price action left the shares trading at an intrinsic discount of about 2%, raising questions about how the current valuation aligns with its fundamentals.
The recent move to ₪21.39 comes on top of strong momentum, with a 30-day share price return of 19.23% and a 90-day gain of 29.40%. The 1-year total shareholder return of 102.37% and 5-year total shareholder return of 362.40% show how Migdal Insurance and Financial Holdings has already rewarded patient investors, while the current intrinsic discount hints at how sentiment toward its risk and growth profile is still evolving.
Scan for other insurance and financial groups showing similar price momentum and a potential valuation gap by checking the hand picked 173 high quality undervalued stocks.
The rush up to ₪21.39 puts Migdal Insurance and Financial Holdings in an awkward spot. Do you lean into the current momentum, or wait in case that 2% discount widens before buying in?
Price-to-Earnings of 11.9x: Is it justified?
Migdal Insurance and Financial Holdings is currently on a P/E of 11.9x, which prices recent momentum into ₪21.39 yet still leaves shares slightly below some valuation checks.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors are willing to pay for each unit of profit. For an insurer and financial services group like Migdal Insurance and Financial Holdings, that multiple often reflects expectations around underwriting discipline, capital allocation and the stability of profit streams more than rapid top line expansion.
Earnings have grown by 10.8% per year over the past 5 years and profit margins have moved from 12.1% to 14.9%, which suggests the business has been turning more of its revenue into bottom line profit. Combined with high quality earnings and a 17.5% return on equity that is framed as low by the 20% benchmark in the data, the current P/E indicates that the market is paying up for improved profitability without stretching into extreme territory.
Against peers, the story is mixed. The P/E of 11.9x is below the peer average of 12.6x, which points to a discount relative to similar companies. However, it is described as expensive compared with the broader Asian Insurance industry average of 11.4x, so the market is valuing Migdal Insurance and Financial Holdings slightly higher than the wider regional group.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 11.9x (ABOUT RIGHT)
Still, Migdal Insurance and Financial Holdings depends heavily on life and long term savings revenue, and any hit to investment performance or regulation could quickly reprice that optimism.
Find out about the key risks to this Migdal Insurance and Financial Holdings narrative.
Another View on Migdal Insurance and Financial Holdings
The P/E work suggests Migdal Insurance and Financial Holdings looks roughly in line with its recent performance, yet the SWS DCF model comes in slightly higher, with a future cash flow value of ₪21.93 versus the current ₪21.39. That 2.4% gap is small. Does it hint at a modest opportunity, or is it just noise?
Look into how the SWS DCF model arrives at its fair value.
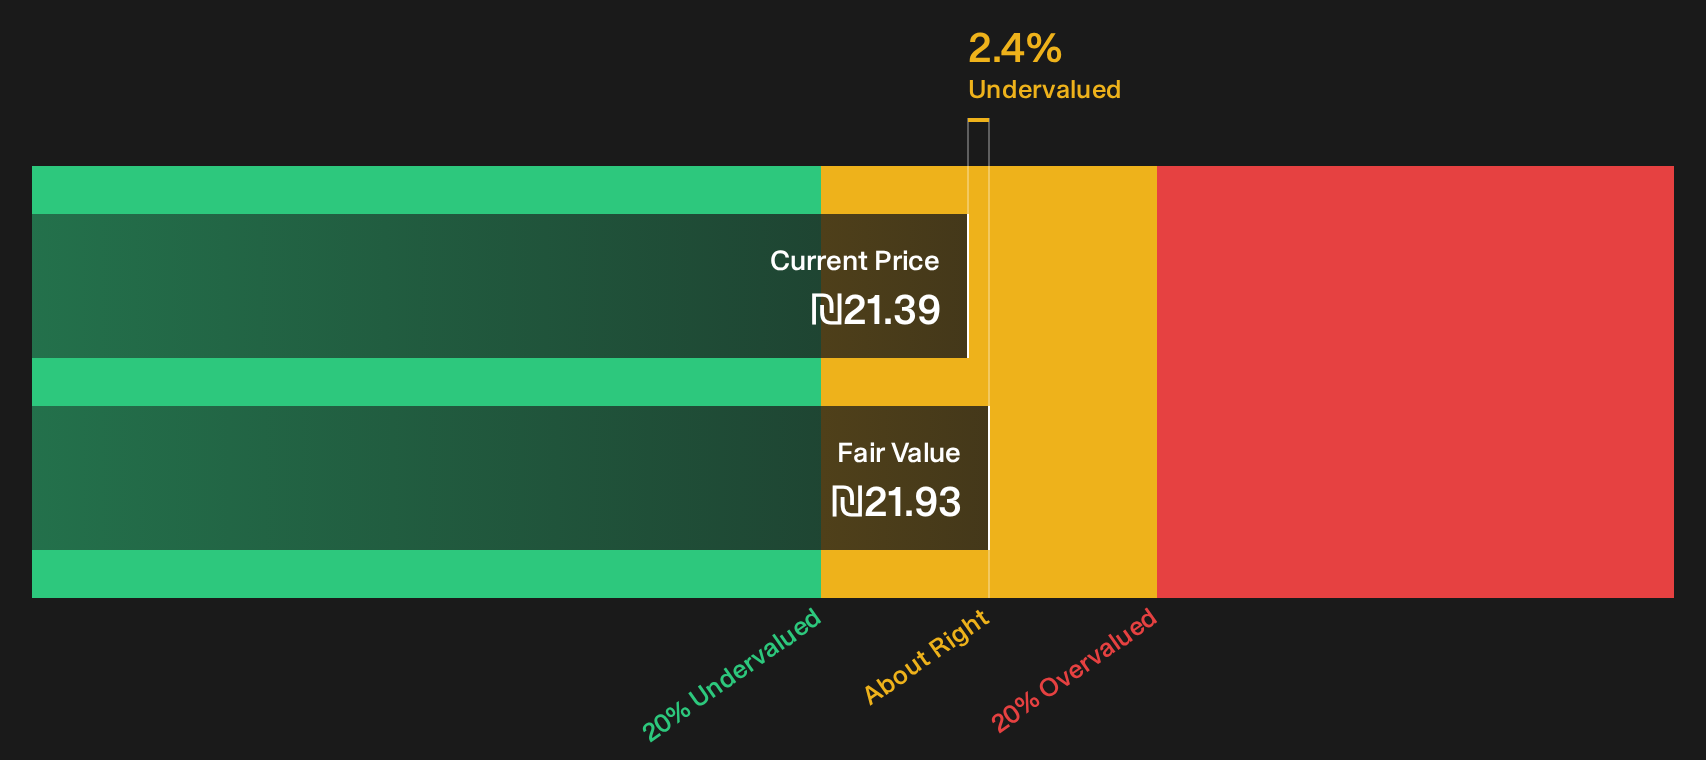
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Migdal Insurance and Financial Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The numbers paint a constructive picture around Migdal Insurance and Financial Holdings, so the key question now is what you make of those signals. Take a closer look at the full breakdown of potential upsides in the 2 key rewards.
Looking for more investment ideas beyond Migdal Insurance and Financial Holdings?
If Migdal Insurance and Financial Holdings has sharpened your focus on valuation, do not stop here. Use powerful screeners to uncover fresh opportunities that fit your style.
- Target dependable cash generators by scanning a list of solid balance sheet and fundamentals (196 results) that can handle setbacks without relying on hopeful stories.
- Hunt for mispriced opportunities with the 618 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
- Prioritize stability over drama by reviewing a 105 resilient stocks with low risk scores that aims to keep surprises to a minimum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com