


WEX (WEX) Stock Looks Pricey As Its 32% Run Continues
WEX has logged a strong run this year, which naturally raises a question for anyone looking at the stock today. Are you now paying a price that its current earnings can genuinely support, or has the share move run ahead of the underlying profit power of the business?
- The stock is up 31.5% year to date, which puts fresh pressure on the earnings picture to justify the higher valuation investors are now paying.
- The company’s model in corporate payments and fleet services leans heavily on fee income and transaction volumes, so expectations for future profitability and cash conversion can have a direct influence on how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on WEX worth weighing. See what analysts think WEX's shares could be worth.
The stock’s next move may depend on whether today’s share price can be squared with what WEX currently earns and is expected to earn over time.
If you are weighing whether WEX’s 31.5% year to date move is justified by its earnings, it can help to compare that profile against 29 high quality undervalued stocks.
Has WEX Run Too Far on Earnings?
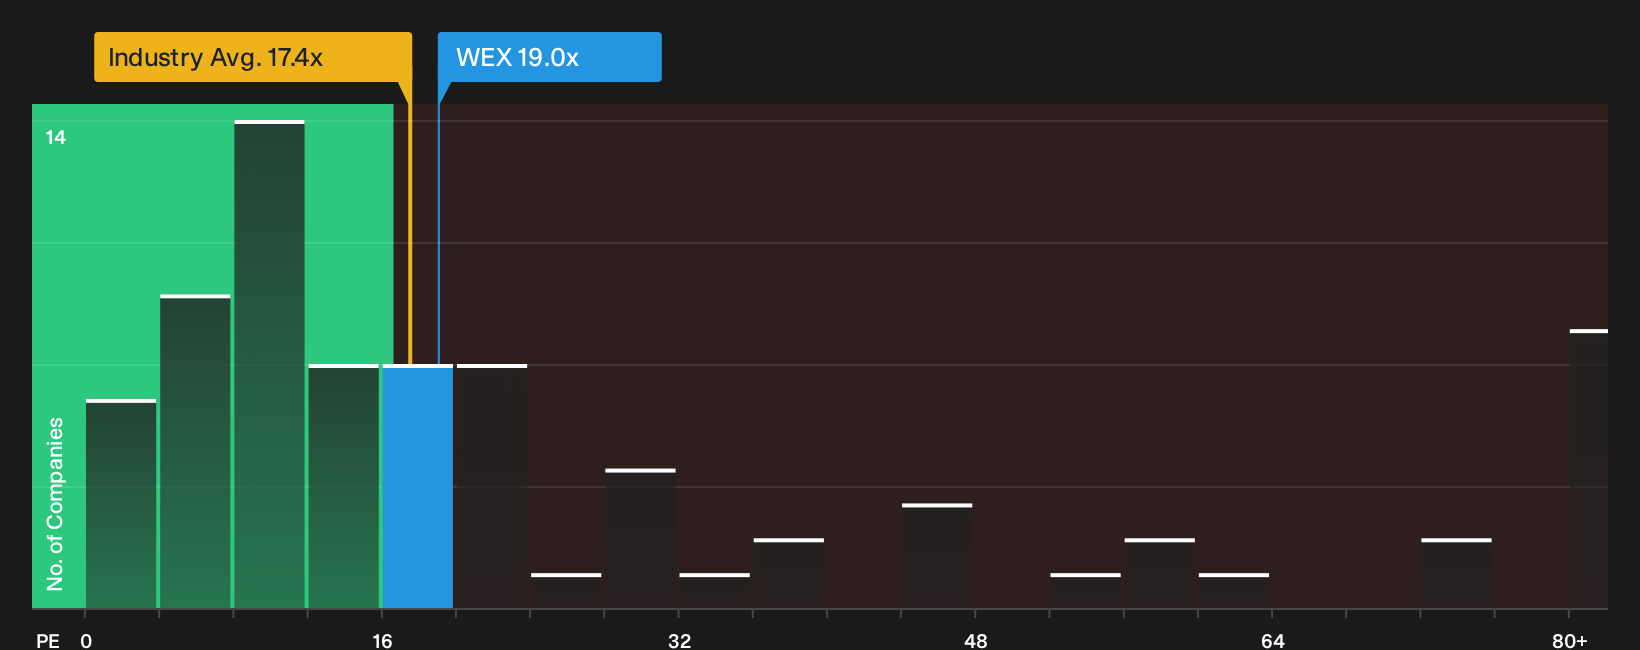
P/E works well for WEX because earnings are a key yardstick for a fee and transaction driven financial platform. On that yardstick, WEX trades on a P/E of 19.0x, above both the Diversified Financial industry average of 17.4x and the peer group at 17.4x. That means you are paying a richer price per dollar of reported profit than the typical stock in its space.
The valuation model that blends WEX’s growth profile, margins, size and risk points to a lower P/E as a fair anchor, so the current 19.0x screens as overvalued on this framework. For an investor, the key question is whether the quality and durability of those earnings justify paying this premium multiple compared with what similar companies trade on. Explore the numbers behind WEX's P/E valuation.
The WEX Narrative: What Would Justify Today's Price?
For WEX, Simply Wall St Narratives sit between the current P/E debate and the bigger question of what kind of growth, margins and earnings path would need to play out for the stock to end up worth a lot more or a lot less than today’s level, and they live on Simply Wall St’s Community page. Instead of stopping at a single valuation output, they unpack the future conditions that figure rests on so you can later check whether those assumptions are actually playing out.
One of the top community narratives on WEX: 11% undervalued
"Continued product innovation in areas like virtual card solutions, embedded payments, flexible funding, and automation tools enables WEX to expand into higher-margin, tech-driven segments..."
Discover why this Narrative puts WEX at 11% undervalued.
For WEX, the share price is only one piece of the story
The next thing to weigh is who is actually steering WEX and how their pay packets line up with your interests as a shareholder. See who runs WEX and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com