


SLM (SLM) Stock Could Be Reasonable With Earnings Still Discounted
SLM Corporation has delivered a powerful 3 year share price run, yet the stock has drifted lower over the past year, which puts fresh attention on whether its current price still lines up with the earnings behind it. For anyone considering SLM today, the key issue is how much of the past gains already reflect what the business earns.
- SLM has climbed 94.5% over the past 3 years, so a lot of the discussion now is about whether that move already bakes in what its profits can reasonably support.
- The group depends heavily on how effectively it turns its loan book into consistent earnings, which can influence how investors think about the durability of its profit stream and the price they are willing to pay for it.
- Your read on SLM is one view; the desks covering it have another. See what analysts think SLM's shares could be worth.
The issue now is whether SLM's current share price of US$24.99 is justified by the earnings power that the business is generating today.
If you want to test the same earnings question you are asking of SLM across a wider set of ideas, scan through 29 high quality undervalued stocks.
Does SLM Look Undervalued on Earnings?
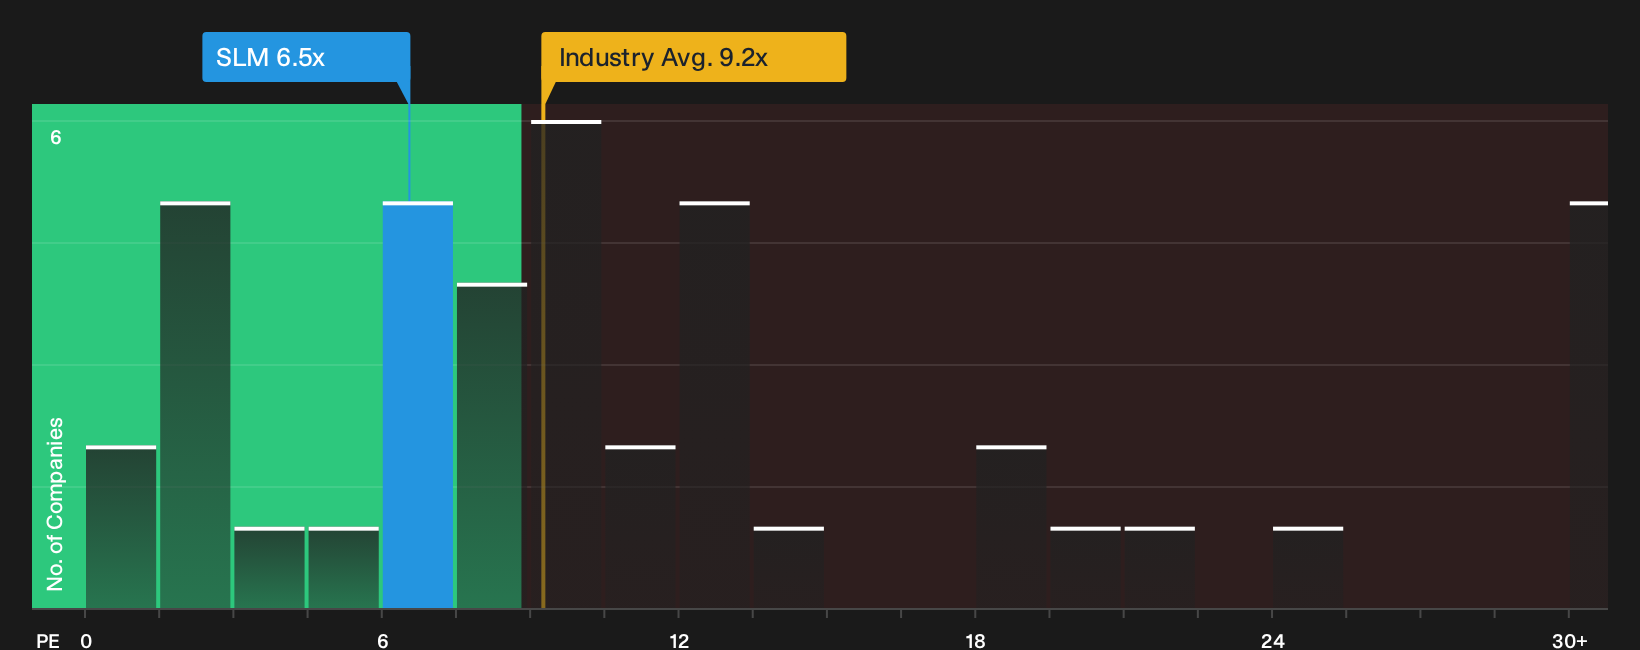
P/E fits SLM well because the business is built around earning a return on its loan book, which shows up directly in net income. At a P/E of about 6.5x, SLM trades at a lower earnings multiple than the consumer finance industry average of roughly 9.2x and the peer group near 11.0x. For a lender where headline earnings are a primary reference point for many investors, that is a meaningful gap.
The fair value model that blends SLM’s growth expectations, profitability profile and risk suggests a higher P/E would be typical for this kind of earnings stream. That places the current multiple below the level implied by those fundamentals. This, in turn, points to the stock pricing in a degree of caution on future earnings quality or regulatory and credit risks. For anyone weighing SLM today, the key question is whether that discount compensates for those uncertainties or reflects them too aggressively. Explore the numbers behind SLM's P/E valuation.
The SLM Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle around SLM leaves off by spelling out what would need to happen to the company’s future growth, margins and earnings for the stock to be worth materially more or less than today’s price. Each scenario links its number to a clear view on how SLM's growth, profitability and risk profile could evolve, giving you something concrete to revisit as fresh information arrives on the Community page.
Community views on SLM split between those who see a discounted lender reshaping its model and others who think current enthusiasm already prices in the story.
Bull case: 29% undervalued
"Credit underwriting metrics such as a 756 average FICO score at approval, a 95% cosigner rate and private education loan net charge offs of 1.95% of loans in repayment support portfolio quality…"
Discover why this Narrative puts SLM at 29% undervalued.
Bear case: 9% overvalued
"The strategy of aggressive capital return via buybacks combined with modest balance sheet growth, in the face of potentially volatile gain on sale economics and ABS spread cycles, could leave limited capital flexibility to absorb adverse credit or funding shocks…"
Explore why this Narrative puts SLM at 9% overvalued.
For SLM, who is steering the ship and how are they rewarded?
Valuation only tells part of the SLM story, because the people setting lending choices, capital returns and risk appetite, and the way their pay is structured, can tilt outcomes in ways the numbers here do not show. See who runs SLM and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com