


Is Extreme Networks (EXTR) Undervalued Following Its Extreme Agent ONE Coworker Launch?
Extreme Networks (EXTR) is putting its agentic AI ambitions into production with the general availability of Extreme Agent ONE Coworker, a subscription add-on now live for Platform ONE customers worldwide.
Recent trading has been choppy for Extreme Networks, with the share price up 1.92% over the last day and 5.34% across the past week, yet down 28.90% on a 90 day share price basis and slightly negative on a 1 year total shareholder return. This comes even after a 129.76% total shareholder return over five years, which points to longer term momentum that has cooled recently.
Spot similar AI-focused opportunities beyond Extreme Networks by reviewing the curated 32 AI small caps that could be building the next wave of enterprise infrastructure.Extreme Networks now has a fresh AI story and a share price that has pulled back sharply over 90 days. Is this the moment to step in, or does waiting for a cleaner valuation case make more sense?
Most Popular Narrative: 33% Undervalued
Extreme Networks is currently trading at $22.31, while the most followed narrative anchors fair value at $33.50. That gap puts the focus squarely on whether its AI and cloud shift can support the assumptions behind that target.
Rapid scale-out of subscription-based, cloud-managed and MSP commercial models, enabled by unique consumption-based billing and automated licensing features, is driving growth in recurring revenues, higher customer retention, and better earnings visibility.
Recent large strategic wins, particularly in APAC and EMEA with government and Fortune 500 customers (e.g., Japanese judiciary, John Deere), are establishing Extreme as a credible upmarket competitor, increasing cross-selling opportunities, expanding backlog, and strengthening revenue and earnings outlook for FY26 and beyond.
See why 14 investors see Extreme Networks as 33% undervalued.
Result: Fair Value of $33.50 (UNDERVALUED)
Still, the bullish Extreme Networks narrative could be knocked off course if large government deals prove irregular or if bigger rivals lean harder on pricing and product bundles.
Find out about the key risks to this Extreme Networks narrative.
Another View: Extreme Networks Through The P/E Lens
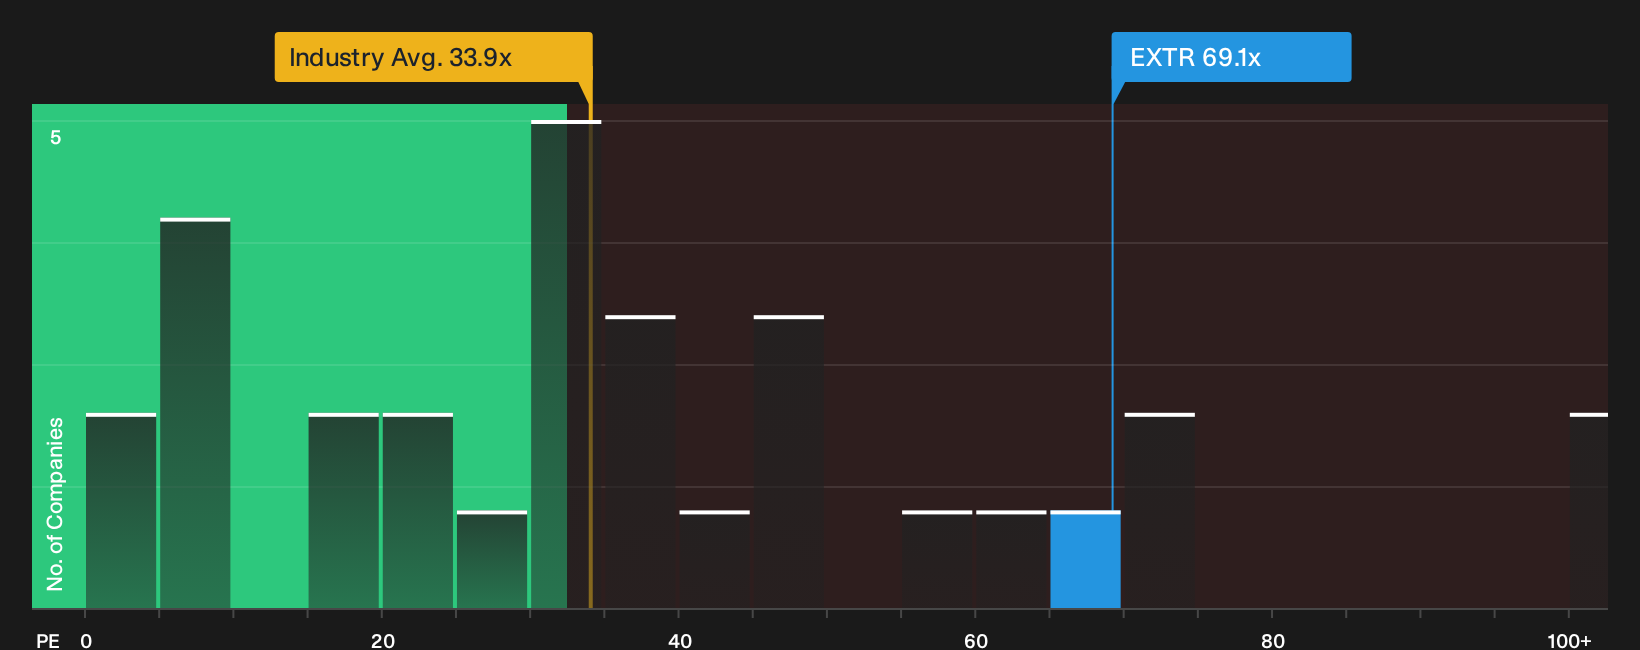
The SWS DCF model points to upside for Extreme Networks, yet the P/E snapshot tells a tougher story. The stock trades on about 69x earnings versus roughly 34x for the wider US Communications group and 42x for peers, well above a fair ratio of 26.6x. That kind of premium can either shrink through a lower share price or grow into the multiple through future delivery, so which path do you think is more realistic?
See what the numbers say about this price in the valuation breakdown here, then weigh it against your own expectations for Extreme Networks over the next few years See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling torn between the optimism around Extreme Networks and the richer P/E multiple on screen is normal. Move quickly from headlines to hard numbers and stress test the bullish points yourself by digging into the 4 key rewards.
Looking For More Investment Ideas Beyond Extreme Networks?
Do not stop your research with Extreme Networks. Broaden your watchlist with focused screens that highlight different types of opportunities other investors might miss.
Use the Simply Wall St Screener to surface fresh ideas that match your style before the crowd catches on.
- Target potential mispricing by scanning a curated set of companies that combine quality fundamentals with compelling valuations using the 29 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with robust finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed opportunities by reviewing a focused lineup of strong fundamentals in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com