


How Investors Are Reacting To ATI (ATI) Record Backlog And Raised Guidance
- ATI Inc. recently presented at Morgan Stanley's 14th Annual Laguna Conference, outlining aerospace and defense demand trends, record backlog levels, and higher 2026 adjusted EBITDA and free cash flow guidance.
- The updated outlook for high teens defense growth and a strong order book gives investors more detail on how ATI’s materials portfolio is tied to long-cycle aerospace and military programs.
- Next, the focus turns to how ATI’s raised guidance and record backlog reshape the existing investment narrative around margins and cash generation.
Compare ATI's momentum in aerospace and defense with a curated list of peers by scanning 37 power grid technology and infrastructure stocks, which are also tied to long-cycle infrastructure and equipment demand.
ATI Investment Narrative Recap
To own ATI, you need to believe the aerospace and defense backlog really can translate into sustained orders, a higher quality mix, and better cash conversion over time. The Laguna conference update, with a record order book and higher 2026 adjusted EBITDA and free cash flow guidance, reinforces that long-cycle thesis rather than changing it.
In the near term, the key swing factor is execution. ATI has to convert that backlog into shipments while managing supply constraints, capital projects, and a high debt load. The biggest risk still sits outside aerospace, where softer industrial and medical demand and tariff pressure can chip away at margins if those end markets stay weak.
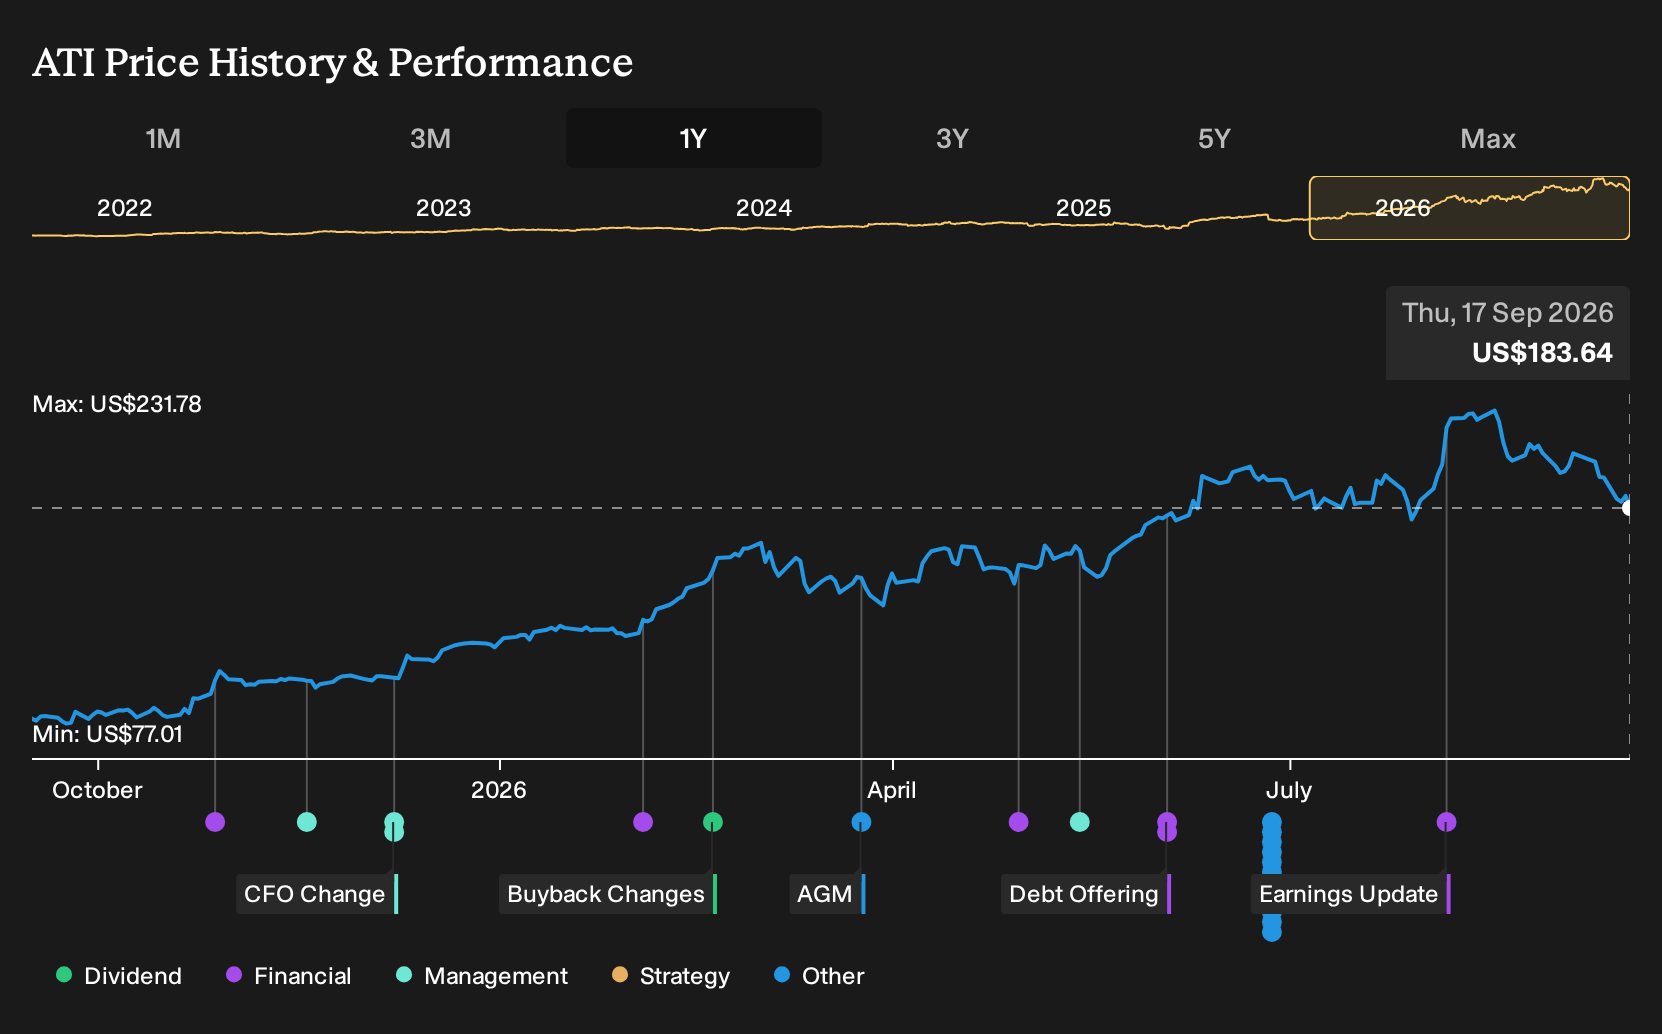
The most relevant fresh data point is ATI lifting its 2026 adjusted EBITDA and free cash flow outlook, alongside a raised full year defense growth guide to the high teens. That development links directly to the current share price move, which is up 64% year to date and well ahead of the broader Aerospace and Defense Equipment group.
This guidance reset puts more attention on whether capacity investments, process upgrades, and long-term aerospace and defense contracts can support the new earnings and cash targets. It also tightens the focus on execution risk. Any stumble in supply chain, capex discipline, or large OEM relationships would matter more now that expectations are higher.
ATI's narrative projects forecast revenue of US$5.9b and earnings of US$874.1m by 2029. This assumes 8.9% yearly revenue growth and an earnings increase of about US$448.6m from current earnings of US$425.5m.
Uncover why ATI's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on ATI focuses on the bullish view that heavy capital spending is a clear earnings catalyst rather than a cash flow risk. The most optimistic analysts were already penciling in revenue of about US$6.7b and earnings near US$1.2b by 2029. That is far above consensus, and the Laguna conference update could eventually push those stories even further apart, so it makes sense to compare several viewpoints before deciding how ATI fits your portfolio.
Explore 4 other ATI fair value estimates, including one that suggests up to 50% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ATI research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ATI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATI's overall financial health at a glance.
Looking For More Investment Ideas Beyond ATI?
If ATI has sharpened your thinking on long-cycle demand and cash generation, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about quality at a sensible entry point, scan a curated set of 29 high quality undervalued stocks that pair strong fundamentals with what may be appealing pricing.
- If capital preservation and balance sheet strength matter to you, filter for companies in the 11 resilient stocks with low risk scores that score well on financial resilience and business stability.
- When you want ideas that fly under the radar, sort through a handpicked pool of 16 high quality undiscovered gems that combine solid business metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com