


Micron Stock Gets New AI Memory Hook With 512GB Server Module
- Micron Technology has announced the first 512GB DDR5 server module running up to 9,200 MT/s and is scaling global capacity, including new assembly and test operations in India, to serve AI data center demand and persistent memory shortages.
- The firm is pairing long-horizon research leadership under new Micron Research Labs head Deirdre Hanford with high-capacity AI memory products and supply agreements. It is reshaping how it allocates capital across R&D, manufacturing and labor at a time of tight industry supply.
- We will now look at how Micron's ultra high capacity 512GB DDR5 module could influence the existing investment narrative around AI memory.
Compare how Micron Technology’s AI memory story stacks up against other potential breakouts in 60 AI infrastructure stocks.
Micron Technology Investment Narrative Recap
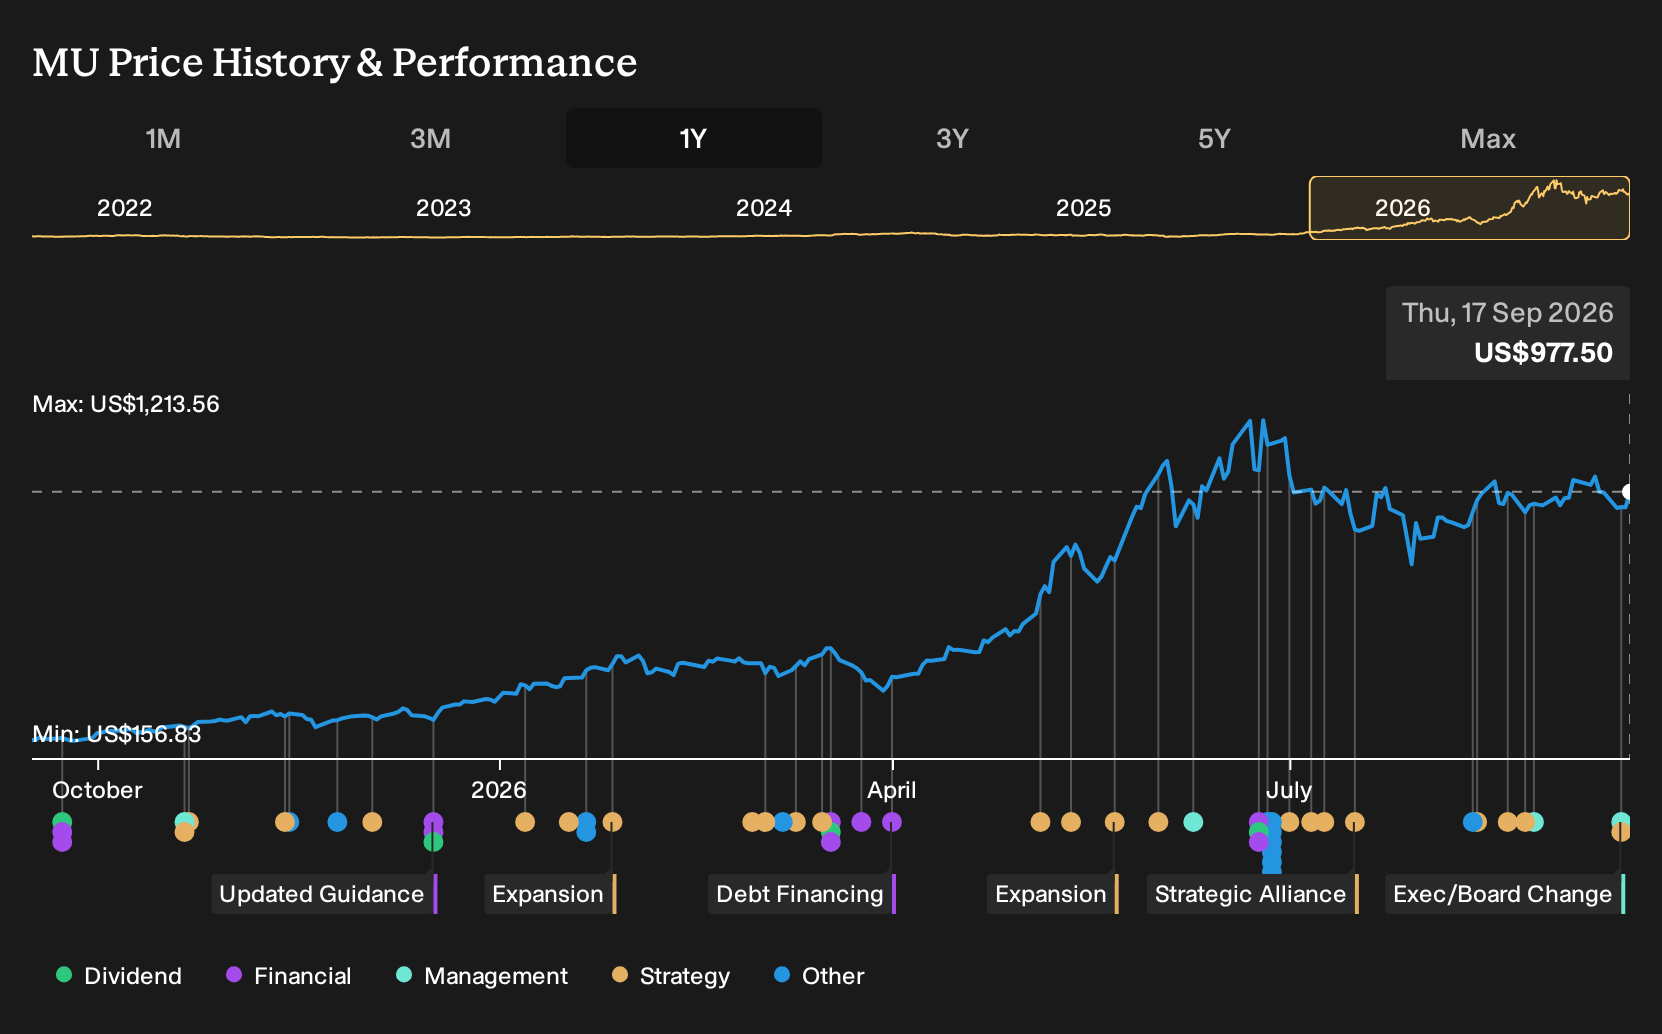
To own Micron Technology today, you need to believe that AI driven demand for advanced DRAM and high bandwidth memory can support a long run shift toward higher value, data center centric products. The 512GB DDR5 module and India capacity ramp fit that thesis operationally, but the near term share price still lives with sharp swings as sentiment around AI infrastructure spending shifts.
The key short term catalyst is the September 30 earnings report and any update on supply tightness, long term customer agreements and capital spending plans. The biggest near term risk sits in execution, including potential Taiwan labor disruption and the sheer capital intensity required to bring new fabs, packaging and HBM lines online without overextending cash flow.
The 512GB DDR5 RDIMM announcement is the clearest operational link to that near term catalyst. It shows Micron Technology pushing into ultra high capacity server memory that directly targets AI, analytics and in memory database workloads where customers are most sensitive to performance per watt and total system memory limits.
On its own, the product news does not change the investment case, since volume production is only expected in the second half of 2027. It does, however, sharpen the questions investors should ask on the upcoming call around R&D priorities, customer qualification progress with AMD and Intel, and how management sequences capital between HBM, DDR5 and new packaging capacity.
Micron Technology's narrative projects US$266.1b revenue and US$168.9b earnings by 2029. This is based on an assumed 43.4% yearly revenue growth and an earnings increase of about 3.3x from US$50.5b today.
Uncover why Micron Technology's fair value points to a 54% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic Micron Technology analysts focus on upside from long term AI data center demand. Before this news, the bullish cohort was penciling in earnings of about US$230.3b by 2029, compared with roughly US$168.9b in the baseline view. That is a very different story. Use this new 512GB DDR5 milestone and Deirdre Hanford’s appointment as fresh context to test which narrative you find more convincing.
Explore 23 other Micron Technology fair value estimates, including one that suggests as much as 123% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Micron Technology research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Micron Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Micron Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Micron Technology?
Once you understand where Micron Technology fits in your portfolio, the next step is to scan for other opportunities with clear financial stories and different risk profiles. The Simply Wall St screener can help you quickly filter the market by quality, balance sheet strength and income potential so you are not just reacting to the latest AI headline.
- If you want resilience first and foremost, start with a 11 resilient stocks with low risk scores that prioritize sturdier business profiles and more controlled risk scores.
- For investors hunting for mispriced quality, use a 29 high quality undervalued stocks to surface companies where fundamentals and price look out of sync.
- Anyone focused on dependable income can review a 6 dividend fortresses that target yields above 5% while still paying attention to stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com