


Cancel Flexibility Might Change The Case For Investing In Frontier Group Holdings (ULCC)
- Frontier Airlines announced a new Cancel for Any Reason option, powered by Hopper Technology Solutions, allowing travelers to cancel trips up to 24 hours before departure and receive refunds based on the level of coverage selected.
- The product adds another paid flexibility feature to Frontier Group Holdings' ancillary toolkit. It ties customer refunds to clearly tiered choices that could influence both booking behavior and the mix of higher margin add ons.
- We will now look at how Frontier Group Holdings' investment narrative could shift as cancel for any reason flexibility reshapes ancillary economics.
Scan beyond Frontier Group Holdings and see how other carriers and travel plays are using extra fees and flexibility to reshape their economics with a curated set of 16 high quality undiscovered gems.
Frontier Group Holdings Investment Narrative Recap
To own Frontier Group Holdings, you need to believe the ultra low cost model can convert strong demand from cost conscious leisure travelers into sustainable cash generation despite ongoing losses today. The key near term swing factor is whether management can use pricing, capacity discipline and ancillary add ons to better absorb fixed costs tied to pilots, crews and aircraft.
The Cancel for Any Reason launch looks incremental rather than transformative for the near term story. It tweaks how ancillary revenue and customer mix could develop, but it does not change the bigger risk that oversupply in U.S. domestic markets and structural non fuel cost pressure keep margins weak and profitability elusive.
The most relevant announcement here is Frontier Airlines’ new Cancel for Any Reason product with Hopper Technology Solutions. It fits squarely into the existing push to use digital tools, the app and website to fine tune pricing, personalize offers and lean harder on fees instead of fares. This approach is central to the Frontier Group Holdings thesis.
For you as a shareholder, the question is execution. If products like Cancel for Any Reason and Disruption Assistance for Any Reason deepen customer adoption of higher margin extras without driving away price sensitive flyers, they could support the ancillary led catalyst analysts are watching. Poor uptake or added complexity, on the other hand, would leave capacity, costs and competition as the dominant drivers.
Frontier Group Holdings is tied to analyst projections that point to revenue of US$6.1b and earnings of US$292.1m by 2029. That path assumes yearly top line growth of 17.2% and an earnings swing of about US$658m from an earnings loss of US$366.0m today.
Uncover why Frontier Group Holdings' fair value indicates a 13% potential upside to its current price before the market closes that valuation gap.
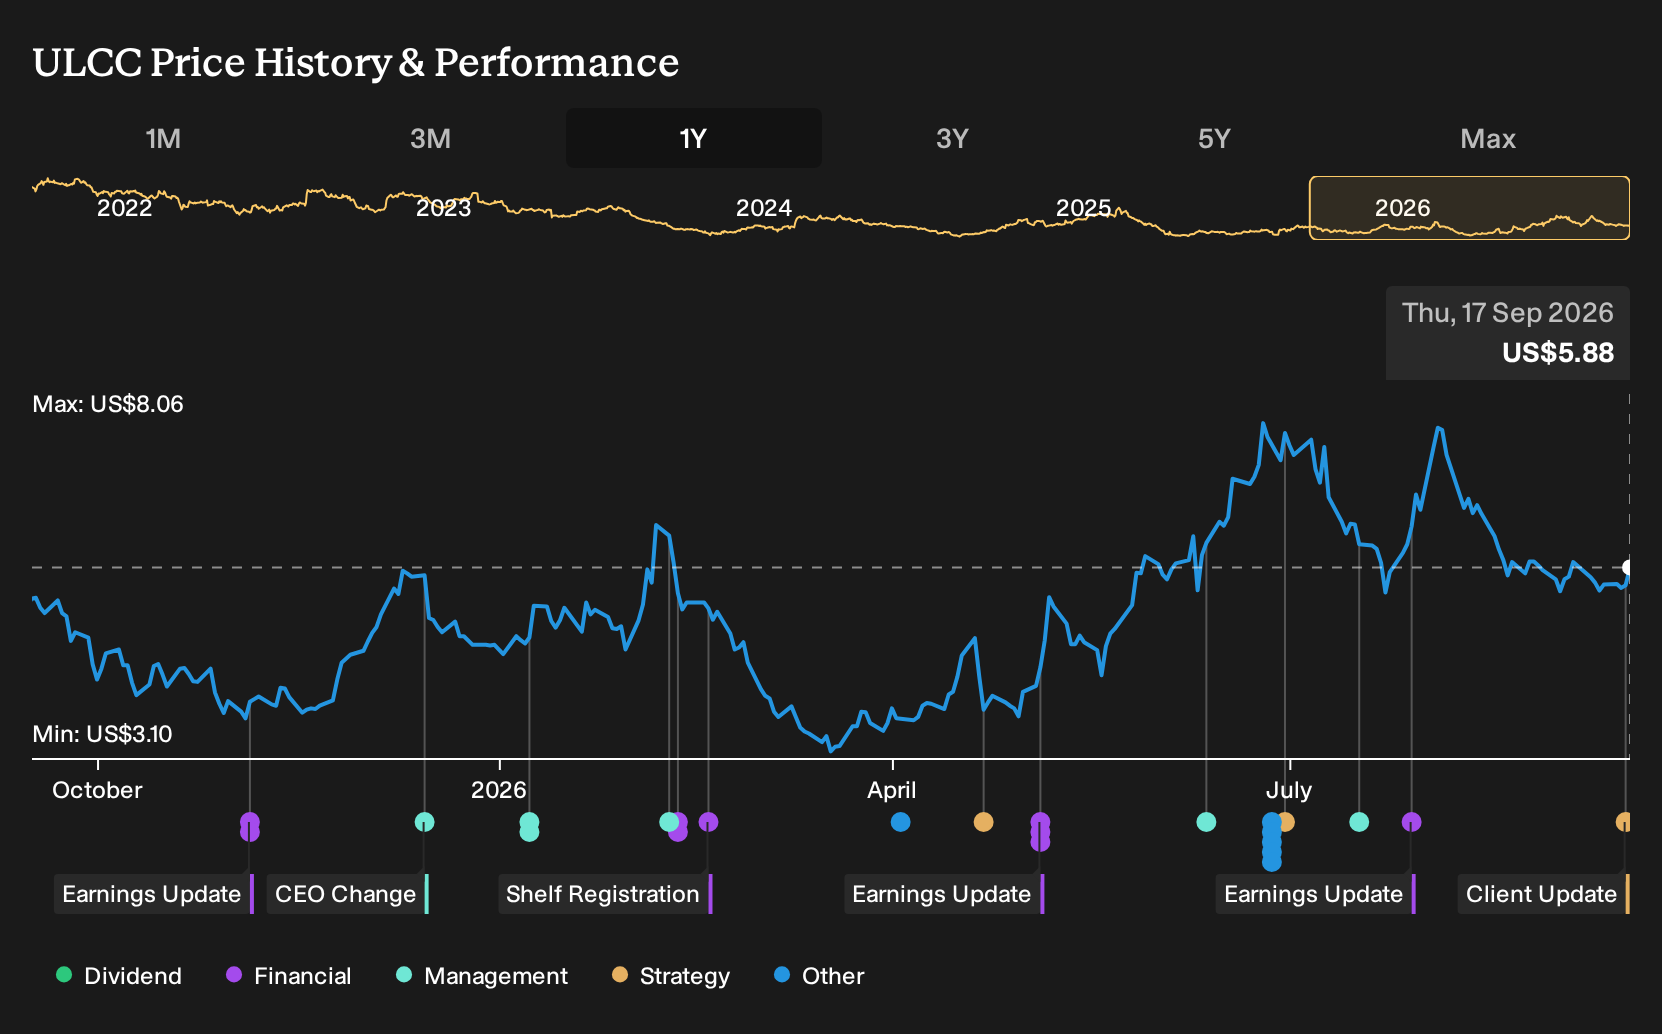
Exploring Other Perspectives
One bullish twist on Frontier Group Holdings focuses on digital and loyalty economics rather than capacity. The most optimistic analysts already penciled in revenue of about US$6.3b and earnings of roughly US$409.7m by 2029 before this Cancel for Any Reason news. You can treat those forecasts as one possible path that might evolve as this flexibility product beds in, then compare them with more cautious scenarios to decide which story you find more convincing.
Explore 4 other Frontier Group Holdings fair value estimates, including one that suggests up to 394% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Frontier Group Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Frontier Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Frontier Group Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Frontier Group Holdings?
Once you have a view on Frontier Group Holdings, it can help to compare it with other opportunities that share similar traits, whether that is value, balance sheet strength or income potential. The Simply Wall St Screener is a straightforward way to surface stocks that fit the type of profile you want to research next.
- If you want potential value opportunities with quality fundamentals, scan a curated set of 32 high quality undervalued stocks that might deserve a closer look.
- For investors who care most about stability and financial resilience, filter for companies in the list of solid balance sheet and fundamentals (22 results) and see which ones match your risk comfort.
- If income is your priority, start building a watchlist from a focused group of 6 dividend fortresses that offer higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com