


Jack Henry & Associates (JKHY) Could Be 5% Undervalued Following KeyBancs Overweight Call
Why Jack Henry & Associates Is Back On Investors’ Radar
A fresh Overweight rating from KeyBanc on Jack Henry & Associates (JKHY) has sharpened investor focus, coming right after a cluster of new client wins and fintech integrations across its digital banking platforms.
Recent price action tells a mixed story. The share price has climbed strongly in the last 90 days with a 23.75% share price return, yet is still down 12.41% on a year to date share price basis. The 1 year total shareholder return of 2.66% hints at modest long run progress as fresh fintech partnerships and the upcoming Analyst/Investor Day reset expectations around Jack Henry & Associates’ growth potential and risk profile.
Capitalize on the momentum around Jack Henry & Associates by lining up similar fintech and financial infrastructure opportunities from a hand picked list of 16 high quality undiscovered gems.After a 24% climb in 90 days and with a year-to-date decline still in place, does Jack Henry & Associates justify a buy now, or does it make more sense to wait for a cheaper entry before the numbers do the talking?
Most Popular Narrative: 4.6% Undervalued
Jack Henry & Associates closed at $156.21, while the most followed narrative pegs fair value nearer $163.69. The gap here is small but meaningful for anyone tracking both execution and pricing closely.
The August call''s dominant narrative posture was confidence compounding on confidence. Adelson opened with three "records": financial performance, sales wins, and trifecta attach, and structured the rest of the prepared remarks as evidence for a fourth record: the platform''s upmarket credibility. The Woodforest name, withheld in May for contractual reasons, served double duty in August: it proved the almost-$10-billion figure mentioned in May and anchored a broader argument that the company can now demonstrate its technology rather than describe it. "There are not PowerPoints being shown. It is all live demonstrations and actual ability to utilize the solution set." That line, volunteered without a direct prompt, is a positioning move. It separates Jack Henry from both legacy competitors and modern-platform pretenders simultaneously.
See why 2 investors see Jack Henry & Associates as 5% undervalued.
Result: Fair Value of $163.69 (UNDERVALUED)
Still, Jack Henry & Associates’ margin reset and the open questions around Banno’s outside base push could both undermine the current 4.6% undervaluation story.
Find out about the key risks to this Jack Henry & Associates narrative.
Another View On Jack Henry & Associates’ Valuation
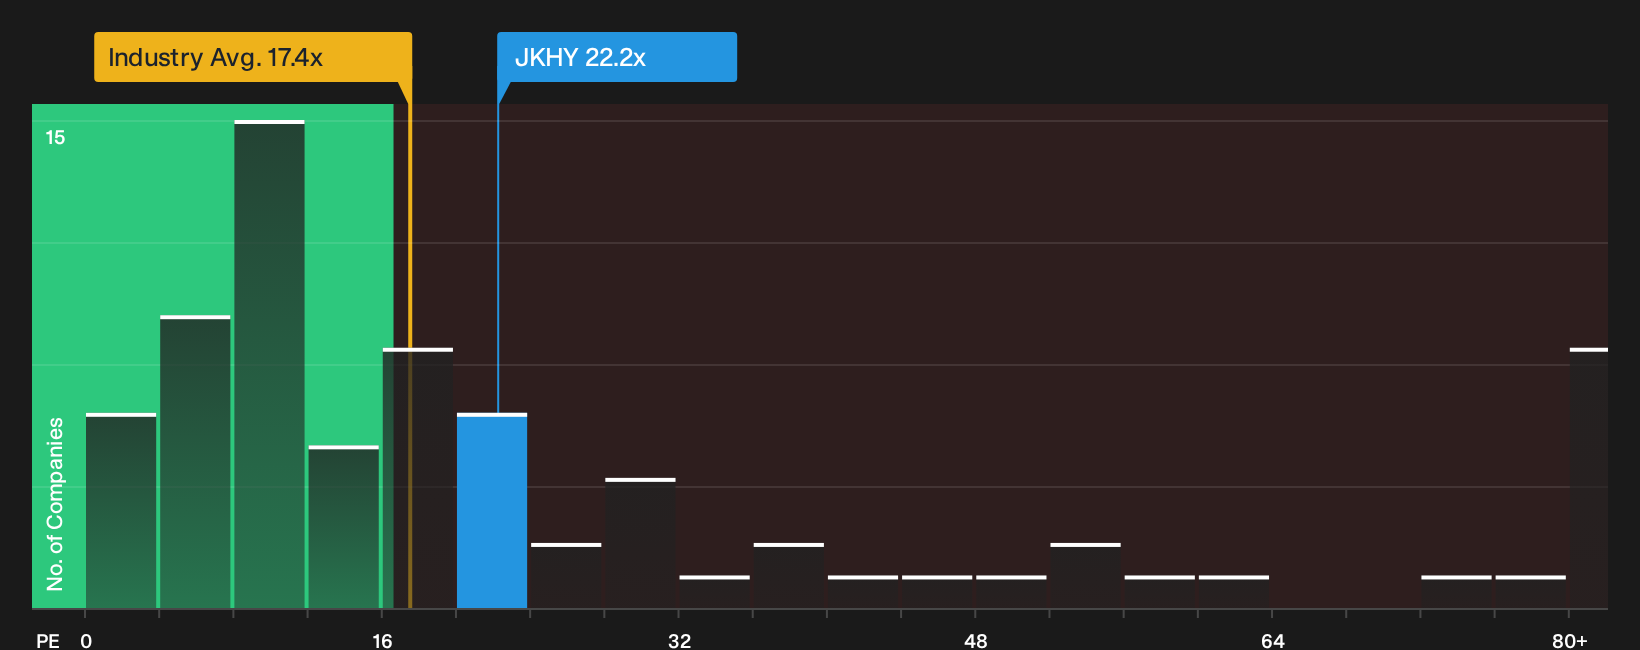
The 4.6% discount to a $163.69 fair value suggests Jack Henry & Associates is slightly undervalued. The P/E picture tells a very different story. The stock trades at 22.2x earnings, compared with 17.4x for the US Diversified Financial industry, a 16x peer average, and a fair ratio of 13.2x that the market could move toward over time.
If sentiment ever swung closer to that 13.2x fair ratio, the share price would need to adjust down. The key question is how much valuation risk you are comfortable owning here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Jack Henry & Associates has turned constructive, but the real edge comes from testing that optimism against the raw numbers yourself. If you want a clearer view of what has investors interested right now, start by zeroing in on the 4 key rewards.
Looking For More Ideas Beyond Jack Henry & Associates?
If you stop with Jack Henry & Associates, you risk missing other opportunities that fit your goals just as well, or sometimes even better.
- Target potential upside by focusing on quality businesses trading below their estimated worth through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies with reliable payouts and higher yields using the 6 dividend fortresses.
- Sleep easier at night by concentrating on resilient businesses that carry lower assessed risk scores with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com