


Shionogi (TSE:4507) Wins New Drug Approvals On Questions Over Whether The Value Case Still Holds
Shionogi (TSE:4507) moved back into focus after fresh product news, as the Japanese pharmaceutical group reported new regulatory approvals for its COVID-19 vaccine COVGOZE and pediatric atopic dermatitis treatment VTAMA Cream.
Against this backdrop, Shionogi’s recent approvals arrive with momentum already building in the stock, with a 90 day share price return of 7.28% and a 1 year total shareholder return of 15.24%. This signals that the latest vaccine and dermatology updates are landing in a market that has been gradually warming to the story.
Compare Shionogi’s fresh product approvals with other pharma players showing similar momentum and potential, starting with the hand picked 74 high quality undiscovered gems.
Shionogi now has fresh products, a long operating history, and a share price that has already moved. The real tension is whether the current valuation still reflects a fair deal.
Preferred P/E of 9.6x: Is it justified?
Shionogi looks cheap on headline metrics, with the stock at ¥2,982.5 and the current P/E of 9.6x sitting well below both peers and the wider JP pharmaceuticals group. For anyone watching the recent product wins, the question is whether that discount reflects caution around future earnings or an opportunity that has not yet been fully repriced.
The P/E ratio compares what investors pay today for each unit of current earnings. For a pharmaceutical business like Shionogi, it becomes a shorthand for how the market is weighing existing cash flows against future drug pipelines, patent cycles, and potential profit swings from one off items.
Here, the current 9.6x multiple is described as good value relative to the JP Pharmaceuticals industry average of 14.3x and an 18.5x peer average. It is also below an estimated fair P/E of 21.8x. That fair P/E suggests the level the market could move toward if sentiment shifted closer to that fair ratio benchmark and earnings held up in line with expectations.
Explore the SWS fair ratio for Shionogi.
Result: Price-to-earnings of 9.6x (UNDERVALUED)
Still, the story around Shionogi can break if its recent revenue growth of 4.34% slows or if its declining net income of 3.48% signals deeper profitability pressure.
Find out about the key risks to this Shionogi narrative.
Another view on Shionogi using DCF
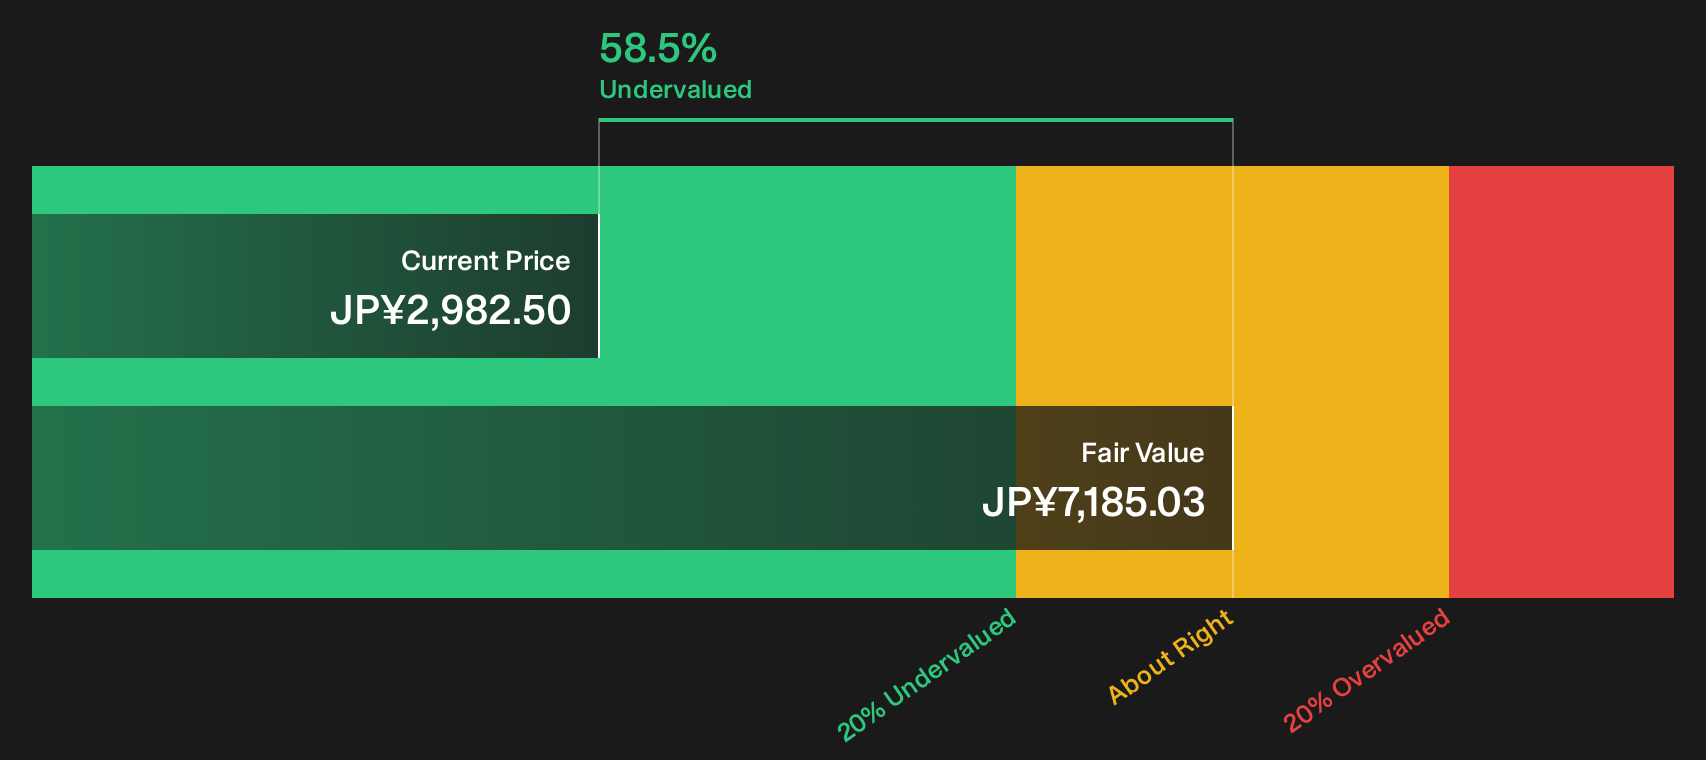
There is a very different signal when you look at Shionogi through the SWS DCF model. At ¥2,982.5, the shares are described as trading about 58.5% below an estimated future cash flow value of ¥7,185.03. This suggests a much deeper potential valuation gap than the 9.6x P/E implies.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shionogi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Shionogi so far, which is exactly why you should look through the numbers yourself, weigh the trade offs, and pressure test both the upside and the weak spots by checking the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Shionogi?
If you stop with Shionogi, you miss plenty of other setups where quality, price, and risk all line up in ways worth your attention.
- Target stronger upside potential by scanning a 17 high quality undervalued stocks that blends solid fundamentals with prices that have not yet fully reflected underlying business quality.
- Build more dependable income by focusing on a 14 dividend fortresses that screens for higher yields alongside balance sheets that look better equipped to support ongoing payouts.
- Cushion your portfolio against shocks by filtering a 12 resilient stocks with low risk scores that highlights companies with sturdier financial profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com