


Is Delek US Holdings (DK) Still Worth A Look As Insider Selling Tests Valuation?
Board member William J Finnerty recently sold 2,943 shares of Delek US Holdings (DK), a transaction valued at about US$227,113, according to an SEC filing dated September 16, 2026.
The latest insider sale comes as Delek US Holdings trades at US$79.16, with a 90 day share price return of 90.89% and a year to date share price return of 165.82%. The 5 year total shareholder return of 466.32% points to strong longer term momentum.
Scan how Delek US Holdings compares with other refiners that have been hand-picked for strong price action and fundamentals using the list of solid balance sheet and fundamentals (22 results).
Delek US Holdings has surged, yet annual revenue and net income have both moved lower. Is this latest jump mainly a vote of confidence in the business, or a rush of optimism in the share price?
Most Popular Narrative: 5% Undervalued
Against the last close at $79.16, the most followed valuation narrative for Delek US Holdings lands on a fair value of $83.00, which points to a modest gap that the market is currently debating.
North America's persistent refinery underinvestment and accelerated rationalization, together with robust long-term demand for refined products in the U.S. and developing markets, are set to drive structurally higher crack spreads and utilization rates. This is expected to amplify Delek's earnings leverage as one of the most efficiently run and U.S.-centric refiners.
See why 0 investors see Delek US Holdings as 5% undervalued.
Result: Fair Value of $83.00 (UNDERVALUED)
Still, Delek US Holdings faces real swing factors, including tighter environmental rules and faster uptake of renewables that could pressure long term refining economics.
Find out about the key risks to this Delek US Holdings narrative.
Another View on Delek US Holdings Valuation
While the most popular narrative frames Delek US Holdings as modestly undervalued at a fair value of $83.00, the SWS DCF model points in the opposite direction. On that cash flow lens, DK at $79.16 screens as overvalued, which suggests a very different risk profile for anyone buying at today’s level.
That gap between a bullish narrative and a cautious cash flow model raises a simple question for investors. Which set of assumptions feels closer to how Delek US Holdings will actually perform over time?
Look into how the SWS DCF model arrives at its fair value.
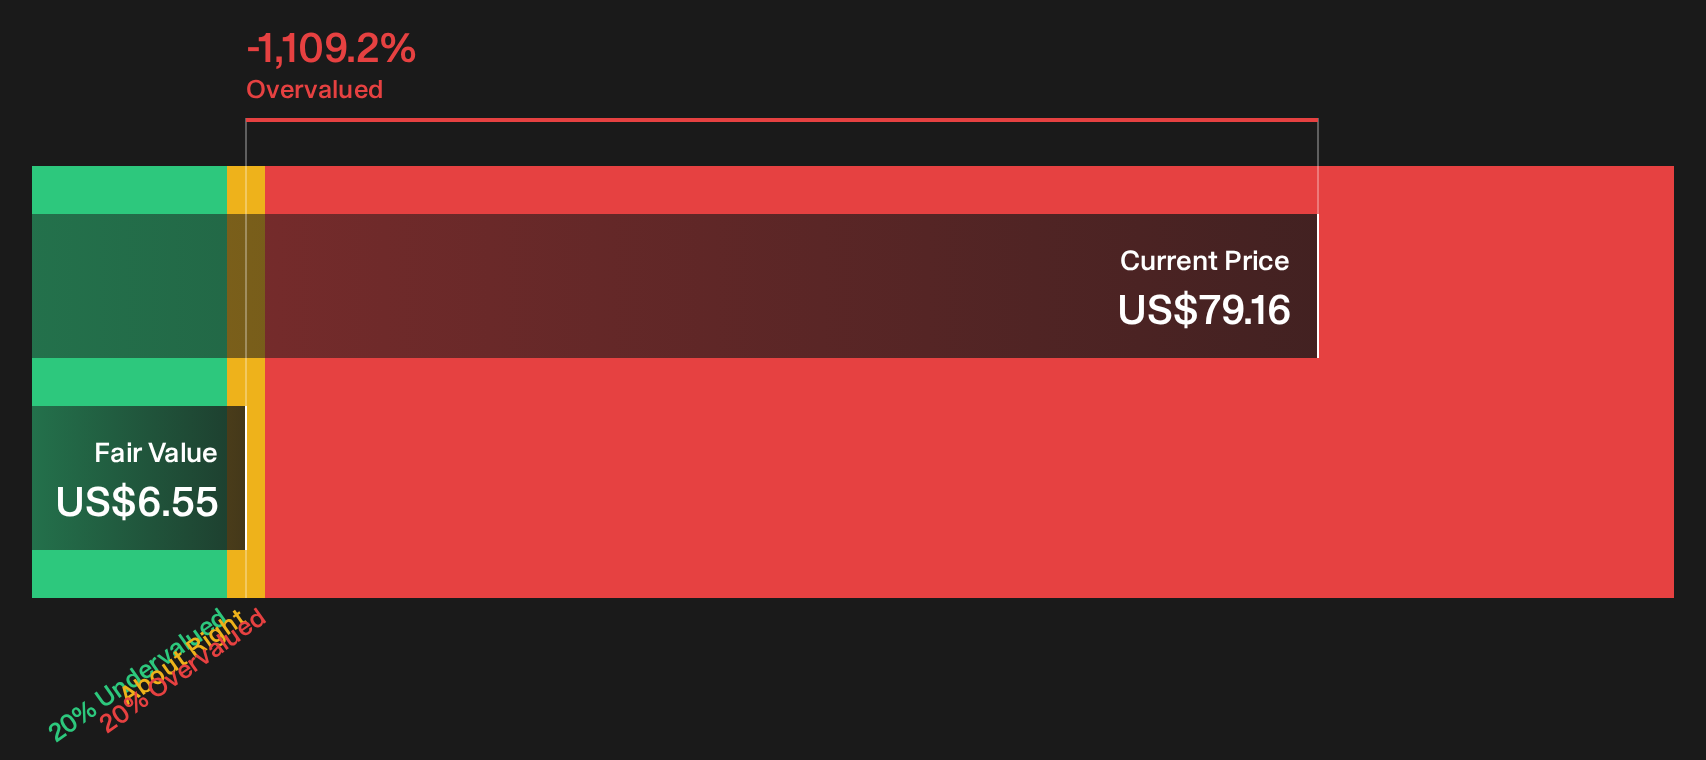
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delek US Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Delek US Holdings can either paralyse you or push you to check the underlying numbers fast and decide where you stand. To see both the upside case and the pressure points investors are focused on right now, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Delek US Holdings?
If Delek US Holdings has you thinking more broadly about where to put fresh capital to work, use these focused screeners to surface alternatives quickly.
- Target potential mispricing by scanning a curated pool of companies that combine quality fundamentals with attractive valuations using the 33 high quality undervalued stocks.
- Find income ideas by reviewing a focused universe of companies designed to provide robust yields and resilient payouts through the 6 dividend fortresses.
- Manage downside risk by filtering for businesses with strong balance sheets and solid financial footing through the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com