


Peloton (PTON) Stock Could Be Fully Priced After Subscriber Growth Warning
Peloton Interactive has seen its share price under pressure in recent years, and the question now is whether the current valuation can still be squared with what the business earns. For anyone watching Peloton stock, the key issue is whether today's earnings profile can support where the market is pricing the company.
- Over the past 5 years the share price has fallen 94.9%, which puts the spotlight firmly on whether the earnings outlook can justify even the current lower level.
- Recent commentary on slower connected fitness subscriber growth suggests Peloton's revenue and profit potential could be more constrained than once hoped, which can affect how much investors are willing to pay for its earnings stream.
- Your read on Peloton Interactive is one view; the desks covering it have another. See what analysts think Peloton Interactive's shares could be worth.
The issue now is whether Peloton's current share price is reasonable when judged purely against the earnings the business is generating.
If Peloton's recent share price slide has you rethinking the theme, it can help to compare its earnings story with companies in 33 high quality undervalued stocks
Is Peloton Interactive Getting Expensive on Earnings?
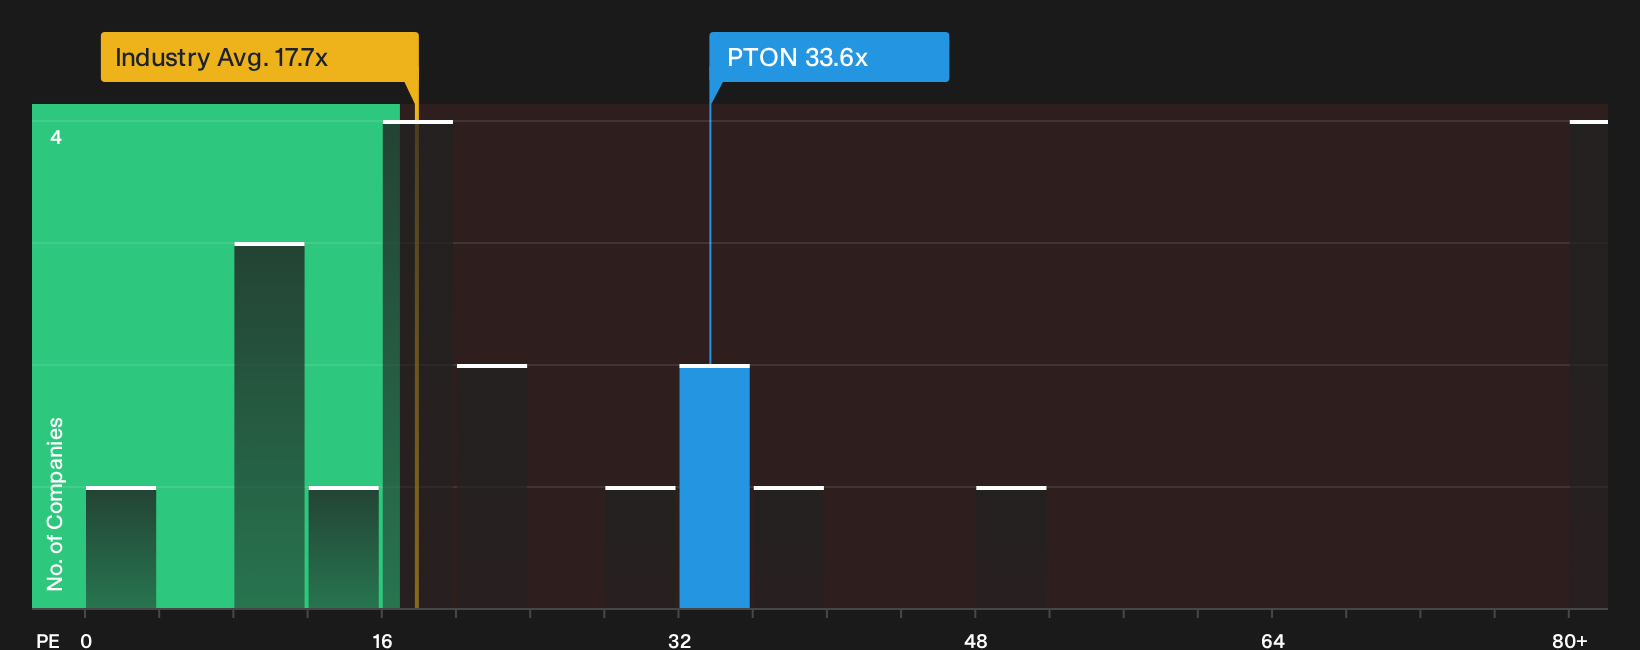
The P/E ratio is a useful measure for Peloton Interactive because the focus today is on earnings power. On this basis, the stock trades on a P/E of 33.6x, which is materially higher than the Leisure industry average of 17.7x and above the peer group on about 20.0x. A tailored fair multiple that blends Peloton's growth profile, margins, size and risk points to a lower P/E than the current figure, so the shares appear overvalued on this framework.
Morgan Stanley has highlighted structural headwinds to connected fitness subscriber growth, so this richer earnings multiple requires paying a premium despite questions around how comfortably profits can support it. For anyone evaluating Peloton Interactive at today's level, the key consideration is whether the current earnings stream and its risks justify paying well above both sector and peer benchmarks on P/E. Explore the numbers behind Peloton Interactive's P/E valuation.
The Peloton Interactive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Peloton Interactive pick up where that P/E puzzle leaves you by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look materially cheaper or more expensive than it does today on the screen. Each scenario focuses on the assumptions that sit behind its view of value so you can watch how those hold up as new results and updates hit the Community page.
Peloton Interactive splits opinion, with one camp seeing a reset platform and another worried the core model is running out of steam.
Bull case: 68% undervalued
"Peloton's continued cost discipline, aggressive restructuring, and platform shift to higher-margin digital subscriptions is happening at the same time as global adoption of digital wellness surges..."
Discover why this Narrative puts Peloton Interactive at 68% undervalued.
Bear case: 21% overvalued
"Slowing hardware sales and subscriber declines reflect that Peloton is nearing saturation in its primary North American and European markets, meaning future revenue growth will be limited..."
Explore why this Narrative puts Peloton Interactive at 21% overvalued.
One more Peloton Interactive check that sits beside the P/E debate
Price can only tell you so much if you have not looked at who is steering Peloton Interactive and how their pay packets line up with your priorities. See who runs Peloton Interactive and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com