


Unilever (LSE:ULVR) Faces A Valuation Split, Is It Fully Priced Or A Bargain?
Unilever (LSE:ULVR) has come back into focus after fresh performance data showed revenue of €50,620m and net income of €5,598m. Investors are weighing these figures against the recent share price moves.
At a share price of £46.33, Unilever has seen short term share price momentum improve, with a 6.16% 90 day return. The year-to-date share price is still down 3.94%, and the 5 year total shareholder return of 29.43% points to steadier long haul progress.
Scan how Unilever’s recent performance compares with other established consumer businesses by reviewing a hand picked set of list of solid balance sheet and fundamentals (11 results) in the market today.
After a 6.16% rise over 90 days yet a share price that is still down for the year, is most of Unilever’s rerating already behind it, or could valuation work in investors’ favour from here?
Most Popular Narrative: 10% Overvalued
Against the latest close at £46.33, the most followed narrative on Unilever points to a fair value of £42.28, suggesting investors today are paying a premium to that estimate. That gap between price and narrative fair value is what makes the underlying thesis worth unpacking.
Unilever is a high-quality business, with return on equity remaining around the 30% mark. Management’s continued use of share buybacks also suggests a degree of confidence in the company’s future direction, although buybacks are only beneficial to shareholders when undertaken at sensible valuations. Importantly for the investment case, Unilever’s valuation does not appear extreme by current market standards. Both the Acquirer’s Multiple and Joel Greenblatt’s Magic Formula produce relatively favourable results. The price-to-earnings ratio, currently around 20 times earnings, is not unreasonable for the quality and stability of the business being purchased. Overall, I think Unilever is probably fairly valued in the current market. It is difficult to make a compelling case that the shares are dramatically undervalued, but equally, the valuation does not appear excessive given the quality of the underlying business, its strong brands, cash generation and potential for improving margins. For me, this makes Unilever a company to watch rather than an obvious buy at any price. If there were a broad market correction that brought the valuation down while the underlying transformation continued to progress, Unilever could become considerably more attractive.
See why 2 investors see Unilever as 10% overvalued.
Result: Fair Value of £42.28 (OVERVALUED)
Still, the planned food demerger and heavy reliance on emerging markets leave Unilever exposed if execution misfires or currency swings affect reported progress.
Find out about the key risks to this Unilever narrative.
Another View On What Unilever Is Worth
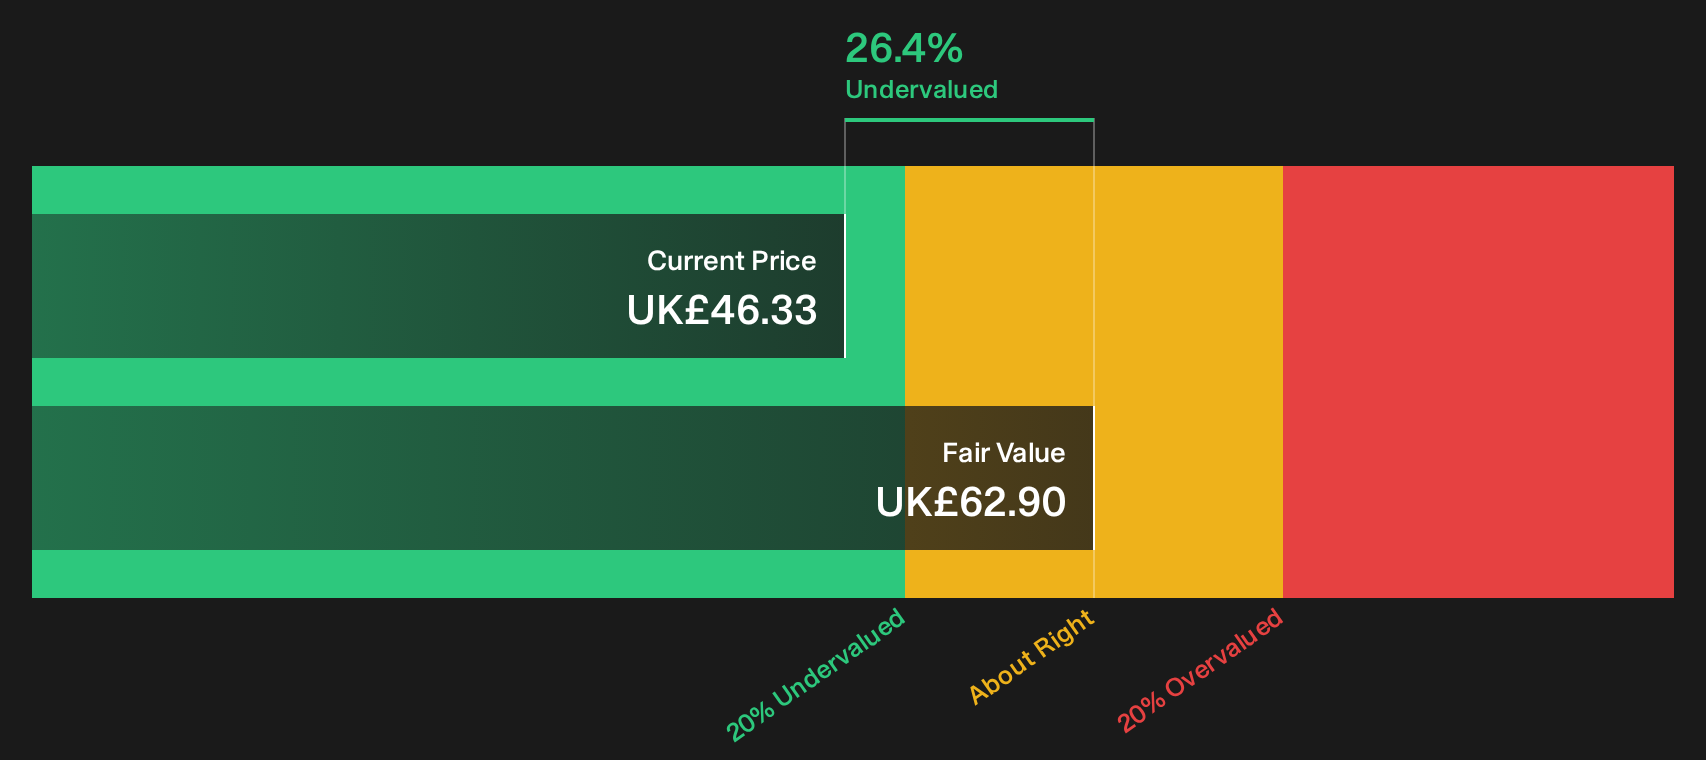
That user narrative leans on a P/E of around 20x to argue Unilever looks fairly priced. Our DCF model tells a different story. On those cash flow assumptions, a fair value of £62.90 versus today’s £46.33 points to the shares trading well below that estimate.
This gap raises a simple question for investors. Is the cash flow outlook too optimistic, or are shorter term concerns around debt, management turnover and underperformance versus the wider UK market pulling the share price below what the SWS DCF model suggests it could be worth?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unilever for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Unilever is clearly split, with both concerns and reasons for optimism in play. Move quickly, inspect the data, and weigh the 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Unilever?
If Unilever has sharpened your focus on quality, do not stop here. Broader research now could surface opportunities you will not see by staying put.
- Target resilient compounding potential by scanning a 8 high quality undervalued stocks that blend strong fundamentals with prices below their assessed worth.
- Lock in reliable income streams by reviewing a curated set of 1 dividend fortresses that combine yield with business durability.
- Protect your downside first by filtering for a 2 resilient stocks with low risk scores that emphasise financial strength and lower risk profiles before chasing upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com