


CTF Services (SEHK:659) Could Be 28% Undervalued After A Pause In Its Share Price
CTF Services (SEHK:659) has drawn investor attention after its shares closed at HK$7.76, leaving the diversified Hong Kong group with a market value of about HK$35.4b and a broad mix of infrastructure and services exposure.
Recent trading points to cooling momentum in the CTF Services share price, which is down 2.1% over the past week and 3% over the past quarter, even though the year-to-date share price return is positive and the 1-year total shareholder return of 18.2% sits on top of strong multi year gains.
Spot opportunities beyond CTF Services by scanning a hand-picked 182 high quality undervalued stocks that may appeal if you are watching for cooling momentum and potential valuation gaps in established businesses.
After a long run and a recent pause in the CTF Services share price, the real puzzle now is simple. Is most of the upside already behind the stock, or is there still meaningful value on the table?
Most Popular Narrative: 28% Undervalued
On the most followed view, CTF Services screens below an implied fair value of HK$10.80, while the shares last traded at HK$7.76. That gap only really matters if the business can turn its current mix of toll roads, insurance and logistics into steadier and more profitable cash flows over time.
The strategic focus on value-accretive acquisitions, especially in growing segments like CTF Life (insurance) and expansions in logistics, is expected to drive long-term revenue and earnings growth. These acquisitions and expansions can potentially increase revenue and enhance net margins through scale and diversified income streams.
See why 1 investors see CTF Services as 28% undervalued.
Result: Fair Value of HK$10.80 (UNDERVALUED)
Still, CTF Services leans heavily on Mainland Chinese visitor demand and carries meaningful gearing, so weaker tourism or higher funding costs could quickly challenge that 28% discount story.
Find out about the key risks to this CTF Services narrative.
Another View On CTF Services Using Market Ratios
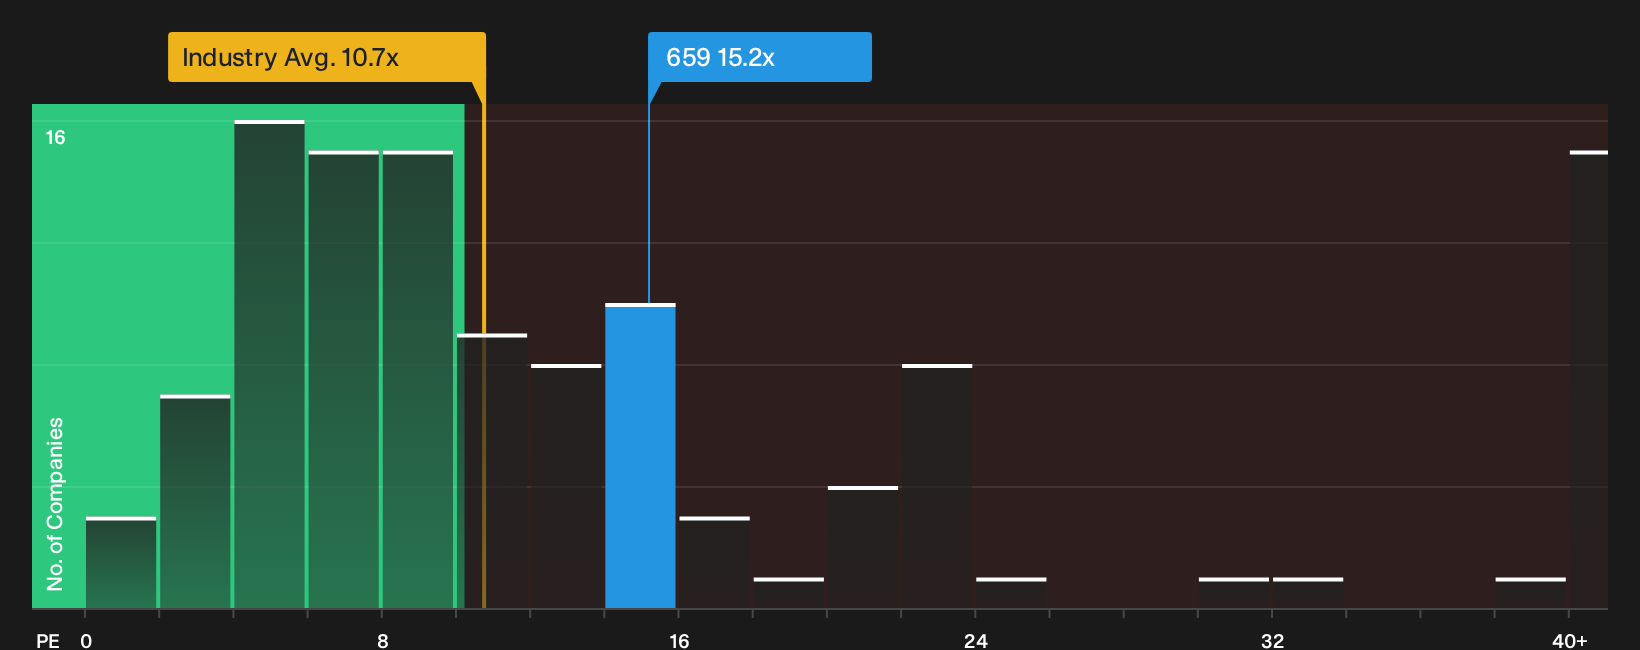
That 28% discount to a HK$10.80 fair value leans on future cash flow assumptions. Market pricing tells a different story. CTF Services trades on a P/E of 15.2x, while Asian industrials average 10.7x and its own fair ratio is 8.8x, which points to valuation risk rather than a clear bargain.
Put simply, the shares look expensive versus peers and that fair ratio, so the question is whether the business can deliver enough earnings quality and growth to justify paying up.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on CTF Services leave you unsure, move quickly. Look through both sides of the story, then weigh up the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond CTF Services?
If CTF Services has sharpened your focus on pricing and quality, do not stop there. Use fresh ideas from focused screeners to keep your watchlist evolving.
- Target potential mispricings by reviewing companies that pass a strict quality filter and appear out of favour through the 182 high quality undervalued stocks.
- Strengthen your income stream by hunting for payout-focused opportunities using the 160 dividend fortresses.
- Sleep easier at night by concentrating on financially robust businesses through the list of solid balance sheet and fundamentals (194 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com