


NextNav (NN) 5G Positioning Breakthrough Leaves Room For An Undervalued View
NextNav (NN) just reported real world field results for its 5G powered positioning technology, showing single digit meter accuracy indoors and outdoors, and plans to walk through the data at ION GNSS+ 2026.
Despite the technical progress, NextNav’s 1 month share price return is down 23.85%, with the stock also declining 19.58% over 3 months and 9.86% year to date. However, the 3 year total shareholder return of 179.54% shows how strong the longer run has been.
Scan beyond NextNav and explore other location and connectivity plays that could be setting up for their own breakout using our curated list of 60 AI infrastructure stocks.
Bulls see a 179.54% three year return and fresh 5G field data as proof that NextNav is building real value, while bears point to a US$111.855m loss on just US$3.977m of revenue. Which story does the valuation tell?
Most Popular Narrative: 57% Undervalued
Against NextNav’s last close of $14.62, the most followed narrative pegs fair value at about $33.67. The story assumes a lot of upside is still on the table if its core 3D positioning ideas translate into contracts and cash flows.
Progress at the FCC toward an NPRM on 5G based 3D PNT in the lower 900 megahertz band, combined with a congressional push to free more spectrum, sets the stage for commercial rights that can unlock new service revenues and crystallize spectrum value on the balance sheet, supporting higher earnings and asset valuations.
See why 4 investors see NextNav as 57% undervalued.
Result: Fair Value of $33.67 (UNDERVALUED)
Still, the bullish NextNav story can crack if FCC timelines slip again or if carriers spread 3D PNT spend across multiple vendors and dilute its share.
Find out about the key risks to this NextNav narrative.
Another View: What Multiples Say About NextNav
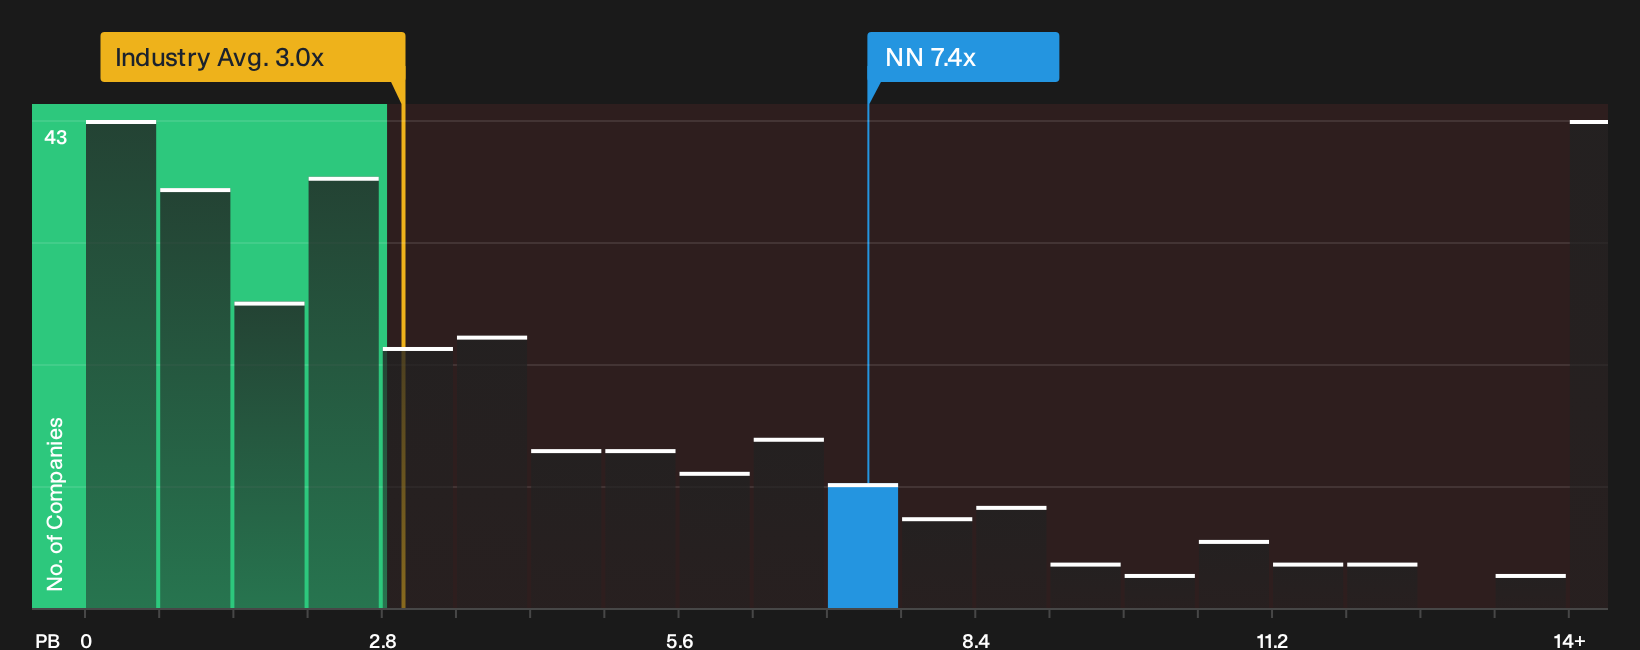
The first story on NextNav focuses on future earnings and a high implied P/E to argue the shares look cheap. A different lens suggests something less comfortable. On a P/B of 7.4x, the stock trades at more than double both the US Software industry average of 3x and the peer average of 2.8x. This points to a rich price tag if expectations fade.
If the market moved toward a lower fair ratio over time, today’s premium could translate into downside risk rather than upside optionality. That gap raises a simple question for investors: Is the current enthusiasm strong enough to keep supporting this kind of valuation multiple when the business is still loss making and revenue is only $4m?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on NextNav so far, with big past gains sitting next to fresh losses and rich multiples, mean you should review the numbers directly, weigh the downside carefully, and start by checking the 3 important warning signs.
Looking for more ideas beyond NextNav?
If NextNav has your attention, do not stop there. Broaden your watchlist with focused sets of companies that fit clear financial traits and risk profiles.
- Target potential value opportunities by running through a curated pool of companies on the 33 high quality undervalued stocks.
- Prioritize resilience and sleep-at-night holdings by scanning the 11 resilient stocks with low risk scores.
- Zero in on robust finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com