


How AI Partnerships At Lenovo (SEHK:992) Have Changed Its Investment Story
- Recent announcements show Lenovo pushing deeper into AI heavy infrastructure and computing, including new ThinkAgile VX850 V4 systems, expanded Express Solutions for virtualization and hybrid cloud, and multi phase collaborations in autonomous driving with HL Klemove and sovereign edge AI in Saudi Arabia with MemryX.
- These moves point to Lenovo leaning into higher complexity, service rich workloads, where long deployment cycles, customer stickiness, and sizable R&D demands can materially shape margin mix and execution risk.
- The focus now turns to how Lenovo's push into AI infrastructure and autonomous driving hardware could reshape the broader investment narrative.
Scan beyond Lenovo Group and evaluate other AI heavy infrastructure plays using our hand picked list of 60 AI infrastructure stocks as potential benchmarks for this kind of capital intensive build out.
Lenovo Group Investment Narrative Recap
To own Lenovo Group, you need to believe its pivot toward AI infrastructure, services, and higher value devices can offset pressure in traditional PCs and the current drag from loss making investment in the Infrastructure Solutions Group. The near term catalyst is execution on this AI heavy pipeline turning into visible, recurring, higher margin workloads rather than just headline product launches.
The biggest risk remains that heavy AI and data center spending keeps compressing group margins if projects like autonomous driving compute and sovereign edge AI scale slowly or prove lumpy. The recent announcements increase execution complexity but do not yet alter that core risk reward balance in a material way.
The HL Klemove partnership is the clearest operational test case here. Lenovo is moving its AI compute into Level 4 capable autonomous driving and advanced driver assistance, with a three phase plan from co development to orders to mass production. That puts long, capital hungry ramps against the need for cleaner profitability from ISG after a period of segment level losses.
For you as an investor, the key question is how quickly this automotive AI compute effort shifts from engineering cost to repeat hardware and services volume. The potential upside would be meaningful design wins with global OEMs that validate Lenovo as a credible automotive computing supplier. The risk is extended timelines, uneven order flow, and further strain on margins while the broader PC and device business still faces commoditization pressure.
Lenovo Group Consensus Assumptions In Context
Analysts currently model Lenovo Group as a much larger, more profitable AI infrastructure and device platform over the next several years, with the numbers putting real weight behind that story. Consensus forecasts call for revenue to expand by 14.4% per year over the coming three years, and for profit margins to move from 0.9% today to 4.4% on a similar horizon. On earnings, the group is expected to move from US$798.0 million today to US$6.0b by about 2029, although the range is wide, from US$4.8b at the low end to US$9.8b at the high end. To get there, the P/E multiple implied by analyst targets would need to compress from 65.4x today to 15.2x in 2029, which is slightly below the current 16.0x P/E cited for the Hong Kong tech peer group.
That shift matters for how you frame Lenovo as an AI infrastructure play. The forecasts effectively assume that the Infrastructure Solutions Group and newer AI centric bets become material earnings engines, not persistent loss centers. They also assume the devices portfolio and services stack can sustain enough top line growth to support a more than sevenfold increase in earnings in a few years while the valuation multiple normalizes. When you evaluate Lenovo against other AI heavy hardware and data center vendors, these expectations give you a rough yardstick for what the market is already baking into the share price.
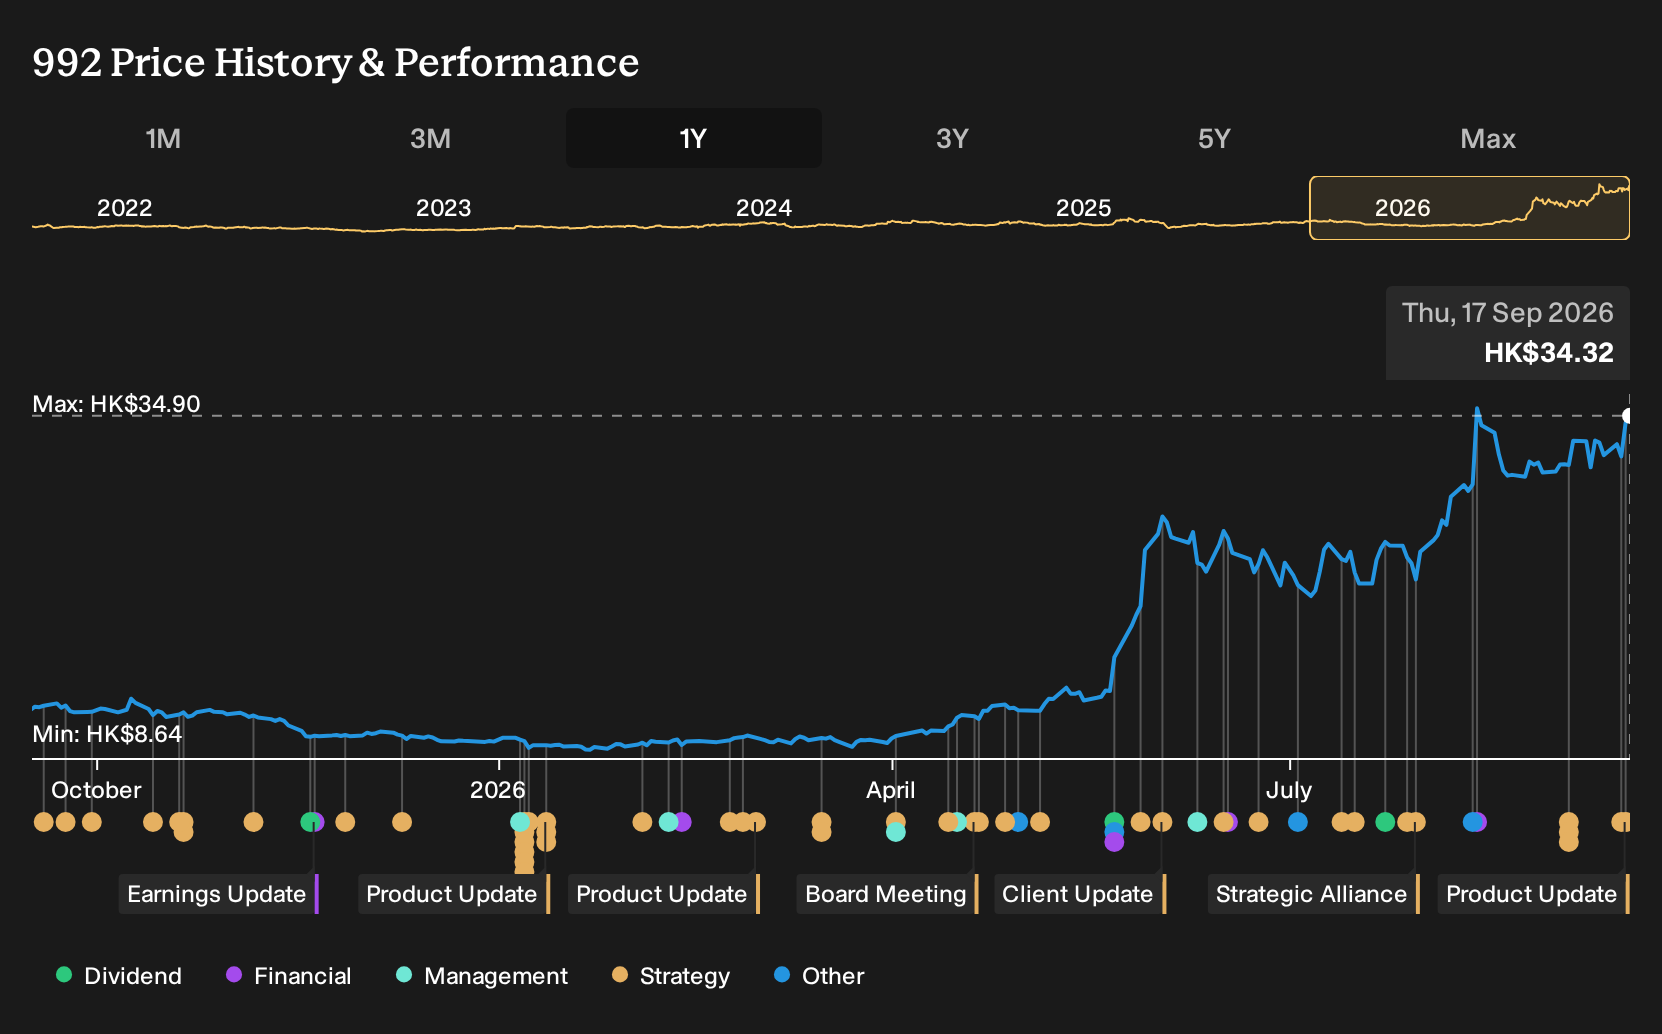
On the valuation side, consensus targets cluster around a fair value that leans on those 2029 estimates. The central analyst view ties a HK$44.38 share price to 2029 revenue of US$136.6b and earnings of US$6.0b, along with that lower 15.2x P/E and a discount rate assumption close to 9%. There is a wide spread in views, with the most optimistic target at HK$66.0 and the lowest at HK$11.03, which signals genuine uncertainty around how cleanly Lenovo can convert its AI and data center pipeline into durable profitability.
Lenovo Group's narrative projects US$136.6b revenue and US$6.0b earnings by 2029. This rests on 14.4% yearly revenue growth and an earnings increase of roughly US$5.2b from US$798.0 million today.
Uncover why Lenovo Group's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on Lenovo Group’s AI upside and more on geopolitical risk. Those bearish analysts were penciling in US$117.3b of revenue and US$4.8b of earnings by 2029, tied to an 8.8% growth path, before this HL Klemove deal. You can treat that more pessimistic setup as a reference point and explore how new alliances might shift it.
Explore 4 other Lenovo Group fair value estimates, including one that suggests as much as 20% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and research.
- A great starting point for your Lenovo Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lenovo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lenovo Group's overall financial health at a glance.
Looking for more investment ideas beyond Lenovo Group?
If Lenovo Group’s AI and infrastructure story has sharpened your thinking, it can help to line it up against other stocks with very different risk and reward profiles. The Simply Wall St Screener lets you jump straight into focused shortlists rather than sifting through the entire market on your own.
- If you want potential upside with strict quality filters, start with a curated group of 619 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- If capital preservation matters just as much as return potential, narrow your search to a 104 resilient stocks with low risk scores that aims to balance resilience with reasonable growth prospects.
- If you care most about balance sheet strength and staying power through cycles, anchor your watchlist around a list of solid balance sheet and fundamentals (194 results) that screens for healthier leverage and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com