


BorgWarner (BWA) Is Back On The Radar, What Is Catching Investors’ Attention?
Why BorgWarner Stock Is Back On Investors’ Radar
BorgWarner (BWA) is drawing attention after being highlighted with a Zacks Rank #2 rating and a Value grade of A, helped by a year-to-date gain of about 38.7%.
Recent action has been choppy, with BorgWarner’s share price down 10.9% over the past 30 days and 13.3% over 90 days, even after a 33.5% year to date share price return and a 42.6% 1 year total shareholder return.
Compare BorgWarner’s value story with a curated list of other potential bargains by scanning the 33 high quality undervalued stocks that currently screen well on both quality and price.
The surge in BorgWarner followed by a sharp pullback leaves a simple tension: Is this where most of the easy money has already been made, or where the valuation still points to more room ahead?
Most Popular Narrative: 22% Undervalued
Against a last close of $62.27 for BorgWarner, the most followed narrative pegs fair value at about $79.67. This implies a sizeable valuation gap that investors are trying to explain through the company’s shift toward electrified powertrain and non auto power opportunities.
Ongoing operational restructuring and cost controls, alongside battery business consolidation measures, are yielding improvements in adjusted operating margins and free cash flow, indicating enhanced profitability and the potential for structurally higher net margins as the company pivots to electrified products.
See why 22 investors see BorgWarner as 22% undervalued.
Result: Fair Value of $79.67 (UNDERVALUED)
Still, the story around BorgWarner can change quickly if combustion heavy product lines face faster than expected regulatory pressure, or if battery and charging demand stays soft for longer.
Find out about the key risks to this BorgWarner narrative.
Another View On BorgWarner’s Valuation
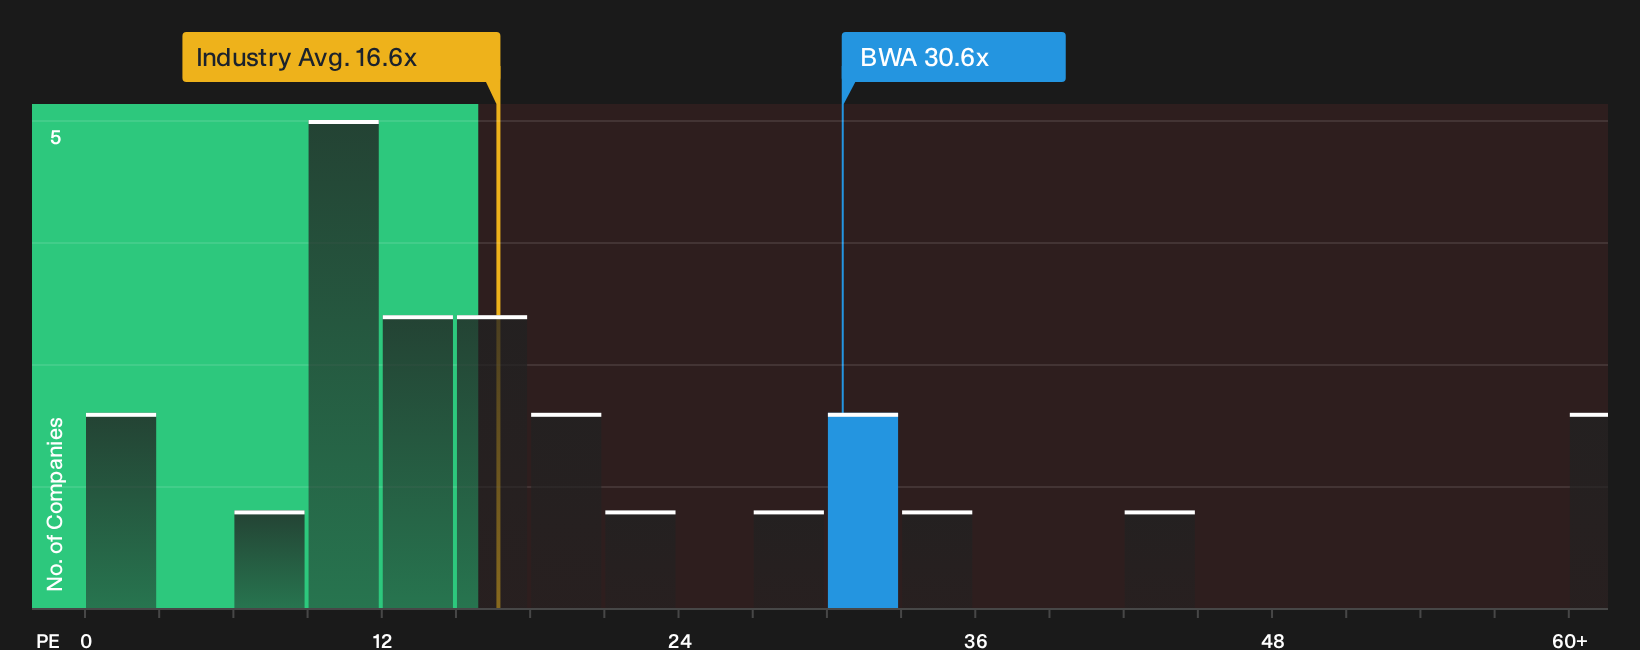
While the narrative fair value for BorgWarner sits at $79.67, the current P/E of 30.6x creates a different picture. That multiple is higher than both the peer average of 14.2x and the fair ratio of 19.8x. This points to a richer pricing that could compress if sentiment cools.
For investors who prefer to lean on earnings multiples, this gap raises a simple question. Is the market rewarding BorgWarner for future execution that has not played out yet, or is it overpaying for recent momentum that could prove temporary for the stock?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals around BorgWarner’s valuation and outlook, sentiment is clearly split. Move quickly, review the details, and weigh both sides through the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond BorgWarner?
If BorgWarner has your attention, do not stop here. The market often rewards investors who keep hunting for strong setups instead of focusing on a single opportunity.
- Target reliable income streams by scanning companies with robust payouts and steady cash generation through the 6 dividend fortresses.
- Spot resilient businesses that aim to protect your downside by filtering for firms in the 11 resilient stocks with low risk scores.
- Zero in on underfollowed opportunities with strong fundamentals by checking the 16 high quality undiscovered gems before they get crowded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com