


Is Eli Lilly (LLY) A Bargain Following Fresh Obesity Drug Data?
Eli Lilly (LLY) just put fresh clinical data at the center of its story, highlighting new results for obesity and diabetes drugs and a genetic medicine collaboration with QurCan Therapeutics.
Recent price action has cooled a little, with a 30-day share price return that declined 3.83%, even as Eli Lilly’s stock still shows a 5.32% year-to-date share price gain and a very strong 1-year total shareholder return of 50.63%. This points to momentum that remains firmly positive over a longer horizon.
Capitalize on Eli Lilly’s cardiometabolic momentum by scanning a hand-picked set of resilient health and quality plays in our 11 resilient stocks with low risk scores.Eli Lilly now carries a trillion dollar valuation, yet the shares have paused after their surge. Is that brief pullback enough of a reset, or does patience make more sense before leaning in further on this story?
Most Popular Narrative: 23% Undervalued
Eli Lilly’s most followed narrative pegs fair value at about $1,477 per share, compared with the recent $1,137.82 close. This frames the trillion dollar tag as still short of what the underlying business could justify using that model and a discount rate of 7.5%.
Eli Lilly already runs one of the fastest-growing drug businesses on earth, and its most powerful drug is not even approved yet.
The pricing headwinds are real, but they are happening to a company with manufacturing scale, regulatory depth, and a next-generation compound that has already beaten the highest analyst expectations in Phase 3.
See why 65 investors see Eli Lilly as 23% undervalued.
According to AHaron, the narrative hinges on cardiometabolic products that already generate very large revenue alongside a pipeline that could add entirely new streams on top of that base. The fair value estimate of $1,477 uses a 7.5% discount rate and still lands above the $1,324 analyst target that currently implies a 16.4% gap from the market price. This shows how different frameworks can point to similar “priced below model” conclusions even when assumptions vary.
The same storyline points to earnings growth, forecast at 17.05% per year, and a net income margin that most recently sat in the low 30s, as the key financial gears behind that valuation. High returns on equity, flagged at 78.84% but influenced by leverage, and rising profitability over the past five years sit alongside a warning on debt levels and funding mix, which keeps the risk side of the equation in clear view.
For readers weighing the trillion dollar market cap against these narratives, the tension is simple to frame. AHaron’s fair value suggests Eli Lilly trades at a discount of 23% to that $1,477 estimate, while Simply Wall St’s own cash flow work points to an even higher figure of $1,706.34, with the stock described as 33.3% below that internal appraisal.
Result: Fair Value of $1,477.03 (UNDERVALUED)
Still, Eli Lilly’s story can break if retatrutide stumbles in later trials or if obesity pricing pressure bites harder than current models assume.
Find out about the key risks to this Eli Lilly narrative.
Another View: Eli Lilly Through The P/E Lens
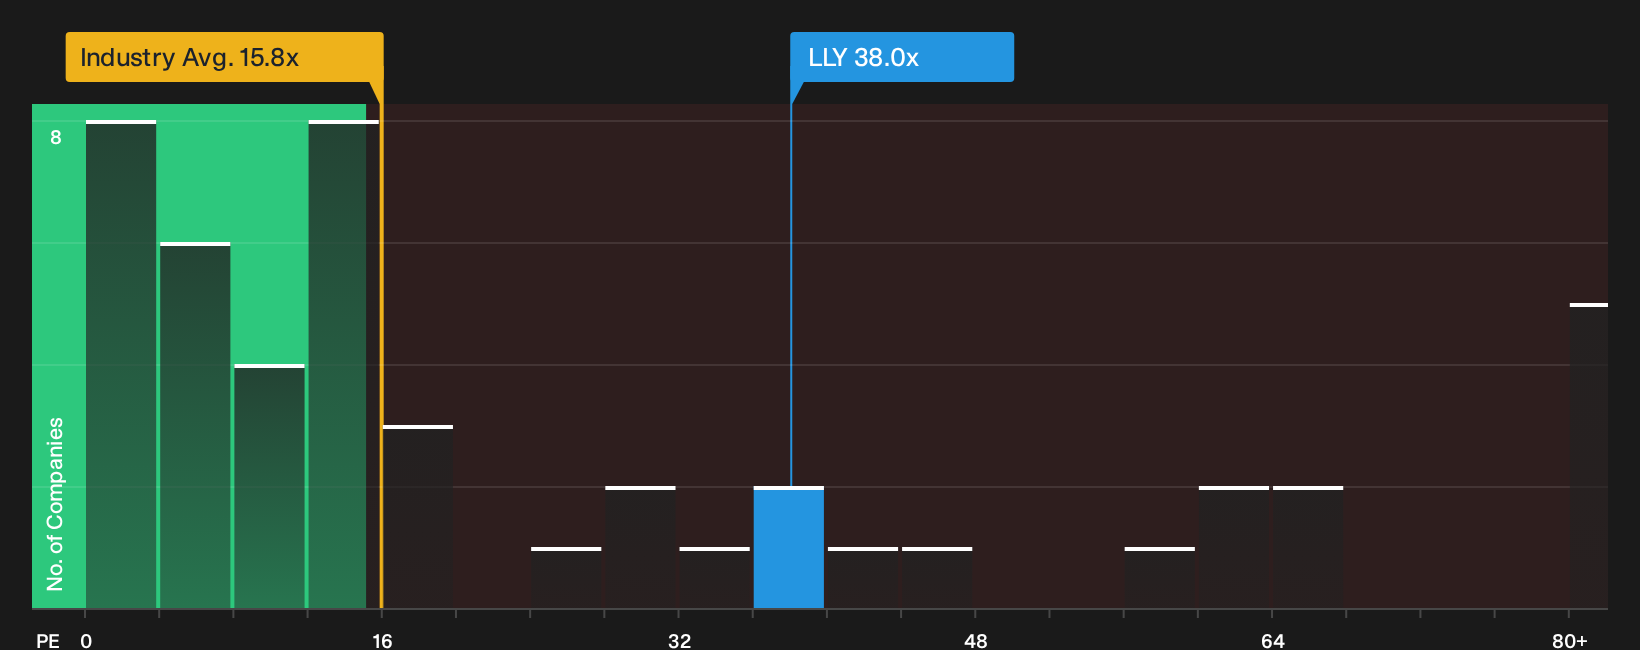
Eli Lilly may look attractively priced against some fair value models, but the P/E tells a tougher story. The stock trades at 38x earnings compared with 15.8x for the US Pharmaceuticals industry and a 45.7x fair ratio that the market could gravitate toward over time.
That gap means investors are already paying a premium versus the sector, even if peers on average trade richer at 48.3x. The question is simple for anyone considering fresh capital: Is this premium a reasonable entry ticket to Eli Lilly’s growth narrative, or a thinner margin for error than the models suggest?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Eli Lilly story today presents mixed signals. Analyze the underlying data promptly, and consider both risks and rewards with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Eli Lilly?
Eli Lilly gives you a strong starting point, but your next win might come from a very different corner of the market. Do not let those opportunities pass by.
- Target resilient performance by scanning a list of solid balance sheet and fundamentals (22 results) that can better handle shocks and still keep their fundamentals intact.
- Hunt for mispriced potential through a curated 16 high quality undiscovered gems that many investors have not fully examined yet.
- Strengthen your portfolio’s income stream by reviewing a focused 6 dividend fortresses designed for investors who want meaningful yield with substance behind it.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com