


Is Defense Expansion Altering The Investment Case For HEICO (HEI)?
- HEICO expanded its defense reach by acquiring 80% of UK based Cook Defence Systems and its VPT unit introduced the FLX Series DC-DC converter for harsh mission critical environments, while broader aerospace demand for replacement parts remains supported by higher passenger traffic and ongoing supply chain constraints.
- The combination of a larger defense portfolio and a new prequalified power solution suggests HEICO is leaning into mission critical, higher specification niches where technical reliability and certification requirements can create stickier customer relationships and potentially steadier demand.
- We will now look at how HEICO's Cook Defence Systems acquisition could reshape the investment narrative investors use to frame this business.
What Is HEICO's Investment Narrative?
The core HEICO pitch is pretty simple. You need to believe this is a collection of niche, mission critical aerospace and defense suppliers that can keep finding specialized products, integrate them well and keep quality high while airlines and defense customers continue to value reliability over chasing the lowest sticker price. That is an execution story around disciplined M&A, consistent operations and tight engineering culture more than a single headline program.
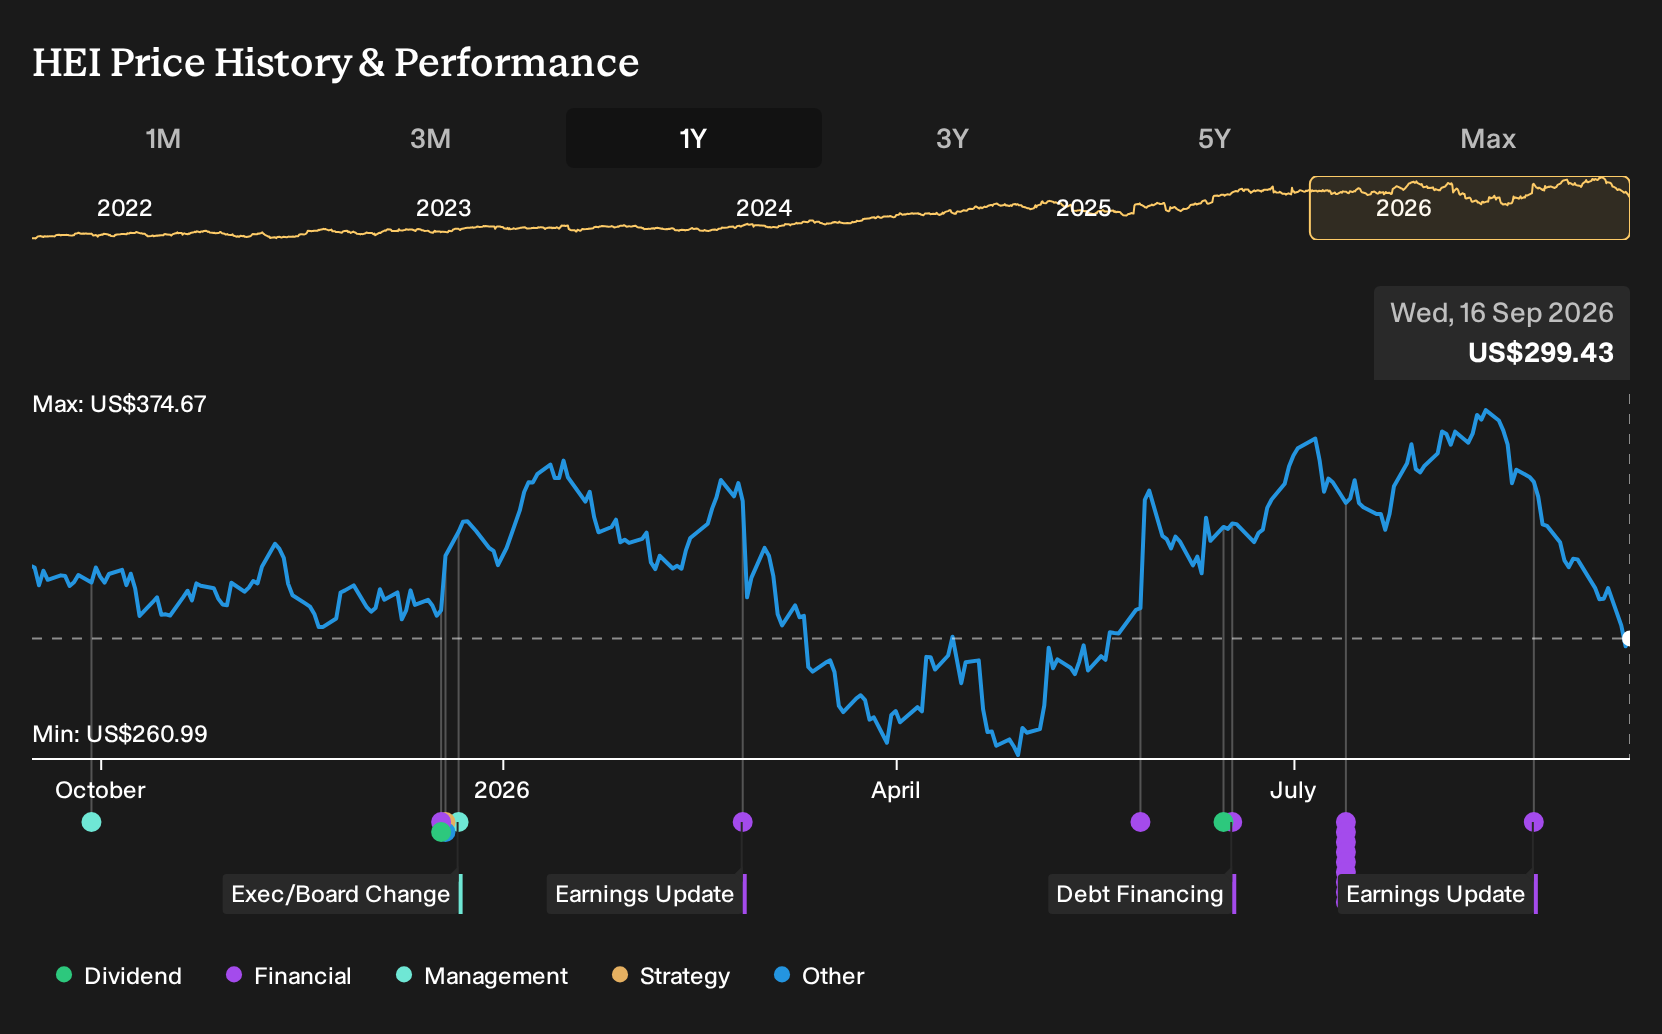
The Cook Defence Systems deal and VPT FLX Series rollout both point in the same direction. Management is leaning into higher spec, harsh environment use cases where qualification and replacement needs can support steadier demand, even as travel patterns or defense budgets move around. In the short term, the bigger questions are whether HEICO can keep absorbing acquisitions without tripping on integration risk, manage a relatively high P/E against recent share price volatility and stay comfortable with debt levels while funding this playbook.
Even so, there is one pressure point in HEICO’s story that deserves a closer look once you consider how all of this is being financed.
There's only one way to know the right time to buy, sell or hold HEICO. Head to Simply Wall St's company report for the latest analysis of HEICO's Fair Value.
Exploring Other Perspectives
Some of the most optimistic HEICO analysts frame the story very differently from the recent pullback and integration worries. They were pencilling in revenue of about US$7.7b and earnings of roughly US$1.4b by 2029, with higher margins and a richer P/E. Those forecasts predate the Cook Defence Systems deal and VPT launch, so you should expect fresh debate as this news gets absorbed.
Explore 3 other HEICO fair value estimates, including one that suggests potential upside of up to 32% from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your HEICO research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for HEICO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HEICO's overall financial health at a glance.
Looking For More Investment Ideas Beyond HEICO?
If HEICO has you thinking about where else mission critical spending and steady cash flows might show up in your portfolio, it can help to cast a wider net. The Simply Wall St Screener lets you filter for specific traits so you can line up potential candidates that actually fit your own risk and return preferences rather than chasing headlines.
- If capital protection sits at the top of your list, start with companies that screen well on resilience and risk controls through the 11 resilient stocks with low risk scores.
- For investors focused on quality at a reasonable entry point, narrow the field to financially robust businesses trading below their assessed value via the 33 high quality undervalued stocks.
- Those hunting for underfollowed opportunities can zero in on smaller, fundamentally strong companies that attract less attention using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com