


How Investors Are Reacting To Clorox (CLX) GOJO Acquisition
- Clorox is pushing ahead with margin management, product development and its IGNITE program while absorbing inflation and softer consumer demand, and it has added GOJO to deepen its health and hygiene exposure.
- The GOJO deal ties Clorox more tightly to institutional cleaning and hygiene spending, which can behave differently from household demand when conditions are weak.
- The focus now shifts to how Clorox's GOJO acquisition could reshape the broader investment narrative that investors already use to judge the business.
Compare how Clorox stacks up on quality, pricing power and balance sheets by scanning a curated group of 11 resilient stocks with low risk scores that tend to hold up when conditions get tougher.
Clorox Investment Narrative Recap
To stay in Clorox, you need to believe the core cleaning, household and wellness portfolio can keep earning its shelf space while the firm repairs margins and absorbs weaker demand. The big short term swing factor is whether pricing, productivity gains and IGNITE execution offset cost pressure without eroding brand loyalty in categories facing heavy discounting.
The main risk right now sits on the cost and cash front. Dividend cover and debt metrics already look tight, so any stumble in category demand, ERP rollout or mix in Glad, litter or grilling could narrow financial flexibility just when Clorox is integrating GOJO and bedding down higher institutional exposure.
The GOJO acquisition is the key recent move that ties directly into this story. It pushes Clorox deeper into health and hygiene, and into institutional customers whose spending patterns do not always match retail demand. That could smooth parts of the revenue base if execution is clean and product superiority holds.
For catalysts, watch how quickly GOJO gets folded into Clorox’s ERP, margin management and IGNITE playbook. If management integrates logistics, procurement and commercial teams effectively, the deal can support the thesis that Clorox is more than a slow household products group. If integration drags or private label pressure intensifies, the added debt load could feel heavier.
Clorox's current analyst narrative points to revenues of US$8.0b and earnings of US$871.3m by 2029, based on an assumed 6.1% yearly revenue growth rate and an earnings increase of about US$284m from US$587.0m today.
Uncover why Clorox's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
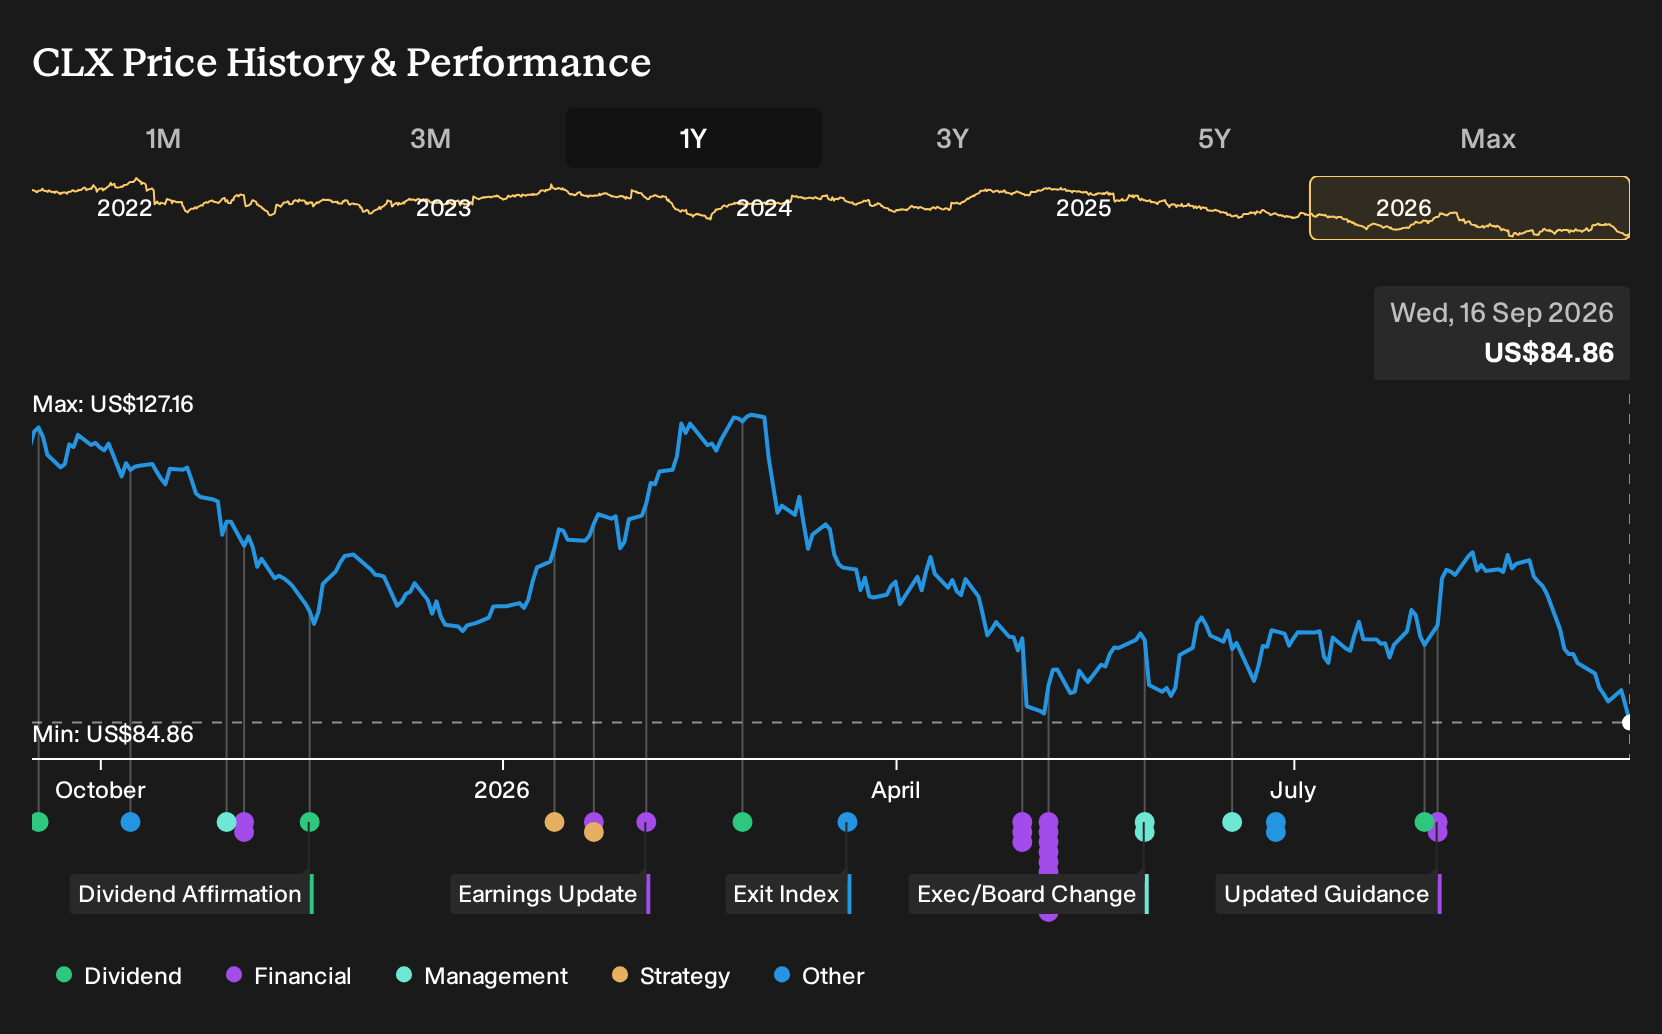
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into ERP and digital benefits for Clorox, expecting revenues of about US$8.2b and earnings near US$894.7m by 2029. You might see that as too punchy. Especially with the GOJO deal now in play, those upbeat pre news forecasts could shift meaningfully.
Explore 5 other Clorox fair value estimates, including one that suggests as much as 182% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Clorox research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clorox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Clorox's overall financial health at a glance.
Looking for more investment ideas beyond Clorox?
If the Clorox story has sharpened your thinking on brands, cash generation and resilience, broaden that lens to a wider watchlist. The Simply Wall St Screener can help you quickly filter businesses that line up with your risk appetite, income needs or value focus so you are not relying on a single stock to carry the load.
- For investors who care most about capital protection and steadier return profiles, start with a 11 resilient stocks with low risk scores that historically tend to ride out tougher conditions more calmly than the broader market.
- If your priority is owning financially sound companies with room to reinvest, target a list of solid balance sheet and fundamentals (22 results) so you can zero in on firms with strong fundamentals and less reliance on fragile funding.
- Income focused investors can put yield in context by scanning a 6 dividend fortresses that can turn a watchlist into a shortlist of candidates for further dividend research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com