


How Lower Half Year Earnings Will Impact Helvetia Baloise Holding Stock (SWX:HBAN)
- Helvetia Baloise Holding reported half year 2026 net income of CHF 68.6 million, with basic and diluted EPS from continuing operations at CHF 0.66, compared with CHF 307.2 million and CHF 5.75 a year earlier.
- The sharp drop in profitability highlights pressure on Helvetia Baloise Holding's earnings power. This is important for funding growth plans and absorbing insurance claims volatility.
- We will now see how Helvetia Baloise Holding's investment narrative compares with this steep fall in half year earnings.
Helvetia Baloise Holding Investment Narrative Recap
To own Helvetia Baloise Holding, you need to be comfortable with an insurer that leans heavily on operational efficiency, digital tools and disciplined underwriting across core European markets. The sharp drop in half year net income to CHF 68.6 million and EPS of CHF 0.66 puts the immediate focus on basic earnings power and how resilient the business model is to claims volatility and integration costs.
Right now, the key short term swing factor is execution on cost programs and pricing discipline in higher risk lines, while integration work around Baloise could add one off pressure. The biggest near term risk is that volatile catastrophe claims or merger related expenses keep recurring, which would make earnings more erratic and slow delivery of the targeted CHF 200 million efficiency gains by 2027.
The relevant reference point for this earnings print is the existing plan for more than 360 efficiency initiatives that are intended to generate CHF 200 million of cost savings by 2027. With half year profit at CHF 68.6 million, your main question is whether these programs can offset claim costs and merger expenses quickly enough to stabilise profitability from here.
If you are tracking catalysts, those efficiency measures connect directly to the story of earnings forecasts and Helvetia Baloise Holding’s valuation debate. Analysts currently expect faster revenue and profit growth than the broader Swiss market, alongside a P/E that is above industry averages. This makes the success or delay of these cost savings central to how comfortable you feel with the stock’s risk reward trade off after such a weak half.
Helvetia Baloise Holding’s current analyst story points to revenues of CHF 19.0b and earnings of CHF 1.1b by 2029, based on assumptions of 22.6% yearly revenue growth and an increase in earnings of about CHF 554m from CHF 545.8m today.
Uncover why Helvetia Baloise Holding's fair value indicates an 8% potential upside to its current price that could narrow quickly.
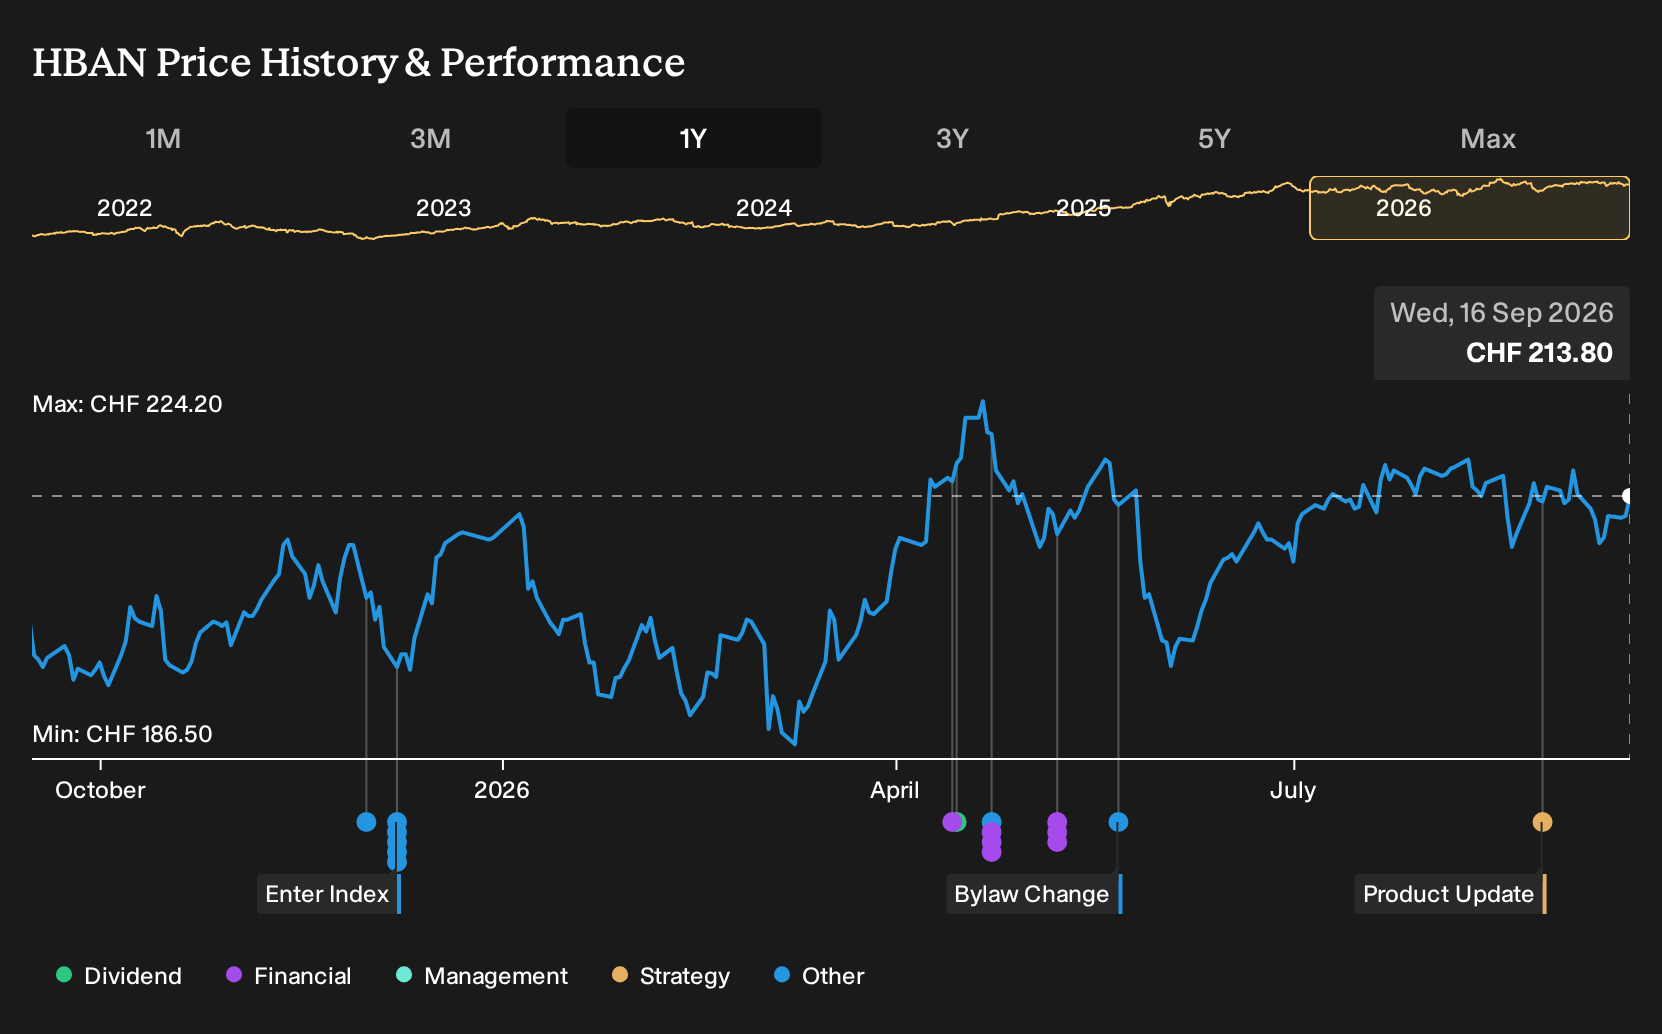
Exploring Other Perspectives
One alternate angle on Helvetia Baloise Holding focuses less on cost savings and more on pressure from climate related claims and low interest income. The most cautious analysts were already working with 2029 revenue near CHF 17.8b and earnings around CHF 1.0b before this weak half year. You can treat those lower figures as a stress test and ask whether this earnings shock pushes expectations even closer to that bearish path or forces a complete rethink.
Explore 3 other Helvetia Baloise Holding fair value estimates, including one that suggests it could be worth just CHF 231.36.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Helvetia Baloise Holding research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Helvetia Baloise Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Helvetia Baloise Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Helvetia Baloise Holding?
If Helvetia Baloise Holding has sharpened your focus on earnings quality, risk and valuation, it can help to line it up against a broader watchlist. Use the Simply Wall St Screener to quickly surface other opportunities that fit the kind of balance sheet strength, income profile or valuation characteristics you want to compare.
- If capital preservation is high on your list, filter for resilient businesses using our 104 resilient stocks with low risk scores to see which stocks currently combine lower risk scores with solid fundamentals.
- If dependable income streams matter to you, scan for high yielding opportunities with the 161 dividend fortresses and see which companies pair sizeable payouts with more robust balance sheets.
- If you prefer to hunt for mispriced opportunities, cast a wider net using the 619 high quality undiscovered gems and focus on candidates with strong financial profiles that may be getting less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com