


Strong Demand, Weak Margins: GCT Semiconductor Could Be a Big Second Half Story
GCT Semiconductor Holding (GCTS) expects 5G chipset shipments in the second half of 2026 to surpass first-half volumes. The company points to secured production capacity and growing customer engagement across satellite, terrestrial, and defense markets as key drivers. However, the second quarter results raise some concerns. Chipset shipments rose 71% sequentially to over 5,100 units. Yet revenue fell 18% year over year while gross margin turned negative. That leaves investors weighing two possibilities. Is GCTS moving toward a turning point in profitability, or is it growing shipments at the expense of the pricing power and margins needed to sustain that growth?
Secured Capacity and a Stronger Cash Position Support the Outlook
GCT Semiconductor entered the second half of the year with a stronger balance sheet. The company ended the quarter with $30.2 million in cash and cash equivalents, up significantly from $7.2 million in the first quarter. Management also confirmed that production capacity has already been secured for the rest of 2026 and through the first quarter of 2027. This helps reduce the risk of supply constraints as shipments increase. GCT further expanded its customer base after quarter-end by signing a new customer for UAV and defense-related connectivity.
About GCT Semiconductor Stock
GCT Semiconductor operates as a fabless B2B company serving industrial and consumer applications worldwide. It is better known for its wireless communications technology, supplying 4G LTE, 5G, and IoT semiconductor solutions. It is headquartered in San Jose, California.
GCTS stock surged over 110% in May, thanks mainly to an explosive Q1 revenue jump and expansion into the satellite communications market. This happened around the same time as the SpaceX (SPCX) IPO, when anything space-related was going up, so GCTS stock went along for the ride. Over the last year, though, the stock is only up 23.8%.
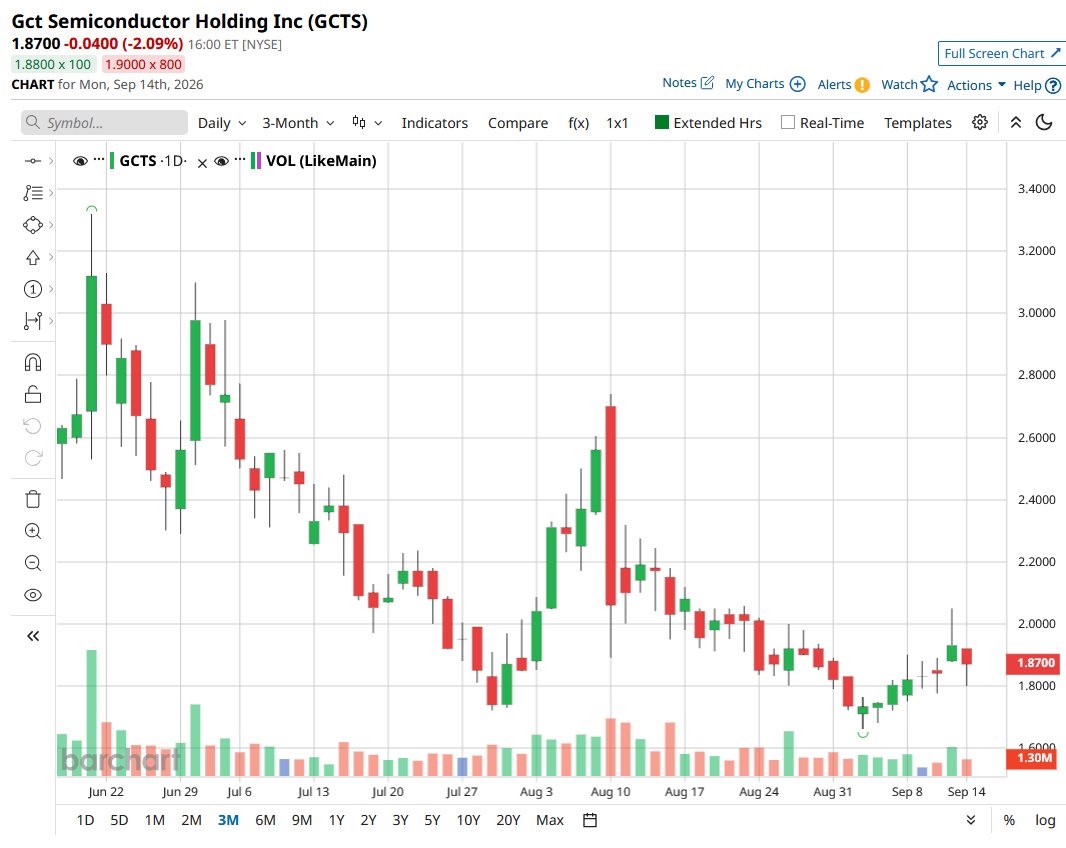
GCT Sees Strong Demand Despite Launch Delays
GCT Semiconductor Holding reported its second-quarter fiscal 2026 earnings on August 10. Net revenues decreased by $0.2 million, or 18%, from $1.2 million a year earlier. CFO Fong Cheng said cost of revenue rose 49% year over year to $1.2 million from $0.8 million. In addition, net loss increased to $20.4 million from $13.5 million a year earlier. The quarter's loss included a $12.3 million non-cash charge related to warrant liabilities. The increase was driven by a rise in the company’s share price and the value of its publicly traded warrants during the quarter. Management framed the quarter as part of a longer commercialization process rather than a sign of weakening demand. GCT Semiconductor is still in the early stages of turning its 5G chip platform into a larger commercial business.
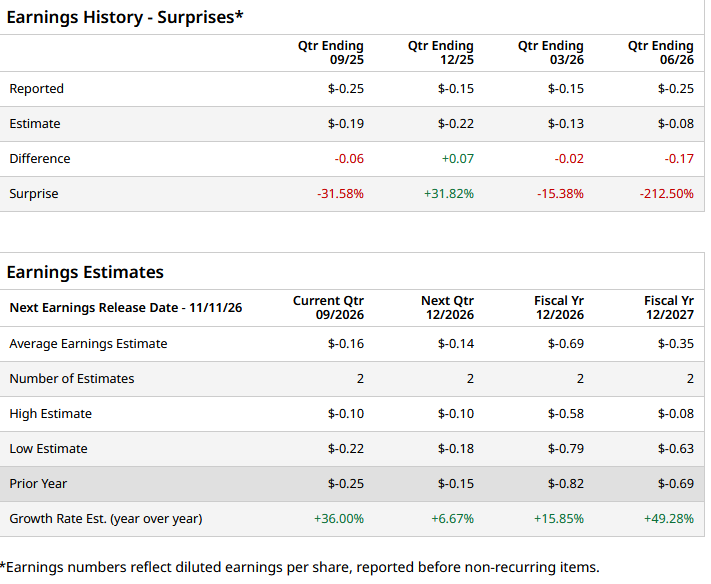
Looking forward, the company expects the second half of 2026 to bring higher shipments than the first half. The company also said it has secured wafer capacity for the rest of 2026 and through Q1 2027. Gross margins are expected to improve as 5G product sales become a larger part of revenue. Management said cash burn should normalize to $8.0 million to $8.5 million per quarter in Q1 2027.
GCTS stock enjoys little analyst coverage on Wall Street, mainly due to its small size. However, as satellite communication becomes a more important part of AI and space infrastructure, Wall Street is bound to notice the opportunity presented by the stock. We already saw one such opportunity grabbed by the company when it announced a strategic partnership for next-gen UAV Control and Communications. There could be more of that to come soon.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.