


Is Weyerhaeuser Stock Underperforming the S&P 500?
Weyerhaeuser Company (WY) is one of the world’s largest private owners of timberlands and a major U.S. producer of wood products. The company manages millions of acres of timberlands across the U.S. and Canada, harvesting trees and turning them into lumber, oriented strand board, engineered wood products and other materials used in construction. Headquartered in Seattle, Washington, Weyerhaeuser has a market capitalization of roughly $16.1 billion.
Weyerhaeuser also generates revenue from timberland real estate, natural resources, energy and emerging climate solutions, giving the company several ways to monetize its vast land portfolio. That scale has pushed WY into “large-cap” territory, sitting comfortably above the commonly used $10 billion threshold for large-cap stocks.
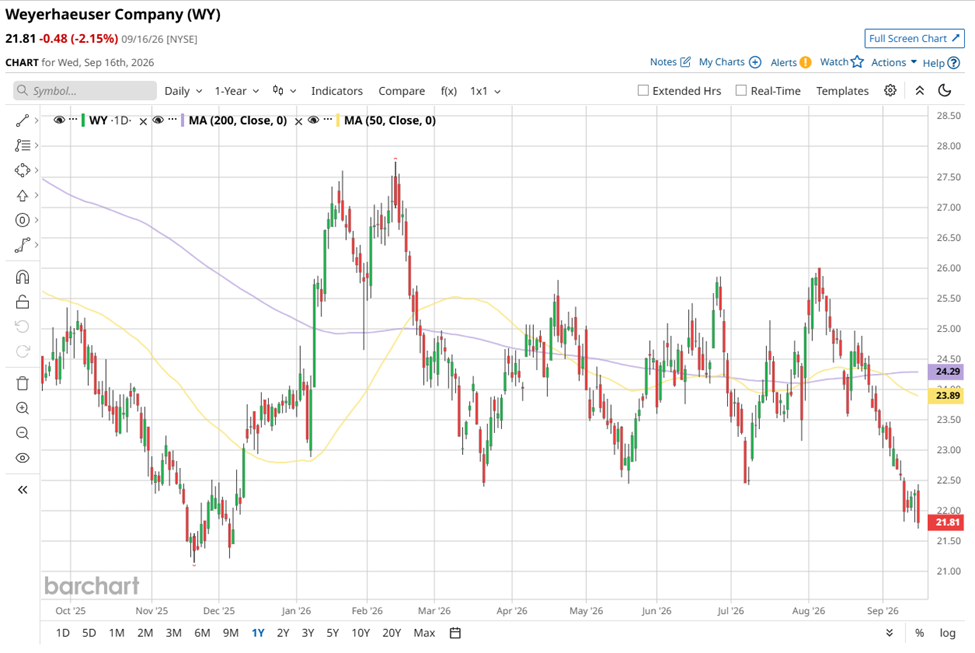
Shares of Weyerhaeuser have had a rough stretch lately. Shares are down 21.4% from their 52-week high of $27.75, reached on Feb. 12. The weakness has continued over the past three months, with WY stock falling 12%, while the S&P 500 Index ($SPX) has managed marginal gains over the same period.
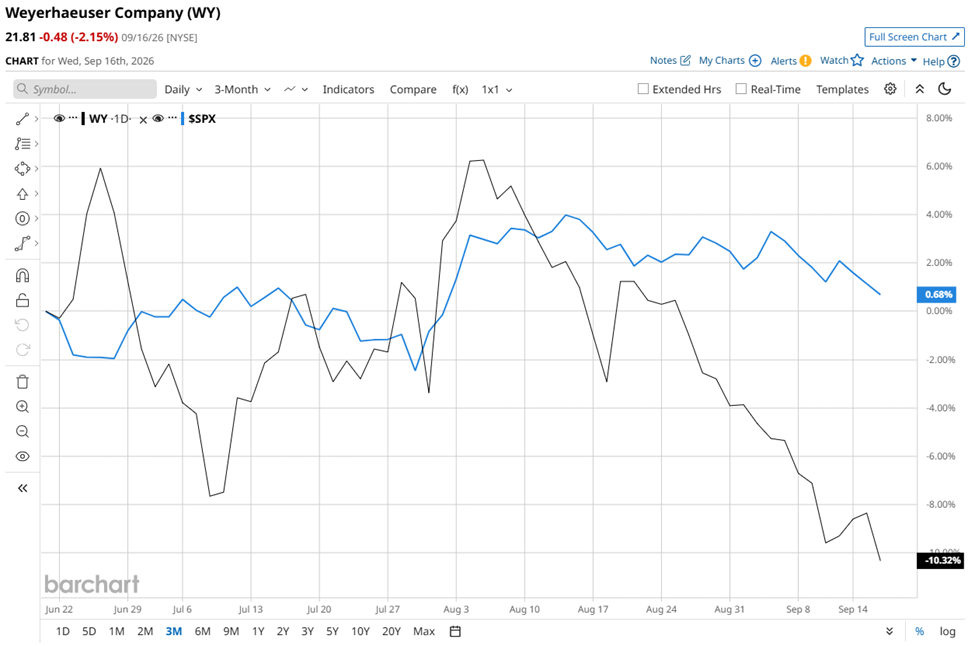
And if you zoom out a little, the picture does not get much prettier. Over the past 52 weeks, WY has slipped 12.6%, even as the S&P 500 has climbed 14.3%. So far in 2026, the gap remains visible, with WY down 7.9% compared with a 10.3% gain for the broader index.
The technical picture adds another layer of caution. WY is trading below both its 50-day and 200-day moving averages, suggesting the stock remains under pressure.
Weyerhaeuser’s weak stock performance over the past year has largely reflected a problem that is bigger than the company itself – the U.S. housing market. After the post-COVID construction boom faded, higher mortgage rates and expensive financing have kept homebuilding activity under pressure. And with long-term rates still elevated, investors have little reason to expect a quick turnaround. Fewer homes being built ultimately means less demand for lumber and other wood products, which has weighed on expectations for WY’s earnings.
There is a bit of a twist, though. Lumber prices have recently bounced back as supply constraints tightened the market. That sounds encouraging, but investors appear more focused on whether those higher prices can last when residential construction and renovation activity remain soft. With demand recovery potentially stretching into 2027, the earnings outlook remains difficult to read.
Meanwhile, higher manufacturing and transportation costs have added another headache, while broader economic uncertainty has kept housing-linked stocks out of favor.
WY’s performance looks a little less concerning when you put it next to its peer Rayonier Inc. (RYN). While the two operate in the same broader space, RYN stock has also struggled, falling 7.4% YTD and 22.7% over the past 52 weeks. That means RYN has actually held up slightly better than WY so far in 2026, but its decline over the past year has been steeper, giving WY a slight edge over the longer timeframe.
Despite WY stock’s underperformance, analysts remain moderately optimistic. The stock has a consensus rating of “Moderate Buy” from 13 analysts in coverage, and the mean price target of $30.42 represents a premium of 39.5% to current levels.
On the date of publication, Sristi Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.