


Will Affordable Homes Launch Change YIT's (HLSE:YIT) Narrative
- YIT Oyj has introduced the YIT Fiksu housing concept and started new projects such as Asunto Oy Jyväskylän Augusta and Helsingin Heikas. The focus is on high-quality, energy-efficient apartments with predictable housing costs and target prices around €3,500 per square meter on leased land.
- The combination of affordable, A-class energy-rated Fiksu homes and premium Formia apartments in central Helsinki shows YIT Oyj reallocating capital across both cost-efficient volume housing and higher-end urban projects. This aims to address changing demand patterns and construction cost pressures.
- The next area of focus is how YIT Oyj's new Fiksu concept for affordable, predictable-cost apartments could reshape its broader investment narrative.
YIT Oyj Investment Narrative Recap
To own YIT Oyj, you need to be comfortable with a cyclical residential builder that is still loss making but priced on the idea that earnings can recover as projects turn and operational efficiency improves. The key short term swing factor remains how quickly new launches convert into reservations and then completions in Finland and CEE, where timing can distort quarterly profit.
The biggest risk is still financial pressure if sales slow, given interest costs are not well covered by current earnings and the sector remains competitive. The Fiksu rollout and new Formia projects do not fundamentally change that in the near term. They mainly shift the project mix rather than removing the exposure to a weak Finnish housing market.
The launch of the YIT Fiksu concept is the most relevant recent announcement. It directly targets affordability and A class energy performance, with target prices around €3,500 per square meter on leased land and cost savings from compact layouts, durable materials and scalable construction. That fits the broader push toward capital efficiency and energy efficient housing.
For catalysts, Fiksu could help YIT Oyj keep volumes moving in a soft primary market by competing more directly with secondary apartments while offering predictable costs and no renovation backlog. Execution risk is real. Pre marketing in multiple cities and the first 40 home Augusta project in Jyväskylä test whether this template can scale without squeezing margins or adding earnings volatility.
YIT Oyj's current analyst narrative points to revenues of €2.2 billion and earnings of €69.3 million by 2029, built on forecast annual revenue growth of 8.1% and an earnings swing of about €131 million from a loss of €62.0 million today.
Uncover why YIT Oyj's fair value indicates a 25% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
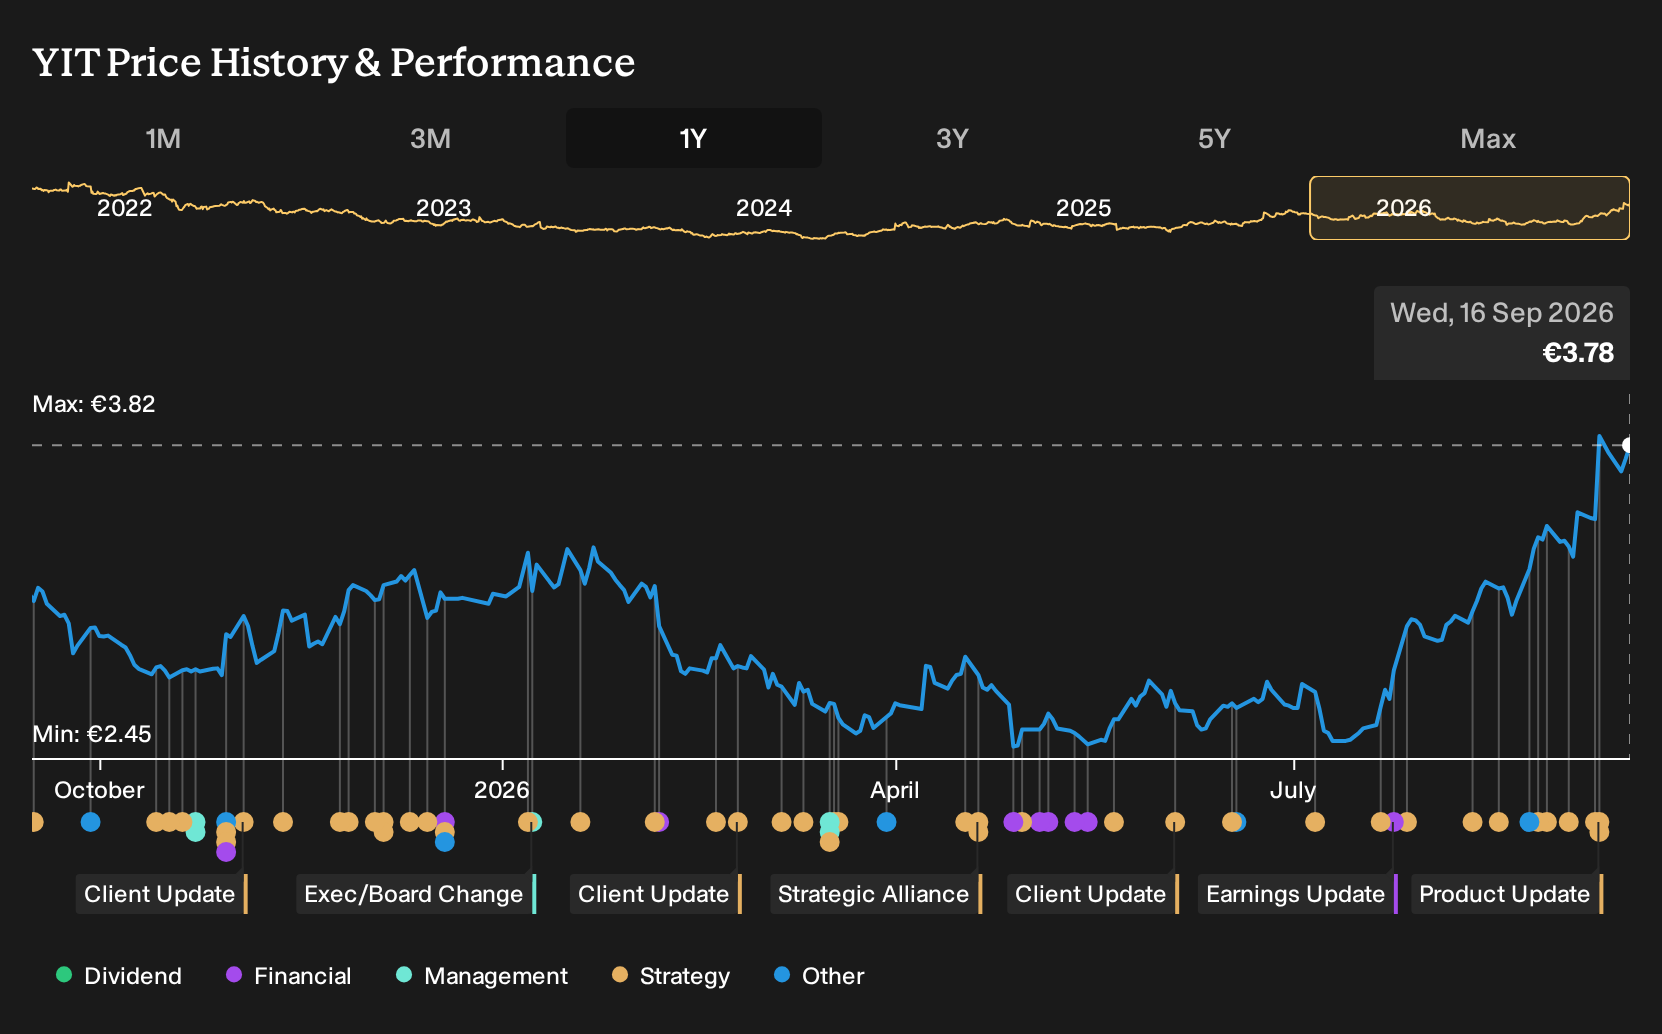
Two fair value views from the Simply Wall St Community span roughly €2.82 to €3.82 per share, which already shows how far opinions on YIT Oyj can stretch. You now have Fiksu and Formia project news layered on top of that, which could sharpen debates on leverage, profit volatility, and long run housing demand. Consider these estimates a starting point and explore several contrasting community viewpoints before forming your own thesis.
Explore another YIT Oyj fair value estimate, including one that suggests as much as 25% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your YIT Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for YIT Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate YIT Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond YIT Oyj?
If the YIT Oyj story has sharpened your thinking on risk, balance sheets and pricing power, it can help to compare it with other companies facing very different pressures. A focused screener gives you a faster way to line up alternatives that match your risk tolerance and income goals, rather than scrolling through endless tickers.
Here are a few curated angles to broaden your watchlist using the Simply Wall St Screener.
- If capital preservation is your priority and you want businesses that aim to weather tougher conditions, start by scanning 104 resilient stocks with low risk scores for ideas with more resilient profiles.
- If you are hunting for quality at a sensible price, use 187 high quality undervalued stocks to surface companies where fundamentals and valuation scores both look more compelling.
- If you prefer staying ahead of the crowd with lesser known opportunities, sift through 619 high quality undiscovered gems and build a shortlist before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com