


How Caliptra Security Support At Rambus Stock Has Changed Its Investment Story
- Rambus Inc. recently announced its CryptoManager Root of Trust now supports the open-source Caliptra specification, aiming to provide production-ready, hardware-level security for data center and AI SoCs with side-channel protections, cryptographic agility, and certification support such as FIPS 140-3 and SESIP.
- This move plugs Rambus directly into the CHIPS Alliance and Open Compute Project security ecosystem, giving chip designers a ready-made path to combine Caliptra-based device identity and attestation with a full security orchestration layer across CPUs, GPUs, AI accelerators and other infrastructure silicon.
- We will now look at how Rambus's Caliptra-ready Root of Trust platform could influence the investment narrative around its data center focus.
Rambus Investment Narrative Recap
To own Rambus, you need to believe its core bet on high speed memory interfaces and security IP for AI and data center workloads keeps finding real design wins as those markets evolve. The Caliptra ready CryptoManager Root of Trust fits that story, but on its own does not look like a near term swing factor for revenue or margins.
The more immediate catalysts still sit around DDR5, MRDIMM ramps and companion chips turning into a broader product engine. The main risk remains concentration in a few memory centric lines, layered on top of exposure to cyclical AI, data center and PC spending, as well as tight execution timing across several new technology transitions.
The product announcement that ties closest to that thesis is the Caliptra compatible CryptoManager Root of Trust for data center and AI SoCs. It positions Rambus to sell security alongside memory and interface IP, which matters if hyperscalers and chipmakers want a single vendor for both performance and protection across CPUs, GPUs and accelerators.
Operationally, that security platform touches multiple catalysts at once. It leans into AI infrastructure demand, deepens the IP portfolio used in custom ASIC and XPU work and widens the potential customer set beyond pure memory interface buyers. The execution test is whether this offering converts into visible licensing and product deals before any delays or competition pressure the existing memory focused business.
Rambus' current analyst setup points to forecast revenue of US$1.2b and projected earnings of US$418.1m by 2029. This implies 17.0% yearly top line growth and an earnings increase of about US$188m from US$230.0m today.
Uncover how Rambus' fair value points to an 83% potential upside compared with its current price, which may not last much longer.
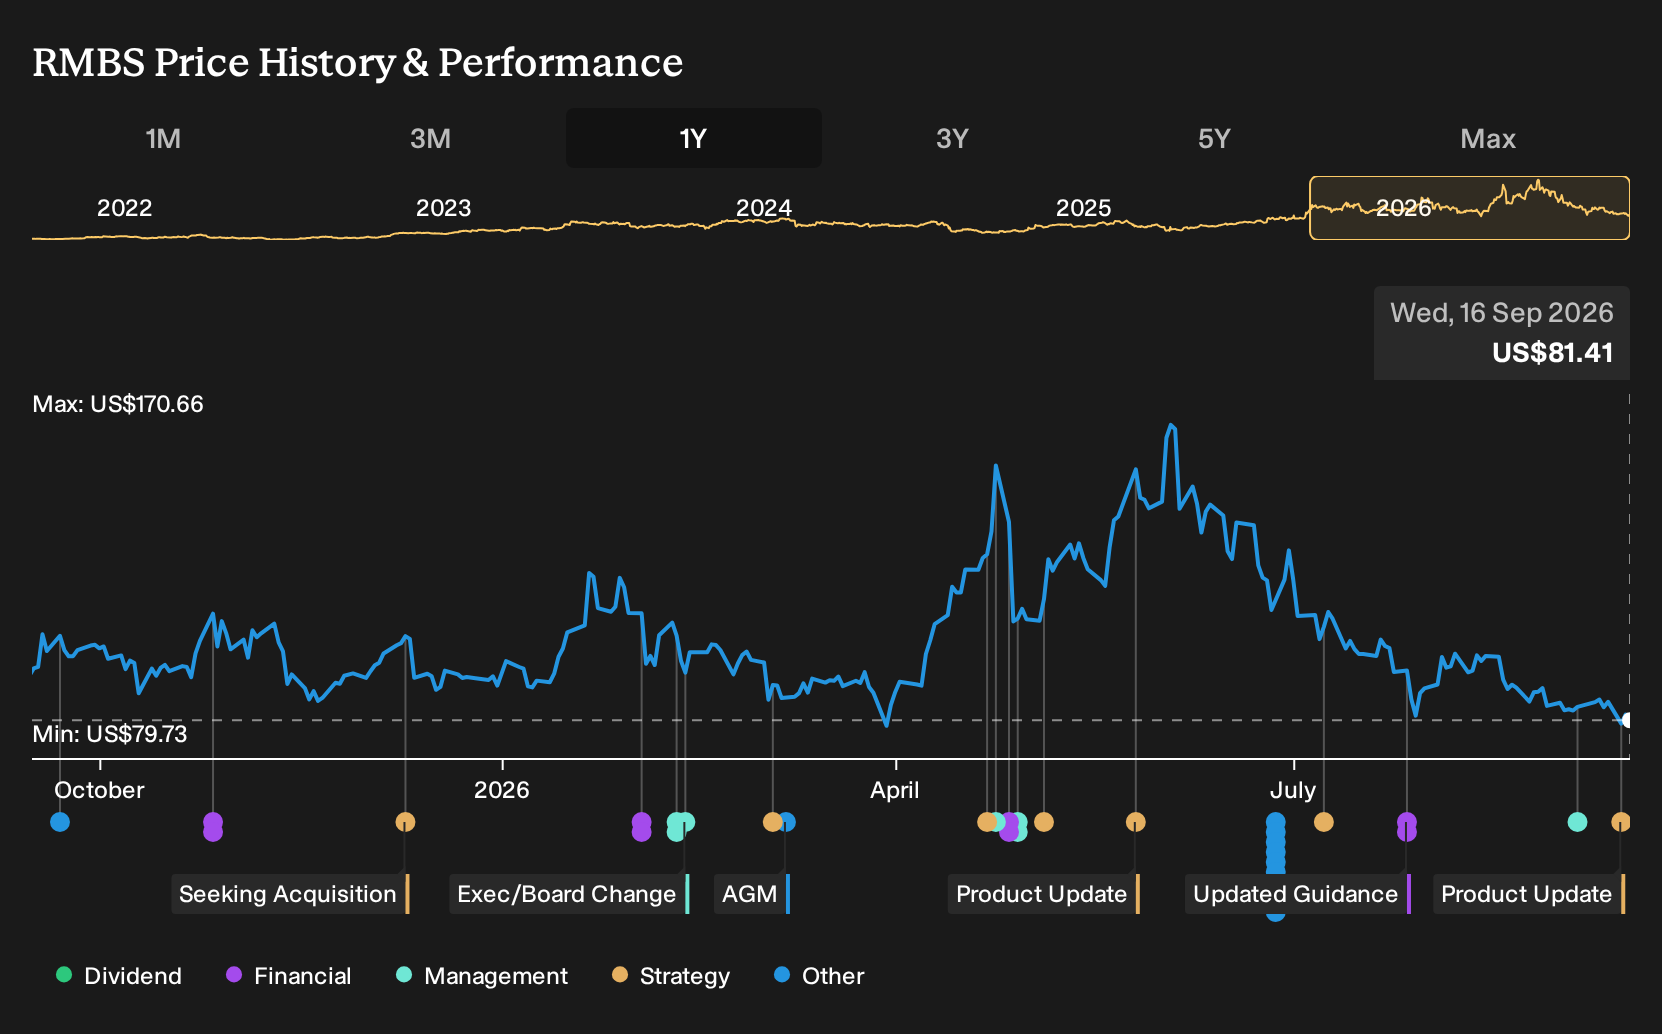
Exploring Other Perspectives
You might see this Rambus Caliptra move as a security catalyst, but the most cautious analysts were focused on slower DDR5 and MRDIMM ramps. Their pre news models pointed to revenue of about US$1.1b and earnings of US$391.9m by 2029, a softer path that leaves plenty of room for views to shift as new information lands.
Explore 3 other Rambus fair value estimates, including one that suggests as much as 60% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rambus research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rambus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rambus' overall financial health at a glance.
Looking For More Ideas Beyond Rambus?
If the Rambus story has you thinking about where else to allocate capital in AI and infrastructure, it can help to scan a broader field of opportunities with clear filters rather than chasing headlines one by one.
- If capital preservation is front of mind, focus on resilience first by scanning a hand picked set of 11 resilient stocks with low risk scores that score well on stability metrics.
- If income matters more to you, zero in on dependable cash returns by reviewing a curated group of 6 dividend fortresses built around higher yielding payouts.
- If you are hunting for overlooked potential, widen the search to a tightly selected pool of 16 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com