


Learn Why The Bull Case For Magna International Stock Could Change Following Earnings Beat
- Magna International recently reported record second quarter adjusted earnings per share and raised its full year 2026 sales and profitability outlook, reflecting confidence in demand for its electrification, software and automated driving components.
- The combination of a stronger first half and higher guidance underlines how Magna International’s diversified product mix ties directly to automaker spending on advanced vehicle content rather than just overall unit production.
- We will now assess how Magna International’s investment narrative could shift in light of the raised 2026 outlook following record quarterly earnings.
Scan how other auto and electrification suppliers are positioned by reviewing the hand picked 38 robotics and automation stocks that are moving with the same push toward software, automation and advanced vehicle content.
Magna International Investment Narrative Recap
To own Magna International, you need to believe that its mix of body structures, powertrain, vision systems and complete vehicles can steadily benefit from rising content per car, especially in electrified and software heavy models. The record quarter and higher 2026 outlook support that thesis on execution, but they do not remove exposure to weak vehicle production, FX swings and labor inflation.
The key near term swing factor remains margin improvement from operational work and restructuring, alongside better free cash flow as heavy battery enclosure spending eases. The biggest risk is that EV and broader production volumes stay soft or stay mixed in a way that keeps net margins under pressure, despite the higher guidance.
Recent commentary around operational excellence and restructuring is the clearest tie in to this earnings beat and higher outlook. Management has been emphasizing cost actions, new program launches and Factory of the Future initiatives that are intended to lift profitability across segments like Body Exteriors & Structures and Power & Vision as the order book converts.
For you as an investor, the link between those initiatives and the latest quarter is important. Stronger results help fund execution on margin projects, while any stumble on factory efficiency, mix or launch timing could keep net margin around the current 1.8% level. That would leave Magna International more exposed to production volatility and FX headwinds than the updated guidance implies.
Magna International's current analyst narrative points to $44.3b in revenue and $1.9b in earnings by 2029, based on an assumed 1.3% yearly revenue growth rate and a move from $761.0m in earnings today, which implies an earnings increase of roughly $1.1b by that forecast year.
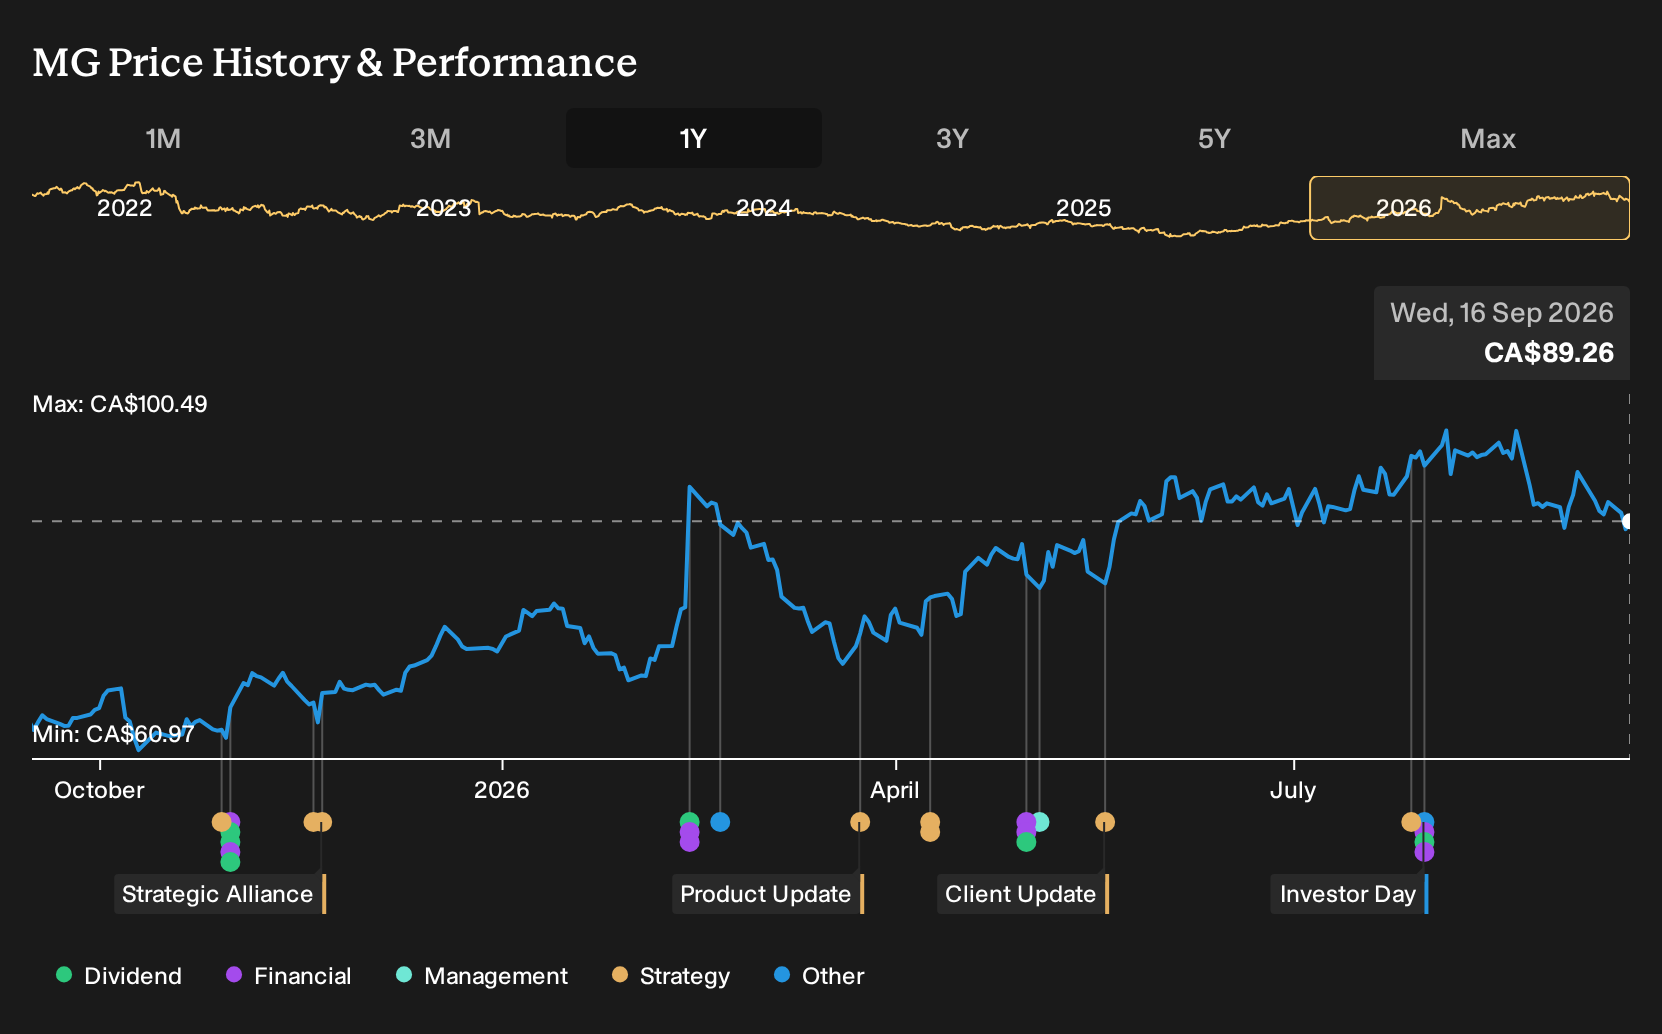
Uncover why Magna International's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest Magna International forecasts focus on slower electrification as the key risk. Those analysts were penciling in roughly flat revenue around $42.4b and earnings near $1.6b by 2029, compared with the $44.3b and $1.9b consensus. That is a much harsher read, and this earnings surprise could eventually shift those views.
Explore 2 other Magna International fair value estimates, including one that suggests it could be worth just CA$94.01.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Magna International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Magna International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magna International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Magna International?
If the Magna International story has sharpened your thinking, you can use that momentum to scan for other opportunities that fit different risk and return profiles. The Simply Wall St Screener lets you filter by balance sheet strength, valuation, dividends and more, so you can quickly build a shortlist that matches your own approach.
- For investors who want growth potential without ignoring quality, consider starting with a curated list of 9 high quality undiscovered gems that have strong underlying fundamentals.
- If capital preservation matters just as much as upside, you can narrow your focus to a 1 resilient stocks with low risk scores that have been filtered for resilience and lower risk scores.
- For income focused portfolios, you might prefer to concentrate on a set of 2 dividend fortresses that combine higher yields with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com