


Learn Why The Bull Case For Urban Outfitters Stock Could Change Following Conference Updates
- Urban Outfitters recently presented at Barclays' 19th Annual Global Consumer Staples Conference in Boston and the Goldman Sachs Global Consumer and Retail Conference in New York, focusing on its operations, portfolio and execution plans.
- Across these forums, Urban Outfitters highlighted its emphasis on logistics automation, store expansion and AI tools as levers to improve scalability and operating efficiency across its brands and channels.
- We will now look at how Urban Outfitters' investment narrative could be influenced by its focus on logistics automation and AI efficiency gains.
Scan other retailers leaning into automation and AI efficiency and see how Urban Outfitters compares to a curated group of 60 AI infrastructure stocks.
Urban Outfitters Investment Narrative Recap
To own Urban Outfitters, you need to believe the retailer can keep turning strong recent execution into steady, high quality earnings, even as earnings forecasts point to a flat path over the next few years. The near term swing factor is whether logistics automation, AI tools and store expansion actually support margins while tariff and cost pressures bite.
The biggest risk still sits in fashion volatility, early stage North America recovery and higher spending on marketing and new stores that could outpace sales if demand slows. The recent conferences do not fundamentally change that risk reward setup. However, they do keep attention on execution and cost discipline.
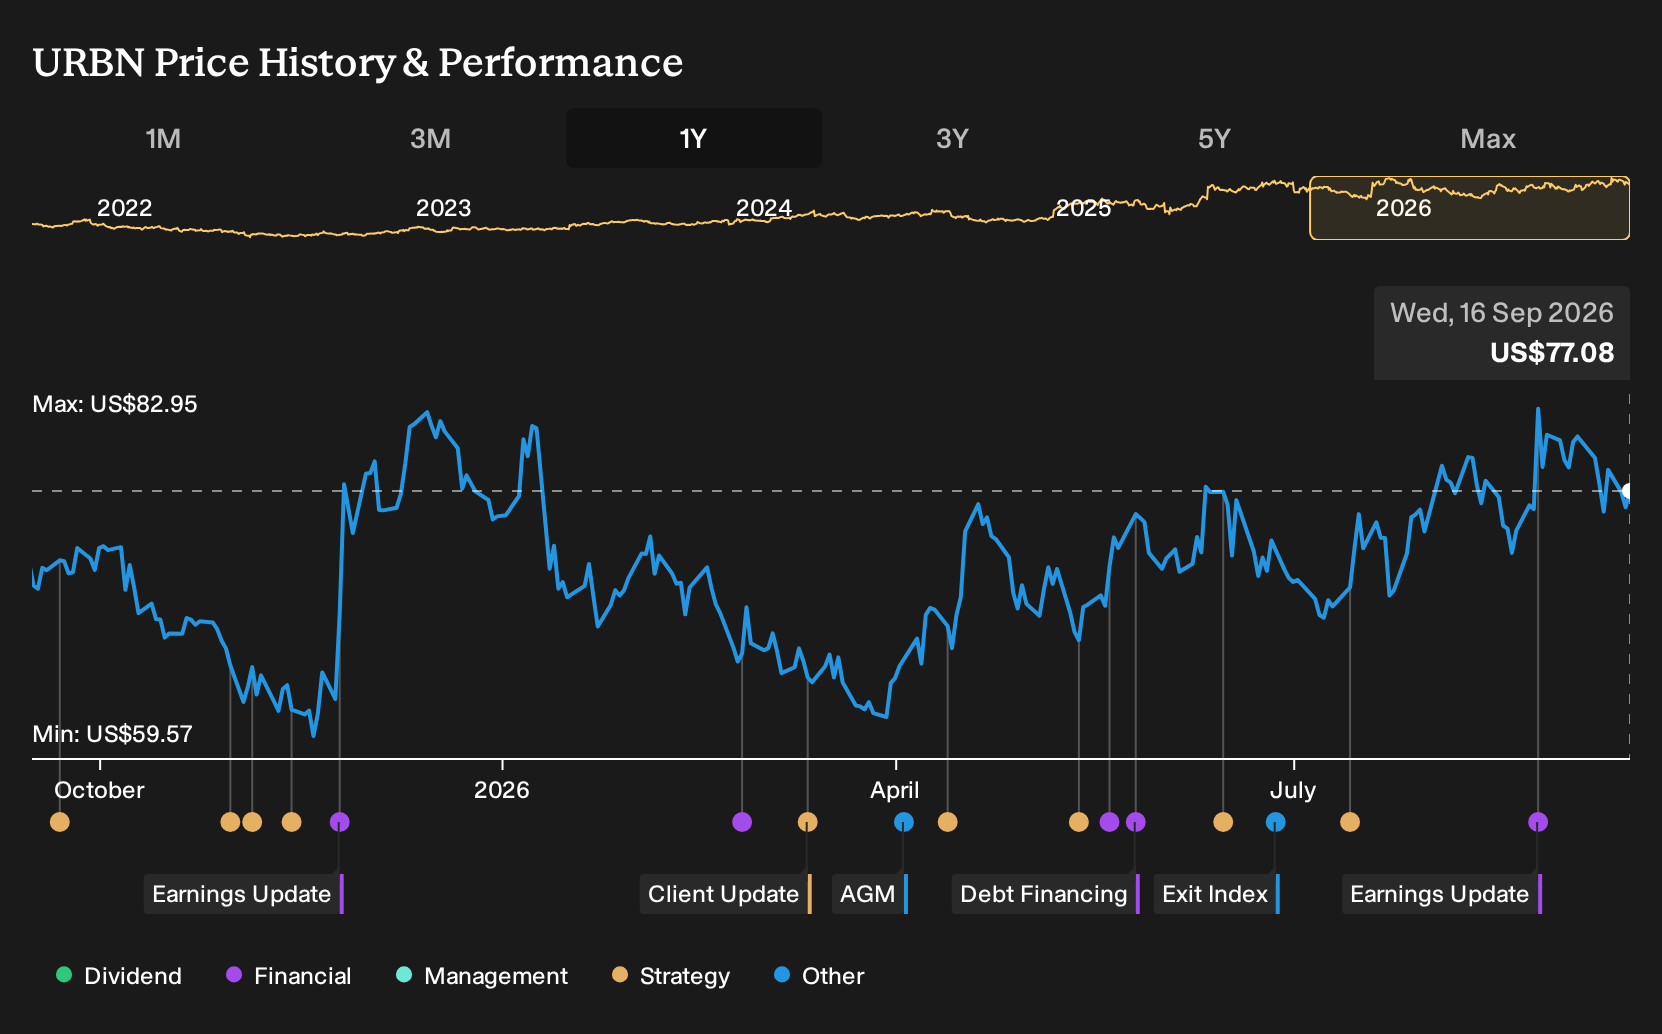
The Goldman Sachs Global Consumer and Retail Conference appearance on 15 September 2026 matters most right now because it keeps Urban Outfitters in front of investors at a time when consensus expects roughly flat earnings over three years. Any detail on automation, Nuuly scale up or omnichannel progress can shape how durable current margins look.
Conference commentary also ties directly to key catalysts. These include Nuuly subscription growth, e commerce integration, disciplined inventory management and international expansion. Concrete evidence that these themes are tracking well could help offset concerns about tariff headwinds, higher SG&A and the slower expected pace of profit growth from here.
Urban Outfitters' narrative projects US$7.9b revenue and US$581.0m earnings by 2029. This assumes 7.0% yearly revenue growth and an earnings increase of about US$11.9m from US$569.1m today.
Uncover why Urban Outfitters' fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans heavily on Nuuly as the real swing factor for Urban Outfitters. Bullish analysts were penciling in revenue growth of 8.2% a year and earnings of about US$662.4m by 2029 before these conference updates. That is far more optimistic than consensus and could shift again once the new automation detail is absorbed.
Explore 2 other Urban Outfitters fair value estimates, including one that suggests up to 16% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Urban Outfitters research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Urban Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Urban Outfitters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Urban Outfitters?
Once you have a view on Urban Outfitters, it can help to compare it with a wider set of businesses that share some of the qualities you care about, whether that is quality, value or resilience.
The Simply Wall St Screener lets you quickly filter the market to match those preferences. A few focused starting points are:
- If capital preservation comes first for you, consider reviewing 11 resilient stocks with low risk scores that combine resilient business profiles with lower risk scores.
- If balance sheet strength matters most, scan the list of solid balance sheet and fundamentals (22 results) to find companies with robust finances backing their operations.
- If you are hunting for overlooked stories, look through the 16 high quality undiscovered gems that pair solid fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com