


Interparfums (ENXTPA:ITP) Could Be 21% Undervalued After Weaker Half Year Results
Interparfums half year results and shifting sentiment
Interparfums (ENXTPA:ITP) has put fresh numbers on the table, reporting softer first half 2026 results that are now shaping the conversation around the stock for the rest of the year.
Interparfums’ recent half year earnings update lands after a strong 30 day share price return of 16.8% and a 20.5% year to date gain. However, the 3 year total shareholder return has declined 25.3%, which hints that recent momentum is building from a weaker longer term base.
Spot opportunities beyond Interparfums’ recent earnings reset by scanning a curated 188 high quality undervalued stocks that combines resilient cash flows with balance sheets built to handle softer trading periods.Interparfums is still putting up solid earnings in absolute terms, yet the share price has sprinted ahead after the half year wobble. So does the current valuation already bake that resilience in?
Price-to-Earnings of 21.2x: Is it justified?
On simple numbers, Interparfums changes hands at a P/E of 21.2x, which aligns closely with its direct peer average of 21.6x even after the recent share price rally from €28.78.
The P/E ratio compares what investors pay today for each euro of annual profit. For a fragrance and cosmetics group like Interparfums, that metric often reflects how steady buyers expect demand for its brands to be, as well as how reliable they judge its earnings profile.
While the stock screens as reasonable value against those peers, the picture shifts once you widen the lens. The same 21.2x multiple is described as expensive relative to the broader European personal products sector average of 17.3x, and it also sits above the estimated fair P/E of 19.9x that our fair ratio work points to as a level the market could move towards if sentiment cools or earnings delivery simply tracks forecasts.
Explore the SWS fair ratio for Interparfums.
Result: Price-to-Earnings of 21.2x (OVERVALUED)
Still, this balance can flip quickly if fragrance demand cools in key regions like North America, or if Interparfums faces pressure on licensing agreements.
Find out about the key risks to this Interparfums narrative.
Another view on Interparfums’ value
The P/E suggests Interparfums trades a little rich, yet our DCF model points in the opposite direction. On that framework, the current price of €28.78 sits around 21% below an estimated future cash flow value of €36.38, which frames the recent rerating as potentially more than just optimism.
This kind of gap can close in more than one way. Do you treat it as a margin of safety, or as a signal to question every line in the cash flow assumptions that produced it?
Look into how the SWS DCF model arrives at its fair value.
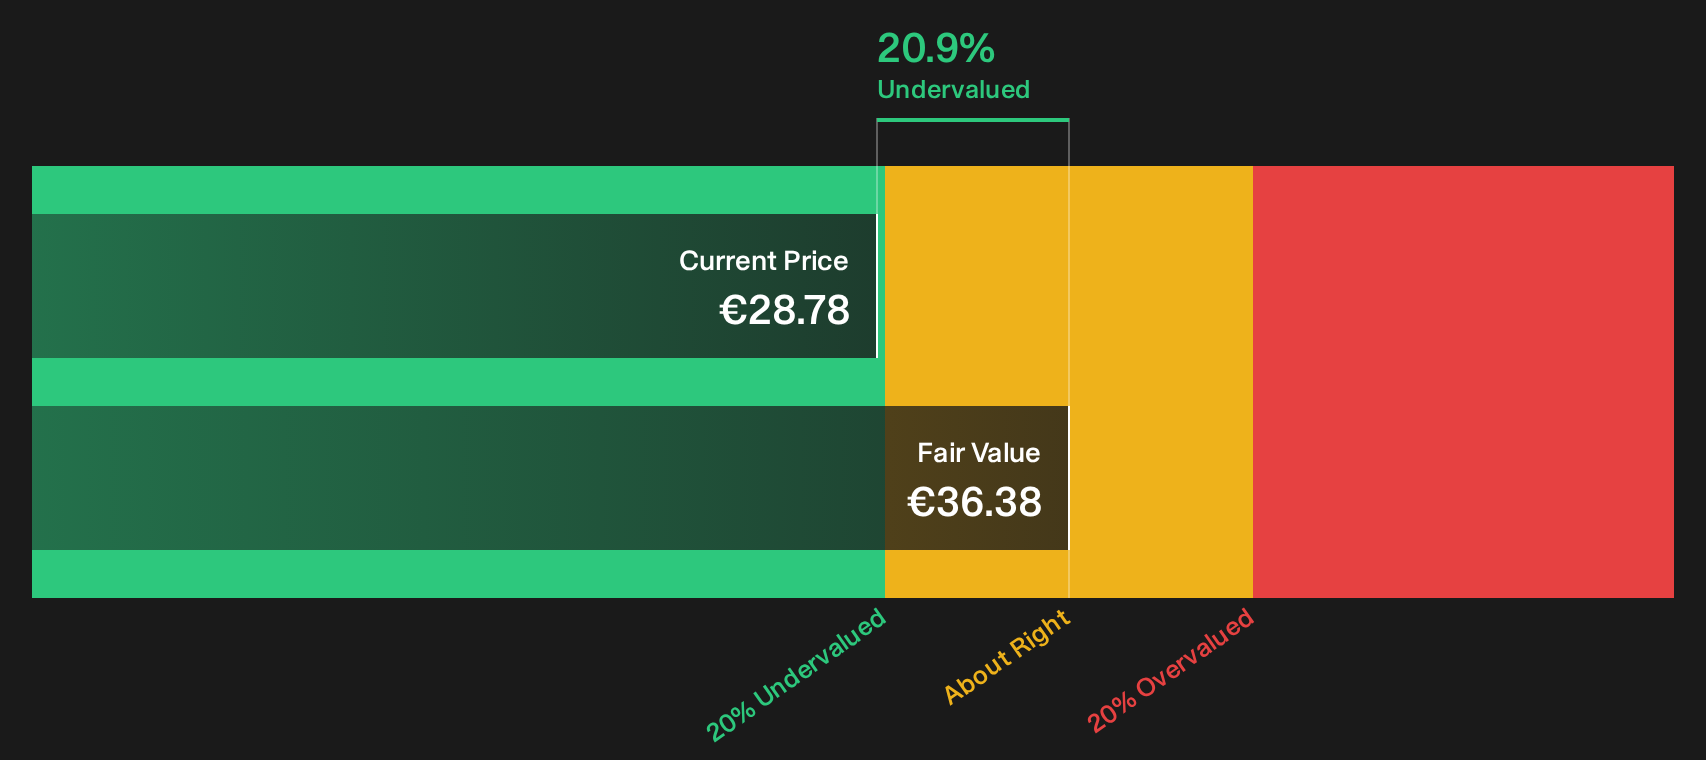
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Interparfums for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 188 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Interparfums story so far. If you want to move quickly and decide where you stand, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Interparfums?
Interparfums may already be on your radar, but building real confidence means lining it up against fresh ideas that could fit your goals even better.
- Target potential value plays early by comparing Interparfums against a curated pool of 188 high quality undervalued stocks that already combine strong fundamentals with appealing price tags.
- Prioritise staying power in tougher periods and weigh Interparfums beside a list of solid balance sheet and fundamentals (194 results) so you can focus on businesses built to endure.
- Hunt for tomorrow's potential standouts by scanning a focused 619 high quality undiscovered gems before the wider market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com