


Talon Metals (TSX:TLO) Stock Looks Above Fair Value After Record Tamarack Drilling
Talon Metals has been on a strong multi year run, and the latest drilling headlines now put a simple question in front of you as an investor: is the current share price properly supported by the sales the business is generating today and those it may be able to book from its projects?
- Over roughly three years, Talon Metals has delivered a share price gain of about 211%, which puts a lot of weight on whether its revenue base can carry that kind of move.
- Record high grade drilling at the Tamarack project and the decision to use the Humboldt Mill can shift expectations for future nickel related sales and potentially reshape when the market thinks meaningful revenue might arrive.
- There is a second opinion on Talon Metals worth weighing. See what analysts think Talon Metals's shares could be worth.
The stock's next move may depend on whether Talon Metals' current market value lines up with what its sales can reasonably justify.
If you want more context around Talon Metals' run and the current nickel story, consider a focused screen of 28 best rare earth metal stocks.
Has Talon Metals Run Too Far on Sales?
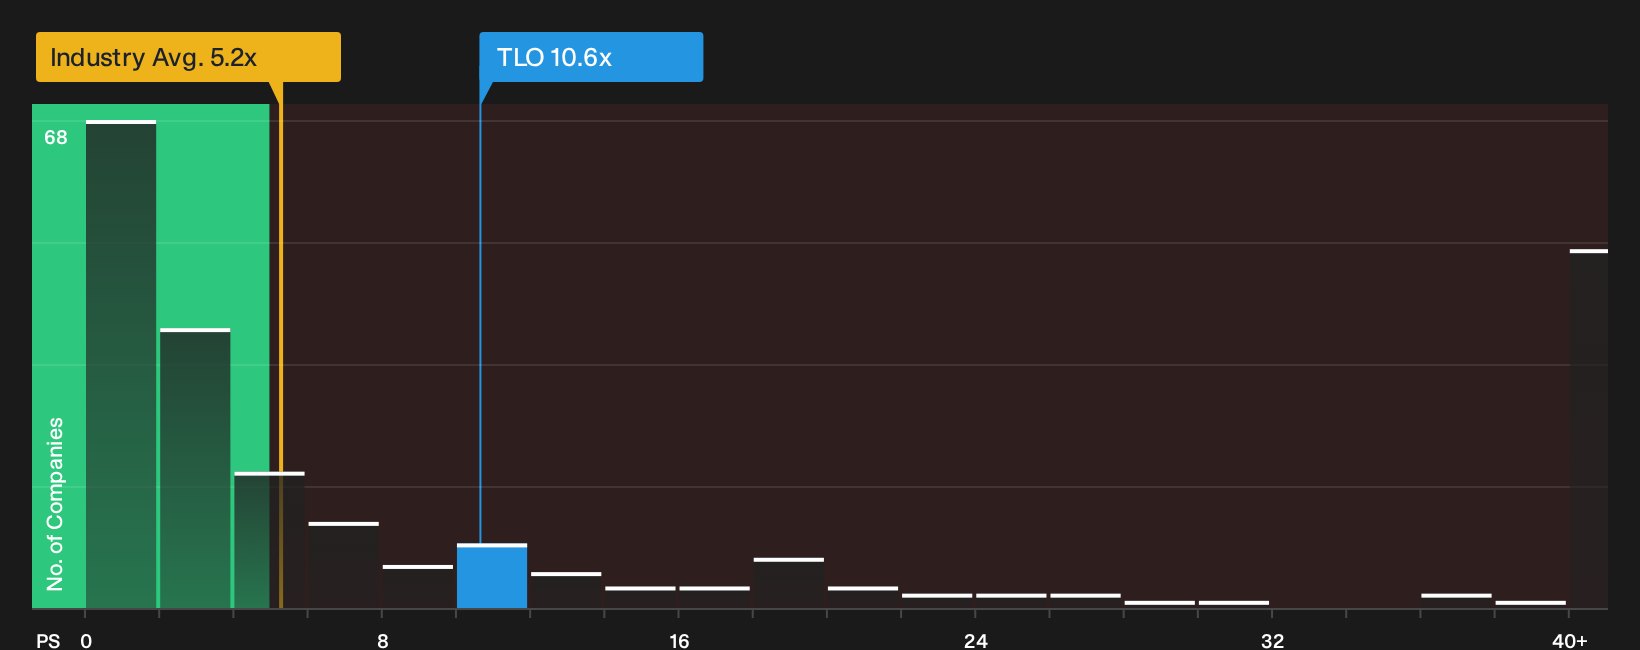
P/S is a cleaner yardstick for Talon Metals because the business is still working through heavy project spending and loss making free cash flow. On this measure, the stock trades on about 10.6x sales, compared with roughly 5.2x for the wider Metals and Mining group and about 6.7x for closer peers. Those marks point to investors paying a clear premium for each dollar of current revenue.
Because of recent excitement around record drilling results at Tamarack and the Humboldt Mill decision, the current P/S multiple still prices Talon Metals well above the level suggested by a more tailored fair value model that already incorporates its risk profile and sector context. The model is effectively flagging that the share price screens as very expensive on this framework rather than offering a precise target. Anyone looking at TSX:TLO therefore needs to decide whether the exploration and project story can justify that kind of revenue multiple. Explore the numbers behind Talon Metals's P/S valuation.
The Talon Metals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Talon Metals valuation question leaves off, by setting out what kind of future growth, margins and earnings profile would need to unfold for the stock to be worth materially more or materially less than it is today on the market. Each scenario ties a specific fair value to a clear storyline about Talon Metals' potential catalysts and risks, so you can watch over time which version seems to be taking shape on the Community page.
A written, number driven Narrative on Talon Metals' valuation gives you a clear way to test whether the current share price still lines up with the revenue profile that might come from Tamarack drilling results and the Humboldt Mill plan. It also creates a simple yardstick you can revisit as new data on the ore body, the Eagle Mine and the regulatory process feeds through into Talon Metals' actual sales and cash generation.
Share your own Narrative for Talon Metals and set out the assumptions behind your valuation.
Before weighing Talon Metals purely on numbers, there is one more piece to check
The people steering Talon Metals and the way they are rewarded can tilt risk and reward in ways a ratio never captures, so it is worth seeing how that picture looks before you act. See who runs Talon Metals and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com