


What Is Driving Attention Around Intact Financial (TSX:IFC) Today?
Intact Financial (TSX:IFC) is coming off a tough second quarter with heavier weather related catastrophe and large losses, yet it still reported profitability and ongoing premium growth that kept book value and return on equity moving higher.
Recent moves show that momentum in Intact Financial’s share price has cooled in the short term, with the 90 day share price return down 6.23% and the year to date share price return down 8.52%. However, the 3 year total shareholder return of 38.14% points to a much stronger longer run picture.
Scan other insurers that have shown similar resilience to Intact Financial in periods of heavier claims by checking the hand picked 1 resilient stocks with low risk scores that prioritize balance sheet strength and controlled risk profiles.
Bulls point to Intact Financial’s resilient profits, rising book value and long dividend record. Bears focus on weather exposure and a cooled share price. Which side does the current valuation actually support next?
Most Popular Narrative: 19% Undervalued
On the most widely followed narrative, Intact Financial screens as undervalued, with a fair value of CA$320.54 against a last close of CA$260.89. This puts the focus squarely on how future earnings power is being framed.
Significant premium growth in personal auto and property, driven by both rate actions and increased units, combined with persistent hard market conditions fueled by more frequent climate-related weather events, position Intact to sustain strong top-line growth and market share gains, directly benefiting future revenue.
Ongoing expansion into U.S. and European markets, as well as new product verticals, supports continued geographic and product diversification, reducing reliance on the Canadian market and helping to stabilize and grow earnings.
See why 40 investors see Intact Financial as 19% undervalued.
Result: Fair Value of CA$320.54 (UNDERVALUED)
Still, the narrative can break if climate related catastrophe losses stay unusually high or if regulatory constraints, such as Alberta auto rate caps, keep pressure on profitability.
Find out about the key risks to this Intact Financial narrative.
Another View On Intact Financial’s Valuation
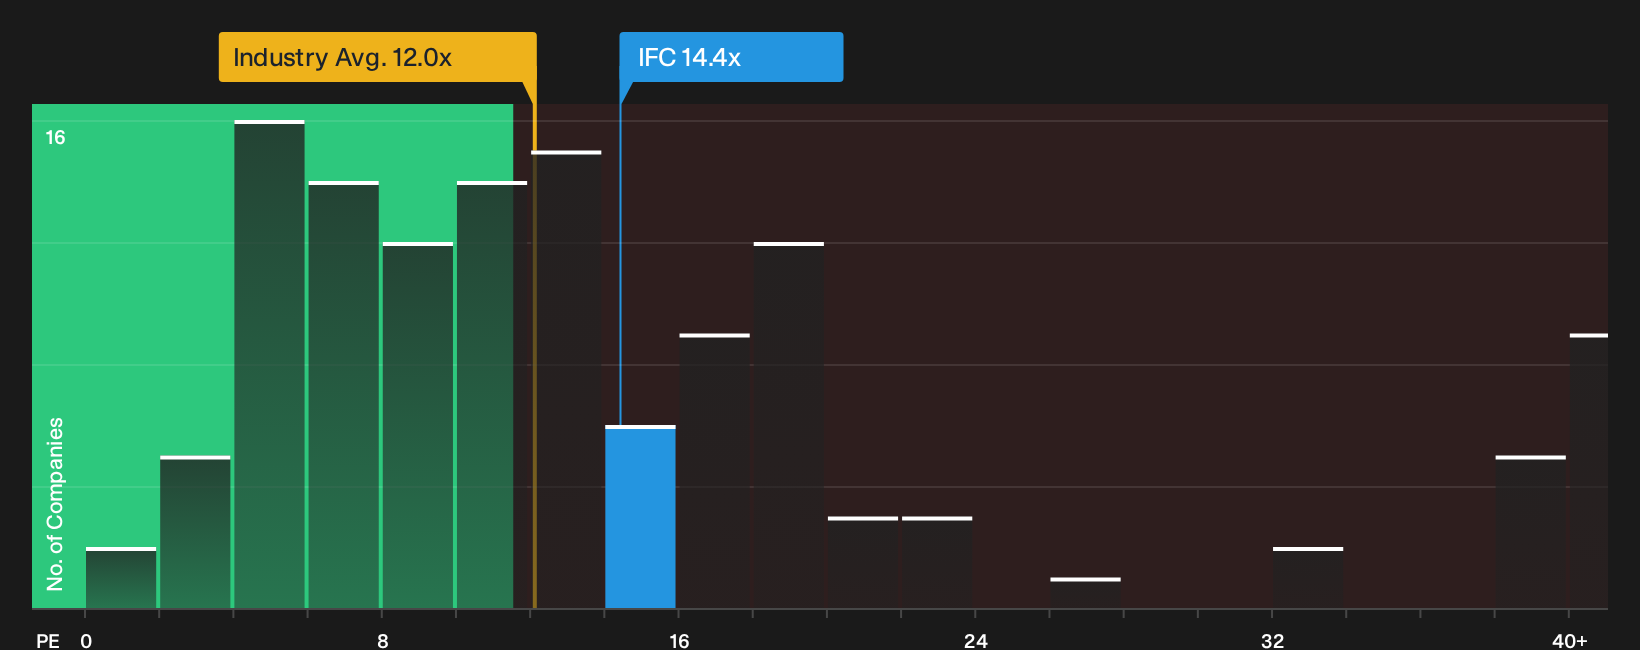
Analysts may see Intact Financial as 19% undervalued on fair value, but the simple earnings multiple paints a cooler picture. The stock trades on a P/E of 14.4x, while the fair ratio sits at 13x and the North American insurance group averages 12.1x. That leans closer to fully priced than bargain territory, so which signal do you trust more?
Investors who lean on earnings multiples rather than fair value models may want to see what the numbers imply for risk and upside across peers, then judge whether Intact Financial’s current P/E leaves enough room for comfort or future repricing pressure. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Intact Financial can feel messy, so move quickly from headline narratives to the underlying data and decide where you stand. To weigh the full picture yourself, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Intact Financial?
If the mixed signals around Intact Financial caught your attention, use that momentum and widen your watchlist before the next round of catalysts reshapes the opportunity set.
- Target potential mispricing by scanning a curated pool of companies that our filters flag as quality opportunities with 4 high quality undervalued stocks.
- Focus on income by filtering for reliable high yield payouts using the carefully constructed set of 2 dividend fortresses.
- Prioritize resilience by zeroing in on businesses screened for robust finances through the list of solid balance sheet and fundamentals (6 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com