


Chime Financial (CHYM) Opens Manhattan Hub As Investors Weigh Its Valuation
Chime Financial (CHYM) just opened an 84,000 square foot East Coast hub at 122 Fifth Avenue in Manhattan’s Flatiron District. The company is expanding its New York presence in what it identifies as its largest metropolitan market.
Chime Financial’s new Manhattan hub lands after a sharp run in the shares, with a 90 day share price return of 77.56% and a 1 year total shareholder return of 33.89%. Recent sessions have cooled that momentum a little, with the 1 day share price return down 7.02% and the 7 day share price return down 4.35% as investors weigh the New York expansion alongside fresh 2026 revenue guidance.
Scan how Chime Financial’s New York expansion fits into a wider fintech story by comparing it with list of solid balance sheet and fundamentals (22 results) that could handle similar growth ambitions.
Bulls see Chime Financial using its Manhattan hub and fresh 2026 guidance to justify a richer multiple. Bears point to recent share price volatility and ongoing losses. Which story do the current valuation markers support?
Most Popular Narrative: 9% Undervalued
Chime Financial closed at $31.25, while the most followed narrative pegs fair value at $34.20, leaving a modest valuation gap for investors to weigh against its East Coast expansion and product pipeline.
The ongoing shift toward digital, app based banking for everyday needs aligns directly with Chime's 9.1 million active members and high brand awareness. This can support member growth and higher payments revenue as more consumers choose online over branch based banking.
See why 3 investors see Chime Financial as 9% undervalued.
Result: Fair Value of $34.20 (UNDERVALUED)
Still, the Chime Financial story can change quickly if competition squeezes interchange revenue or if credit products like MyPay see loss rates drift higher.
Find out about the key risks to this Chime Financial narrative.
Another View on Chime Financial’s Valuation
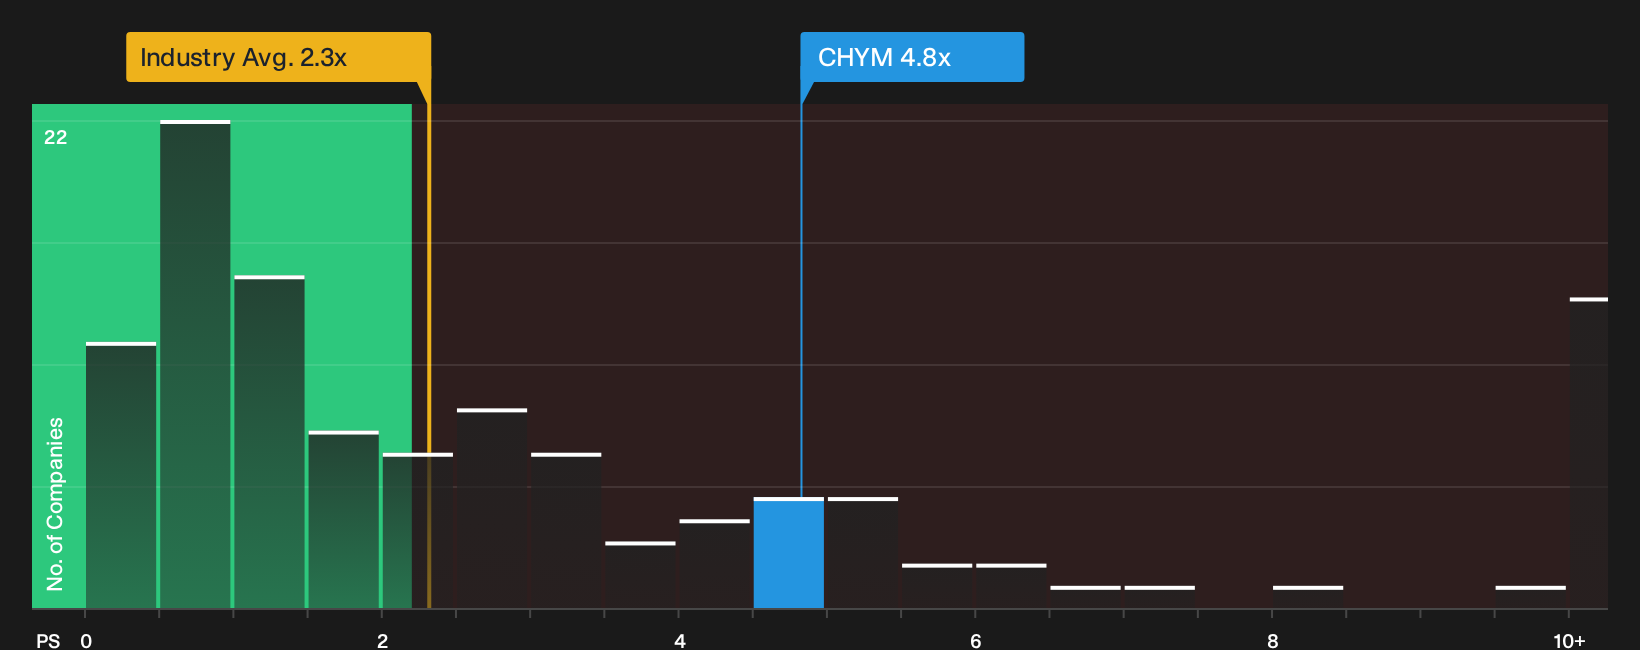
On the first pass, Chime Financial looks modestly undervalued relative to the $34.20 fair value estimate. A different lens using the P/S ratio tells a tougher story. The stock trades at 4.8x sales, which is richer than both the US Diversified Financial industry at 2.4x and peers at 4.1x. The fair ratio is also 4.1x, so if the market drifts toward that level, investors would be paying today for a valuation that already embeds a lot of execution success. Is that premium something you are comfortable underwriting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling conflicted about Chime Financial after weighing the fresh guidance, valuation gap and New York build out? Use the full picture of risks and upside potential to move quickly and sharpen your own view with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Chime Financial?
Do not stop your research at Chime Financial. Broaden your watchlist now with fresh ideas that match your goals before the next wave of opportunities moves ahead without you.
- Hunt for mispriced quality by scanning 33 high quality undervalued stocks that combine solid fundamentals with what could be attractive entry points.
- Strengthen your income mix by lining up 6 dividend fortresses that aim to pair higher yields with resilience when markets turn choppy.
- Dial down portfolio stress by reviewing 11 resilient stocks with low risk scores built on sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com