


What Comfort Systems USA Stock Earnings Upgrades Mean For Shareholders
- Comfort Systems USA is attracting attention after analysts highlighted strong earnings and cash flow characteristics, supported by positive revisions to earnings estimates and a high Zacks growth rating.
- The more interesting angle is how management’s focus on data center and service work aligns with this analyst optimism, tying near term sentiment to longer term demand in complex, recurring projects.
- This article examines how Comfort Systems USA's investment narrative is influenced by these earnings upgrades and growth focused analyst views.
Scan other contractors riding similar data center and cash flow themes by reviewing our curated list of 38 power grid technology and infrastructure stocks before you decide how Comfort Systems USA fits into your watchlist.
Comfort Systems USA Investment Narrative Recap
To own Comfort Systems USA, you need to buy into a construction and services platform that leans heavily on complex technology projects and a growing recurring service base. The big swing factor in the near term is how efficiently that record backlog converts into revenue and cash, particularly in data center and other high spec work.
The most important near term risk is concentration in technology led builds at the same time labor, materials and competition all create pressure on execution. Recent analyst enthusiasm around earnings and cash flow does not change that core setup much. It instead raises the bar on delivery and consistency.
The recent focus on Comfort Systems USA’s Zacks growth rating and earnings estimate revisions ties directly to that operational story. Positive revisions hinge on management continuing to win and execute large, complex projects while also scaling higher margin service revenue and modular offerings efficiently.
What matters from here is whether the company can work through its US$8.1b backlog with tight cost control, keep gross margins supported despite labor and input cost risks, and grow service revenue from its current US$1.2b base. Analyst optimism is a secondary factor unless execution on those operational levers stays on track.
Comfort Systems USA's analyst narrative points to revenues of US$19.6b and earnings of US$2.9b by 2029, based on forecast yearly revenue growth of 20.3% and an earnings increase of about US$1.5b from current earnings of US$1.4b.
Uncover why Comfort Systems USA's fair value indicates a 38% potential upside to its current price, a gap that could close quickly.
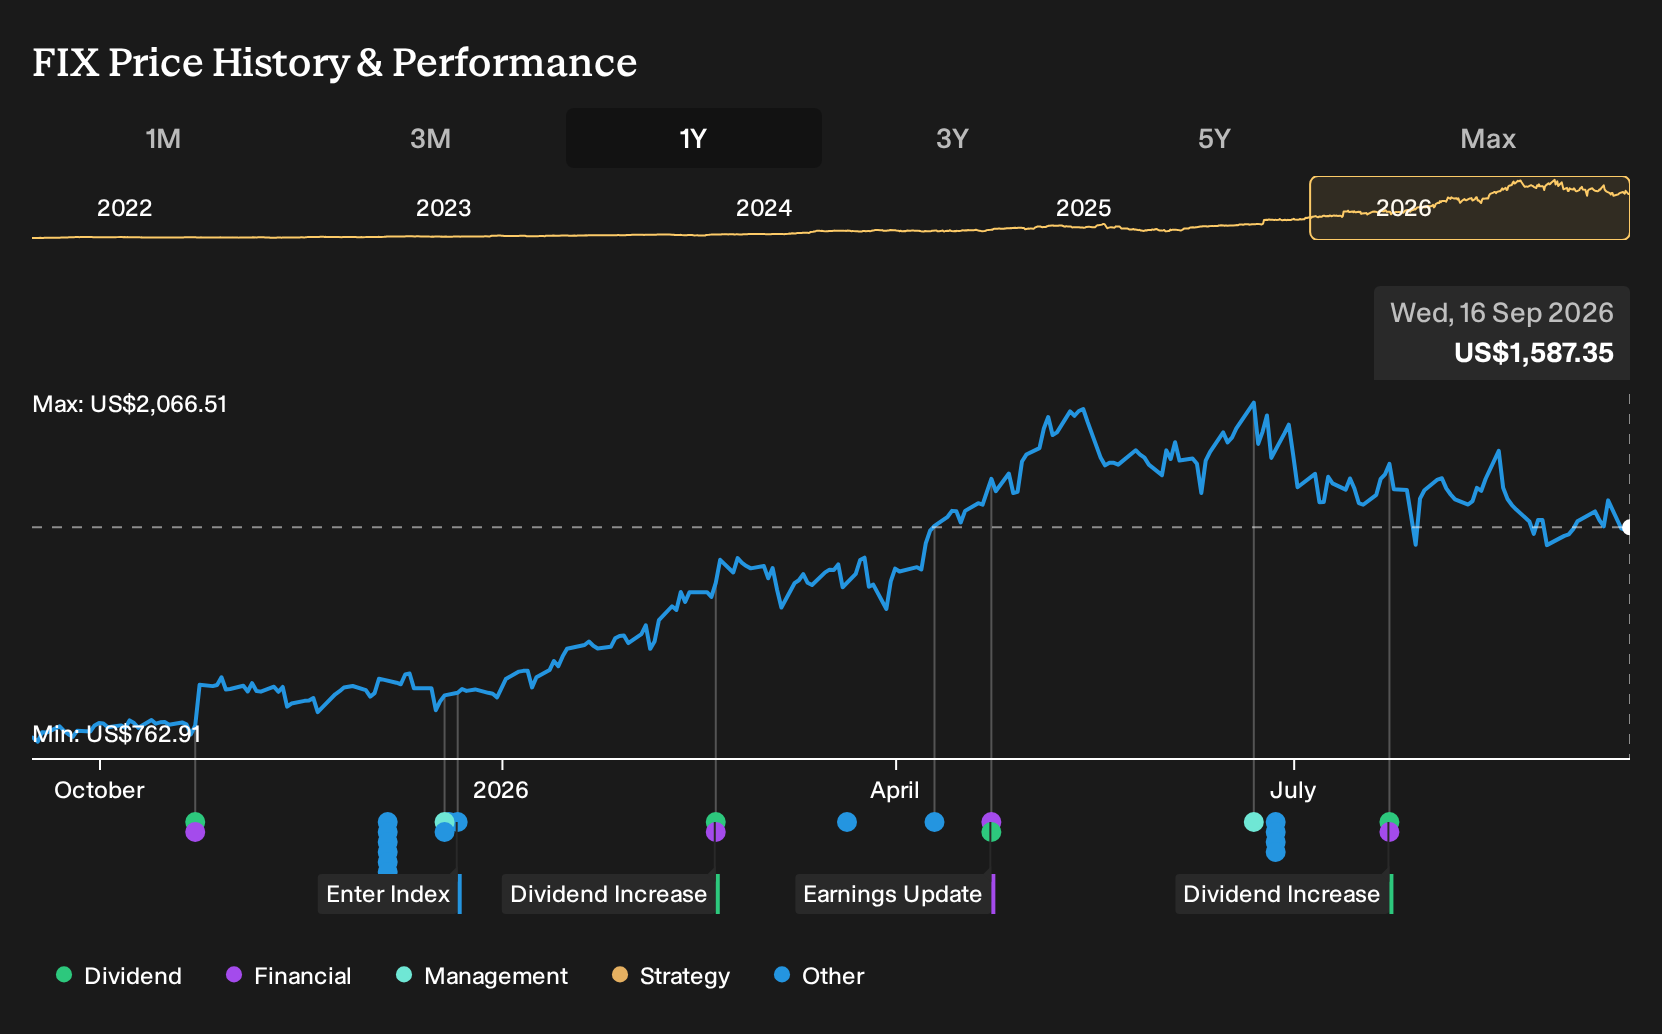
Exploring Other Perspectives
For Comfort Systems USA, the bullish twist in the story is the optimistic view on data center demand. The most upbeat analysts were penciling in about US$20.1b of revenue and US$3.0b of earnings by 2029 before this news, which is far above the more cautious US$19.6b and US$2.9b path. That gap shows how widely opinions can differ, so treat this update as a chance to explore both the consensus and the more aggressive outlooks for yourself.
Explore 5 other Comfort Systems USA fair value estimates, including one that suggests as much as 67% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Comfort Systems USA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Comfort Systems USA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comfort Systems USA's overall financial health at a glance.
Looking For More Comfort Systems USA Investment Ideas?
If Comfort Systems USA has sharpened your thinking about earnings quality, cash flow and balance sheets, use that momentum to widen your watchlist with a structured search across other stocks.
- If you want high quality businesses that the market may be overlooking, scan our curated group of 16 high quality undiscovered gems and see which ones match your criteria.
- If capital preservation sits high on your priority list, filter for calmer rides by focusing on 11 resilient stocks with low risk scores that combine resilience with measured expectations.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (22 results) and look for companies where debt levels and fundamentals line up with your comfort zone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com