


Rush Enterprises (RUSH.A) Following Its MCT Joint Venture, Does The Valuation Story Change?
Rush Enterprises (RUSH.A) just closed a 50-50 joint venture with MCT Companies, bringing Carrier Transicold refrigeration dealerships and mobile service locations into its commercial vehicle solutions portfolio.
Recent trading has been choppy for Rush Enterprises, with the share price down about 10.5% over the last month, even after a roughly 4.9% gain across the past quarter. However, the year-to-date share price return of 35.9%, alongside a 1-year total shareholder return of 33.4% and a 5-year total shareholder return of 171.1%, points to longer term momentum that frames this new refrigeration joint venture as another factor investors may weigh when reassessing both growth potential and risk around the current US$49.01 price.
Scan beyond Rush Enterprises and this refrigeration joint venture to find other commercial vehicle and industrial players showing strong momentum on our hand picked 33 high quality undervalued stocks.
Rush Enterprises now trades around US$49.01 while analyst targets and intrinsic estimates sit higher on average. The next step for valuation work is to determine how wide that gap really is.
Most Popular Narrative: 18% Undervalued
On the most followed view of Rush Enterprises, a fair value of about $59.67 sits well above the recent $49.01 close. This puts the focus on whether earnings power from services can support that gap.
Rush is leveraging recurring revenue growth through the ongoing expansion of its parts/service business (including proprietary solutions like RushCare) and is capitalizing on technician retention improvements, which is expected to enhance customer stickiness and promote better net margins through more stable, higher-margin revenue streams. Industry-wide dealer consolidation and increased truck complexity continue to favor national scale operators like Rush, allowing the company to capture greater market share and purchasing power, supporting long-term revenue growth and earnings leverage as operational efficiencies scale.
See why 3 investors see Rush Enterprises as 18% undervalued.
Result: Fair Value of $59.67 (UNDERVALUED)
Still, if freight demand stays weak or regulatory uncertainty around emissions drags on longer than expected, the Rush Enterprises service cushion could prove thinner than bulls assume.
Find out about the key risks to this Rush Enterprises narrative.
Another View: Rush Enterprises Through The P/E Lens
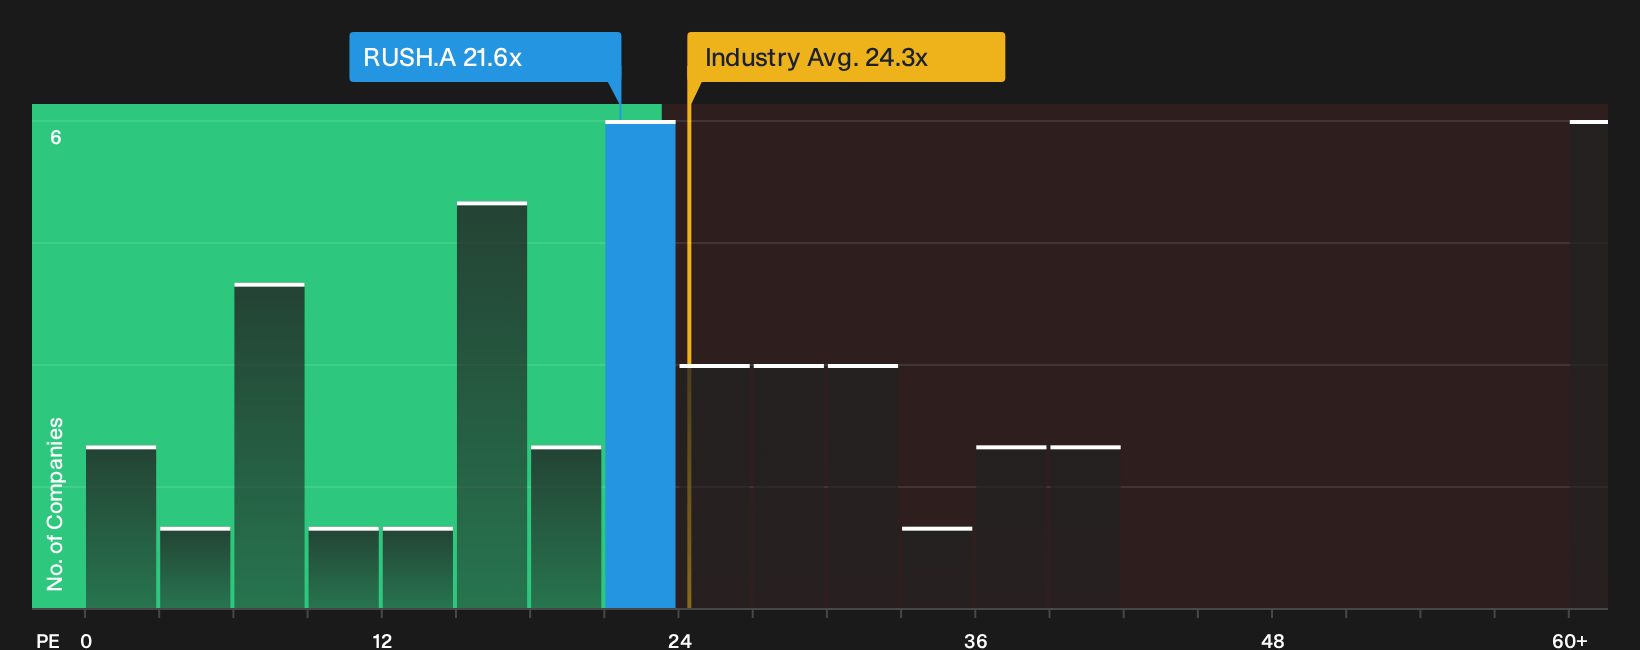
There is a very different message when valuation for Rush Enterprises is viewed through the P/E ratio instead of fair value models. At about 21.6x earnings, the stock trades almost exactly in line with its fair ratio of 21.5x and well below peer levels near 66x. This points to limited multiple upside but also less extreme downside if sentiment cools.
For investors weighing this earnings based view against richer fair value estimates, the key question is whether future results justify paying much more than a fairly priced business today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Rush Enterprises so far. If you want a clear view, review the data directly and consider the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Rush Enterprises?
Do not stop your research with Rush Enterprises. Broaden your watchlist using focused stock ideas that line up with how you prefer to balance risk, quality, and income.
- Target potential bargains with solid fundamentals by scanning our hand picked 33 high quality undervalued stocks that might warrant a closer look before the crowd catches on.
- Prioritize resilience and sleep better at night by reviewing a 11 resilient stocks with low risk scores that highlights businesses with steadier risk profiles and sturdier financial footing.
- Hunt for future leaders early by checking a 16 high quality undiscovered gems that surfaces quality companies still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com