


Stantec And 2 Canadian Undervalued Stocks To Watch
Trump’s threat of very heavy tariffs on the European Union if it deepens ties with Canada has pushed trade risk back onto the radar for Canadian investors. When headlines lean toward tariff fights, solid Canadian companies with strong cash generation and conservative balance sheets can quietly slip to attractive prices. This article highlights three such high quality opportunities that currently look mispriced by the market.
The three stocks below are just a starting sample, and the same screen surfaced 1 more company with an equally compelling quality and value story that is not covered here.
If you want to identify and analyze all of them side by side, head straight to the High Quality Undervalued Stocks screener.
Stantec (TSX:STN)
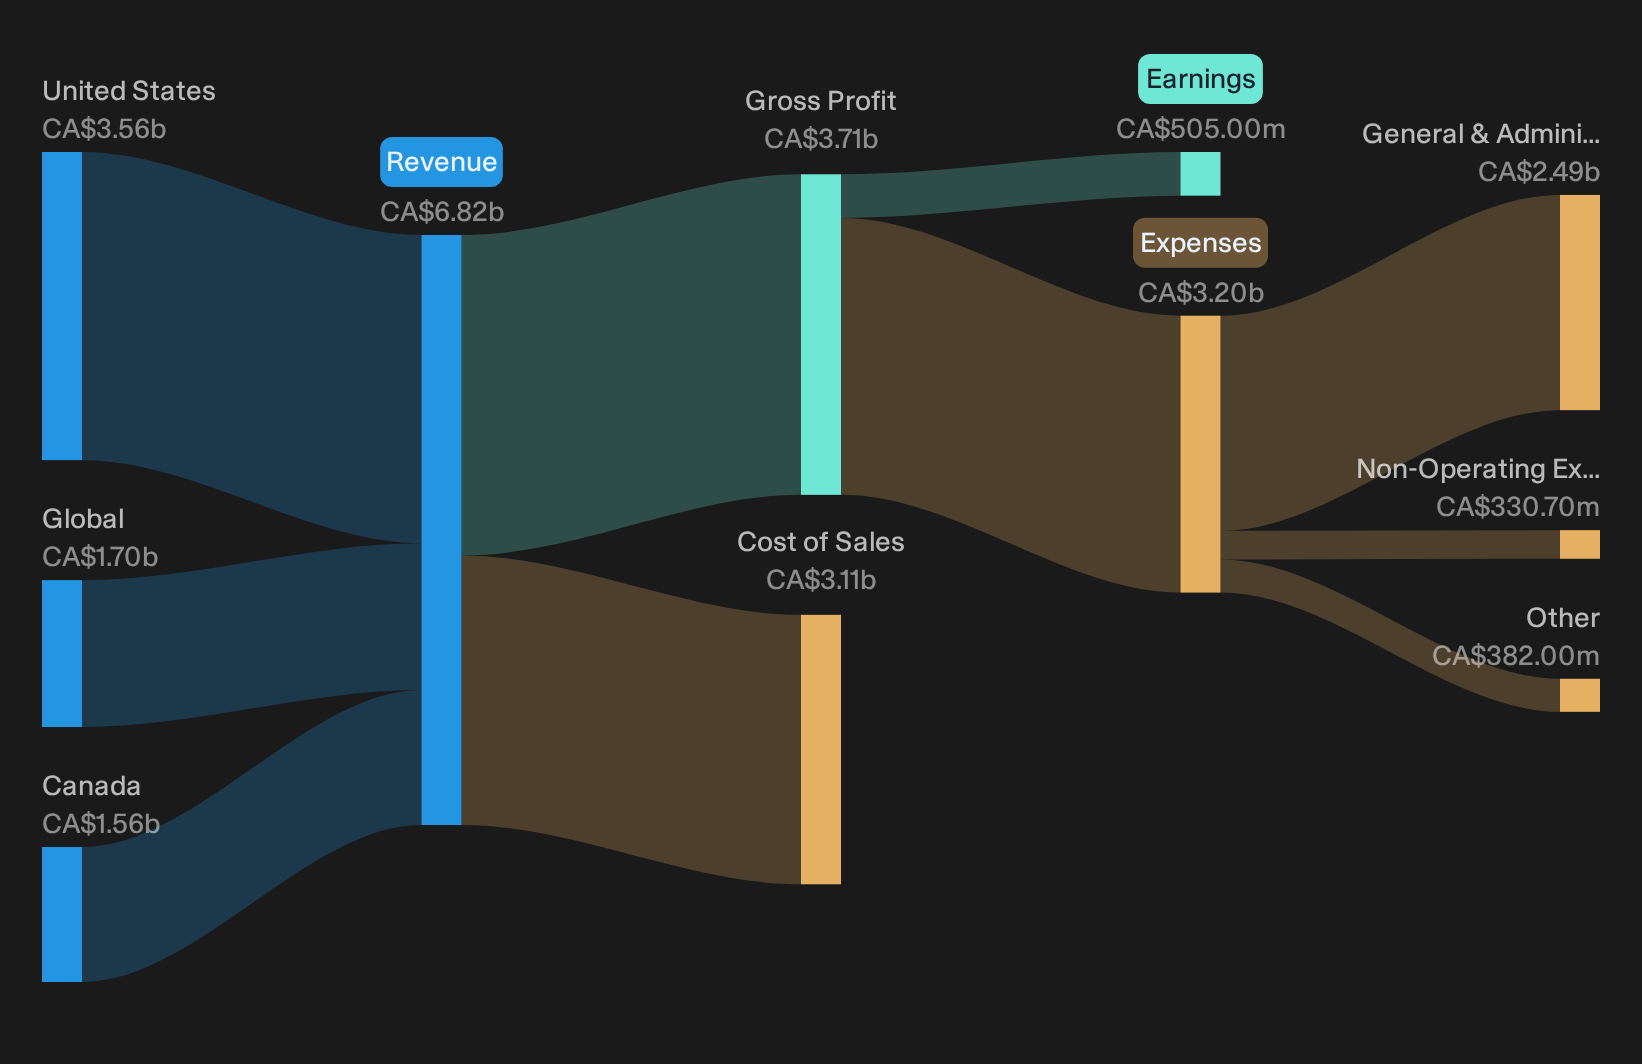
Overview: Stantec is a global engineering and consulting firm that plans, designs, and manages long-term infrastructure and water projects for governments and utilities.
Operations: The business generates most of its CA$6.8 billion revenue from the United States at CA$3.6 billion, with Canada and global operations contributing the rest.
Market Cap: CA$11.1 billion
For the High Quality Undervalued Stocks theme, Stantec matters because recurring infrastructure and water contracts can translate project backlogs into steady cash flows and balance-sheet strength.
"Demand for infrastructure upgrades, water/wastewater treatment, energy transition, and climate adaptation projects remains exceptionally strong globally, with double-digit organic growth and a $7.9 billion backlog, which the company indicates is positioning it for sustained revenue expansion in line with multi-decade trends toward urbanization and aging infrastructure."
What happens to Stantec’s margin story if a single unseen pressure changes how efficiently those higher-value consulting projects convert into earnings.
That margin pressure question is exactly what the full narrative for Stantec unpacks, showing how Stantec’s backlog, pricing power and capital choices could reshape the risk reward profile.
Celestica (TSX:CLS)
Overview: Celestica provides hardware platforms and end to end supply chain services for hyperscalers, cloud providers, and diversified industrial customers worldwide.
Operations: Celestica generates US$3.3b from Advanced Technology Solutions and US$12.3b from Connectivity & Cloud Solutions, with the latter driving most activity.
Market Cap: CA$50.6 billion
Celestica fits the High Quality Undervalued Stocks theme through its rack scale AI hardware platforms and supply chain services that plug directly into hyperscaler and cloud build outs, which can turn long design cycles into recurring, high-value programs.
"Accelerated demand for advanced networking and AI infrastructure by hyperscaler customers is driving rapid growth in Celestica's CCS segment, with multiple new 800G and upcoming 1.6T program ramps, supporting revenue expansion and greater operating leverage going forward."
What happens to Celestica’s cash generation and earnings quality if a single concentrated customer decision shifts the rhythm of that hyperscaler demand.
When that concentration risk matters most, the full narrative for Celestica shows how accelerating AI hardware ramps could still reshape Celestica’s cash profile and re-rate the story.

Triple Flag Precious Metals (TSX:TFPM)
Overview: Triple Flag Precious Metals runs a precious metals streaming and royalty model that converts contracted mine output into recurring, low-capex cash flows.
Operations: Triple Flag Precious Metals reports $488.6 million from gold and other precious metals streams and royalties, mainly across Peru, Australia, other Latin America, and North America.
Market Cap: CA$9.3 billion
Triple Flag Precious Metals slots neatly into this high quality undervalued list because its streaming contracts aim to turn long life mines into relatively steady cash generation with limited ongoing spending, which is exactly the kind of profile this screen is built to surface.
"Multiple new royalty and streaming investments, including the Arthur Gold project in Nevada, Arcata and Azuca silver mines in Peru, and Johnson Camp copper mine in Arizona, are expected to deliver first revenues in the second half of 2025, underpinning forward growth in revenue and operating cash flow as these assets ramp up."
What happens to that clean cash flow story if a single shift in funding conditions changes how comfortably Triple Flag Precious Metals carries its obligations.
If that funding shift is what worries you, the full narrative for Triple Flag Precious Metals shows how Triple Flag Precious Metals could still accelerate or stall as new streams switch on.

Curious About What You Might Be Missing?
Fresh ideas can move fast. Some gain momentum quietly, while others are caught before a breakout or start dropping once the crowd piles in. Scan these under the radar for now opportunities and get in early.
- Spot companies quietly building strength before momentum catches the headlines by running the 9 high quality undiscovered gems while valuations and expectations still look reasonable.
- Track where real cash generation meets durable yield using the 2 dividend fortresses so income focused ideas do not fly past unnoticed.
- Follow structural demand in critical materials with the 29 top copper producer stocks and see which producers could benefit most while pricing shifts still matter.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com