


Should Conference Appearance Require Action From Matson (MATX) Investors?
- Matson recently presented at Morgan Stanley's 14th Annual Laguna Conference in Laguna Beach, where it outlined how its ocean transport and logistics operations are positioned across key Pacific trade routes.
- Management focus on Vietnam-origin shipping volumes and expedited transpacific services highlighted how shifting supply chains are feeding into Matson's core freight demand and service mix.
- We will now examine how Matson's investment narrative could be influenced by its conference messaging around Vietnam growth and supply chains.
Matson Investment Narrative Recap
To own Matson, you need to believe its mix of protected U.S. trade lanes and faster transpacific routes, including Vietnam, can keep filling ships consistently even as global trade patterns stay choppy. The short-term swing factor is how resilient Vietnam and China express volumes are if freight pricing softens or competitors add capacity into the same corridors.
The biggest risk sits in that concentration. Matson leans heavily on a few lanes while also committing to ongoing vessel spending, which can strain cash if rates reset lower. The Laguna conference messaging helps clarify management’s read on these trade flows but does not fundamentally change that risk profile.
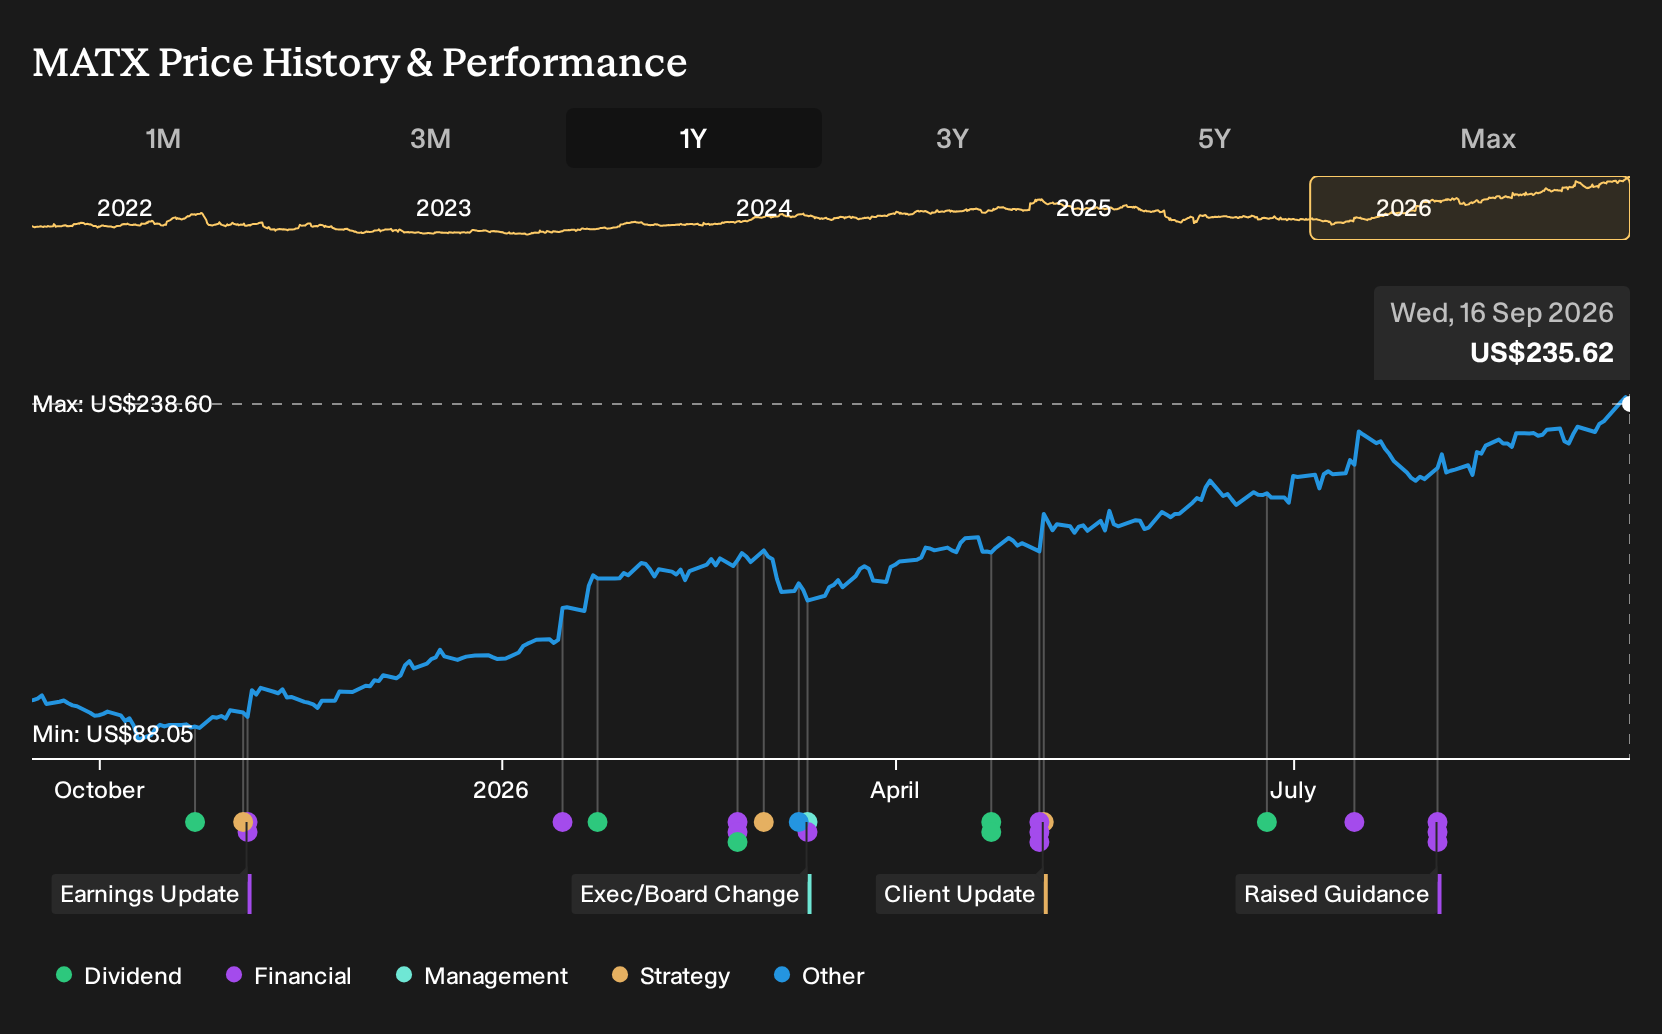
The most relevant datapoint around this event is Matson’s strong share price run into the Laguna appearance, with a year-to-date gain above 90% and a transportation sector beat. That move indicates expectations are already high as management emphasizes Vietnam volumes, express services and the broader freight portfolio.
For you, the question is whether the operational story can keep matching that enthusiasm. Analyst estimates have turned more positive, with full-year earnings expectations raised and a Zacks Rank of #1, yet the core drivers remain the same. Execution on vessel spending, pricing in key lanes and competition across expedited transpacific routes still anchor the real catalysts from here.
Matson's narrative projects US$4.0b revenue and US$496.8m earnings by 2029. That implies 5.1% yearly revenue growth and an earnings increase of about US$33m from current earnings of US$463.8m.
Uncover why Matson's fair value indicates an 11% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One optimistic twist in the alternate view is how much weight some analysts put on Matson’s Vietnam and wider Southeast Asia capacity additions. The most bullish group was modeling US$4.0b of revenue and US$528.7m of earnings by 2029, versus about US$496.8m in the baseline, even before this Laguna conference update. You can treat today’s Vietnam messaging as a fresh input and decide whether those higher forecasts still feel realistic.
Explore 7 other Matson fair value estimates, including one that suggests an upside of as much as 206% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Matson research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Matson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Matson's overall financial health at a glance.
Looking for more investment ideas beyond Matson?
If Matson has sharpened your interest in how trade, balance sheets and pricing power fit together, it can be useful to line it up against other businesses with different strengths using the Simply Wall St Screener.
- For investors who want potential upside with a margin of safety, review a curated set of companies flagged as having room between price and fundamentals through the 33 high quality undervalued stocks.
- If capital preservation matters most to you, filter for businesses with sturdier finances and low risk scores using the 11 resilient stocks with low risk scores.
- When you want financial strength and quality together, scan a list of solid balance sheet and fundamentals (22 results) to see which businesses pair resilient balance sheets with consistent fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com