


3 Oil Stocks Retail Investors Are Watching As Supply Risks Return
Oil headlines are back on front pages, with Iran related risks, Gulf export disruptions, and Saudi pipeline outages all pulling crude and inflation expectations into the spotlight again. That kind of uncertainty can punish some energy stocks and reward others that are better positioned or better prepared. This article walks through three stocks exposed to this news backdrop and explains why each could be worth a closer look at this time.
The stocks covered below are only a small sample of what fits this theme, and the full screen surfaced 41 more global oil and gas producers with equally compelling narratives that are not discussed here. To go straight to the full opportunity set, analyze, filter, and identify your own highest conviction ideas using the Global Oil & Gas Producers screener.
Energean (LSE:ENOG)
Overview: Energean is a London based pure-play oil and gas explorer and producer focused on Mediterranean fields, with flagship offshore Israeli projects.
Operations: Energean generates about US$1.67b from oil and gas exploration and production, with roughly US$1.16b tied to Israeli operations and sales.
Market Cap: £1.46b
Energean appears in this global producers screen as a direct way to gain exposure to crude and gas price swings through a focused Mediterranean portfolio, rather than via a diversified energy conglomerate.
"Energean's ongoing expansion in the Mediterranean, with significant agreements in Israel, including $4 billion worth of gas contracts and a total contracted revenue of over $20 billion for the next 20 years, offers a reliable and predictable cash flow, which is expected to positively impact future revenue and earnings."
This raises a key question: what happens if a single assumption behind those long dated contracts shifts, especially around costs and future pricing power?
If that contract risk is front of mind, read the full narrative for Energean to see how Energean’s pricing power, capital plans, and regional exposure could be decoupling.

VAALCO Energy (EGY)
Overview: VAALCO Energy is an independent Houston based producer that acquires, develops, and operates oil and gas fields across West Africa and Canada.
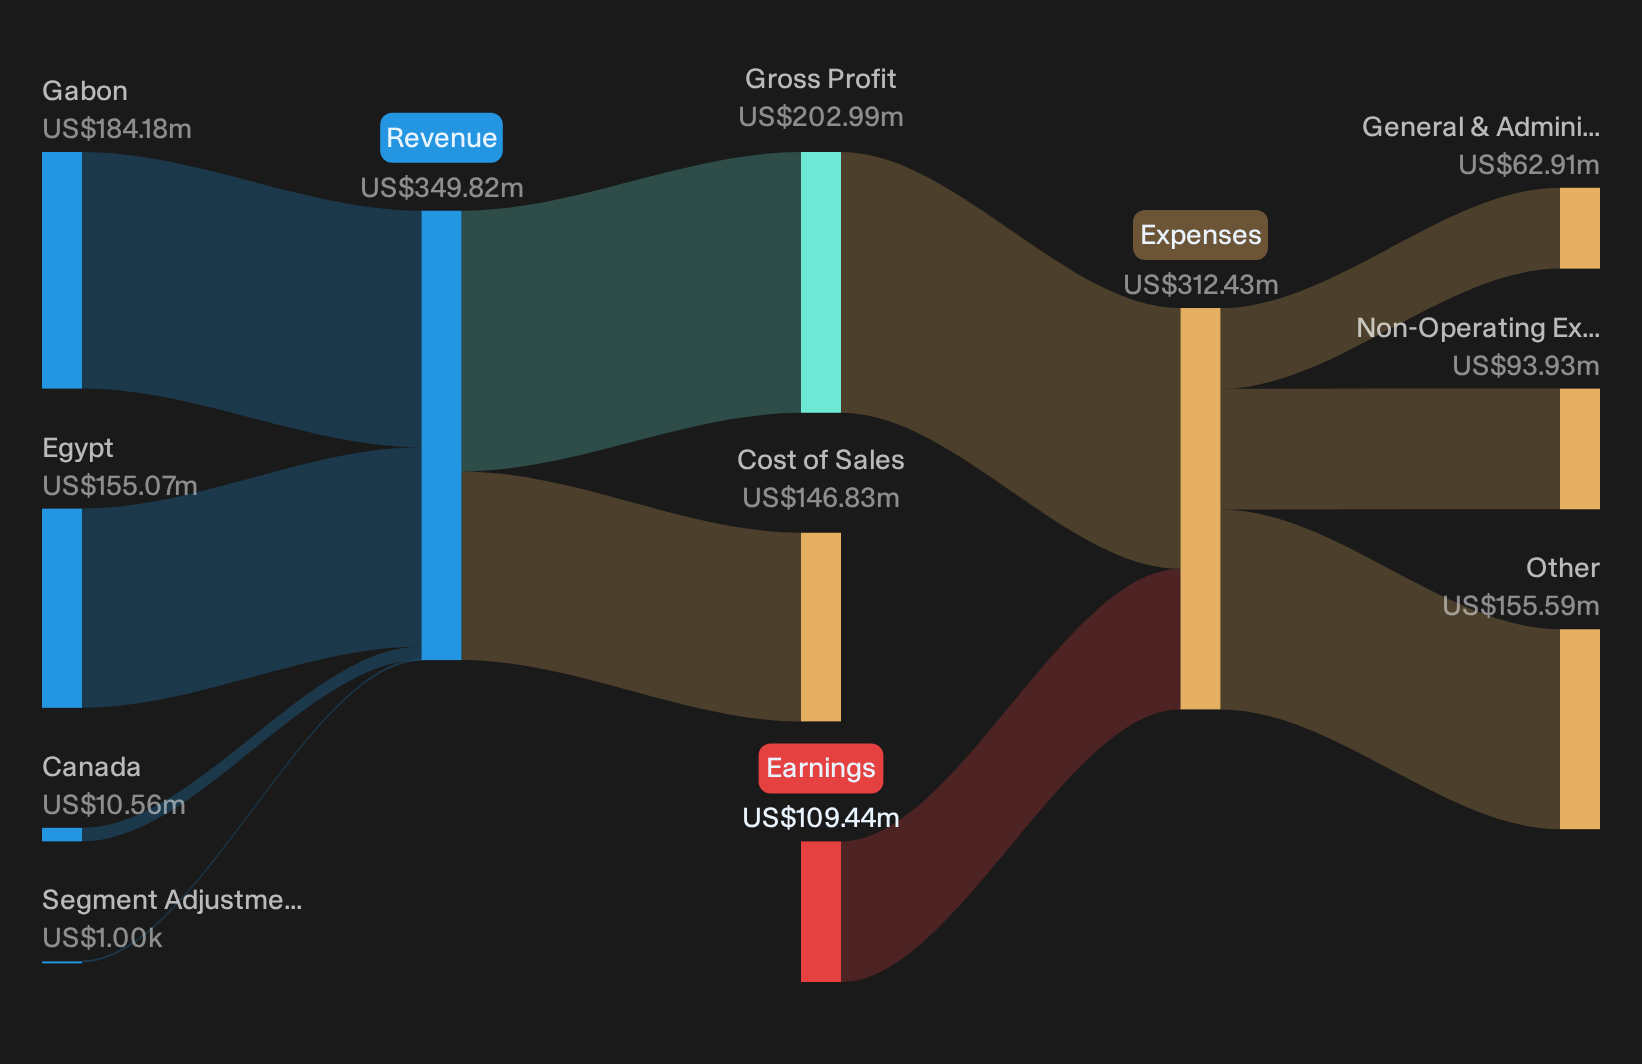
Operations: VAALCO generates about US$349.8 million from hydrocarbon exploration and production, mainly from Gabon and Egypt with a smaller Canadian contribution.
Market Cap: US$686 million
VAALCO Energy brings a different flavor to this Global Oil & Gas Producers screen, with offshore fields that are tied to Brent pricing and export routes that currently sit outside the Gulf chokepoints now dominating headlines.
"The anticipated restart and subsequent ramp-up of production in Côte d'Ivoire in 2026, following ahead-of-schedule FPSO refurbishment and a 10-year license extension, is likely to deliver a significant uplift in production volumes and revenues, benefiting from persistent global energy demand and the continued necessity of stable oil supplies."
What really matters for VAALCO Energy is how one less visible cost and funding pressure ultimately filters through to long run free cash flow.
That funding squeeze is where the story starts to get interesting, and the full narrative for VAALCO Energy digs into how VAALCO Energy’s capital choices could accelerate or stall that potential uplift.
Evolution Petroleum (EPM)
Overview: Evolution Petroleum is a Houston based energy producer that develops and owns onshore U.S. oil and gas fields. Its cash flows move directly with commodity prices.
Operations: Evolution Petroleum generates about US$83 million from oil and gas exploration and production, entirely from onshore assets in the United States.
Market Cap: US$145 million
Evolution Petroleum fits the Global Oil & Gas Producers theme as a straightforward onshore U.S. operator whose fortunes closely track crude pricing. This makes current geopolitical stress a powerful swing factor for both cash generation and dividend coverage.
"Mounting global decarbonization initiatives and accelerating regulatory action against fossil fuels threaten to erode long-term oil and gas demand and restrict Evolution Petroleum's access to capital, which would negatively impact revenue growth and could result in shrinking net margins as the company faces higher compliance costs and reduced pricing power for its hydrocarbons."
The real fulcrum for Evolution Petroleum is how one shift in long term policy and capital availability eventually filters through to shareholder payouts.
That pivot point is exactly what the full narrative for Evolution Petroleum unpacks, revealing how Evolution Petroleum’s policy risk, capital access, and payout potential could be quietly decoupling.

Curious To Explore Smart Alternatives?
Fresh opportunities can move from quiet to flying under the radar in days. Check these curated lists before the breakout gets caught by the crowd. Act now.
- Spot resilient cash generators with strong balance sheets before momentum picks up by scanning the curated list of solid balance sheet and fundamentals (10 results).
- Target income ideas that aim for durability and yield by working through a hand picked universe of 1 dividend fortresses.
- Pursue early stage growth angles beyond Energean, VAALCO Energy, and Evolution Petroleum by focusing on a tightly filtered group of 7 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com