


IDC: Global smart glasses shipments increased 35.3% year-on-year in the second quarter, and audio and photography glasses became the main growth force
The Zhitong Finance App learned that the “Global Smart Glasses Market Quarterly Tracking Report” recently released by International Data Corporation (IDC) shows that global shipments in the second quarter increased 35.3% year on year. Audio and photography glasses became the main growth force. AR/ER glasses accelerated penetration, and the headset market faced adjustments. Major international manufacturers continue to dominate the industry direction, and ecology and AI experience have become the new focus of competition; Chinese innovative manufacturers are speeding up the pace of globalization and enhancing overseas influence through product diversification and channel expansion. At the same time, the market structure is evolving towards advanced intelligence, and application scenarios are constantly expanding. Despite short-term pressure on the Chinese market, the vitality of the industry has not diminished. Technological innovation, ecological collaboration, and global layout are injecting new momentum into future development.
The global market
According to the latest IDC data, the global smart eyewear (Smart Eyewear) market shipments reached 3.547 million units in the second quarter of 2026, an increase of 35.3% over the previous year. Among them, shipments of audio and audio shooting glasses were 2.494 million units, up 54% year on year; AR/ER glasses were shipped 505,000 units, up 75.7% year on year; and 548,000 VR/MR headsets were shipped, down 23.3% year on year.
In the first half of 2026, the cumulative shipment volume of the global smart glasses market reached 7.114 million units, an increase of 70.5% over the previous year. This round of growth is mainly driven by glasses-type products, and the market structure is gradually evolving towards higher levels and intelligence. In the second half of the year, with the release of new products and the integration of technology, the industry pattern is expected to be further adjusted, but the overall demand performance still needs to be observed.
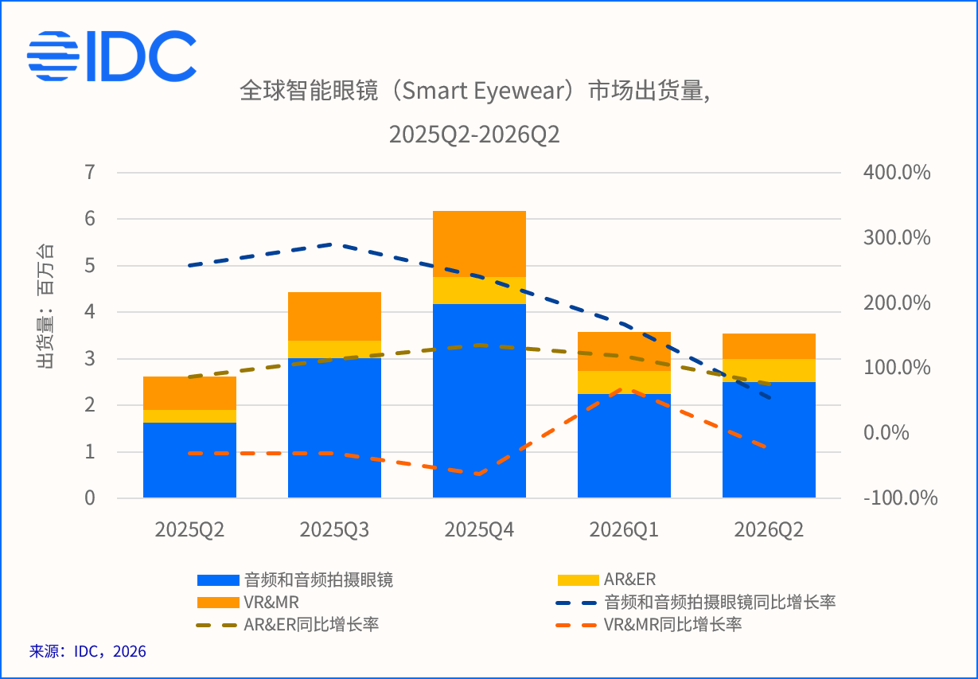
Global Market Product News
1. The share of major international manufacturers is leading, and the focus of resource investment is clearly shifting
Leading international manufacturers continue to lead the development direction of the smart glasses industry. Meta maintains a leading position in the market with audio smart glasses and is actively preparing for new product launches. Apple's first smart glasses product has entered the countdown to mass production, and the focus of industry competition is shifting from simple hardware shipments to the deep integration of the ecosystem and AI experience. Despite the multi-line layout of major international companies, there has been a clear shift in the focus of resource investment.
Meta (META.US): Continuing to maintain its leading share of the global smart glasses market, and launched new, more cost-effective products in the second quarter, further strengthening its foundation in the mass consumer market. Display smart glasses such as Ray-Ban Display are limited by yield and production capacity. Shipments have yet to be scaled up, and market segmentation advantages have yet to be established. In terms of headsets, the Quest series continues to advance, but overall shipments are expected to be limited.
Apple (AAPL.US): As the first smart glasses product enters mass production, the pace of the headset product line is adjusted accordingly, and the release time for the next headset may be greatly delayed.
2. Chinese science and technology innovators accelerate globalization and diversify product lines and channels
Chinese science and technology innovators have accelerated their global layout. By enriching product lines, expanding overseas channels, and deepening localized operations, they have formed differentiated competitiveness in the field of display glasses, and their overseas market share continues to increase.
Thunderbird: Accelerate product iteration and launch the GT series and lightweight V4 AI shooting glasses, which focus on high-end movie viewing experiences. At the same time, Q3 will officially release the iO series display smart glasses. Overseas market expansion accelerated this year, offline channel construction accelerated, and maintained a lead in the global and Chinese consumer AR & ER eyewear markets in the first half of the year.
Xreal: Overseas shipments account for more than 60% of global shipments. The product line continues to be rich, covering different price segments and segments, including the entry-level XBX A01+ and R1 for the gaming market. At the same time, Q3 will officially release Project Aura overseas to further improve the layout of high-end display smart glasses, and the global market coverage is becoming more and more perfect.
Manufacturers such as Inmo and Viture also continue to gain strength in overseas markets. Inmo plans to launch Wang Jia Er co-branded models in Q3 to expand the fashion consumption scene; Viture focuses on market segmentation, continues to expand overseas retail channels, and has a steady performance in North America and other places.
3. Ecological construction and cross-border cooperation are being accelerated, and application scenarios continue to expand
Ecological construction and cross-border cooperation are accelerating, smart glasses application scenarios continue to expand, and manufacturers continue to enhance product value through AI capabilities, content ecology and multi-terminal collaboration.
Qianwen: Qianwen quickly gained momentum in the domestic smart glasses market with cameras and mainly AI functions. Relying on the deep integration of large models with e-commerce and payment ecosystems, it took the lead. In the third quarter, it is expected to collaborate with the new Qianwen AI headset to further improve the AI hardware ecosystem layout.
Rokid: Overseas shipments began to increase, maintaining the lead in the global non-full-color eyewear market in the second quarter. At the ecological level, Open Day 2026 released Yoda OS to improve the underlying system. Subsequent plans are to introduce Tencent WorkBuddy AI office capabilities to explore the implementation of glasses in the office scene.
Chinese market
In the second quarter of 2026, China's smart glasses market shipped 611,000 units, down 8.0% year on year. The market experienced negative growth for the first time. The decline was mainly affected by the audio glasses market, but overall industry competition is still active. Manufacturers continue to optimize product lines and channel layouts, new players continue to enter, and market vitality has not diminished.
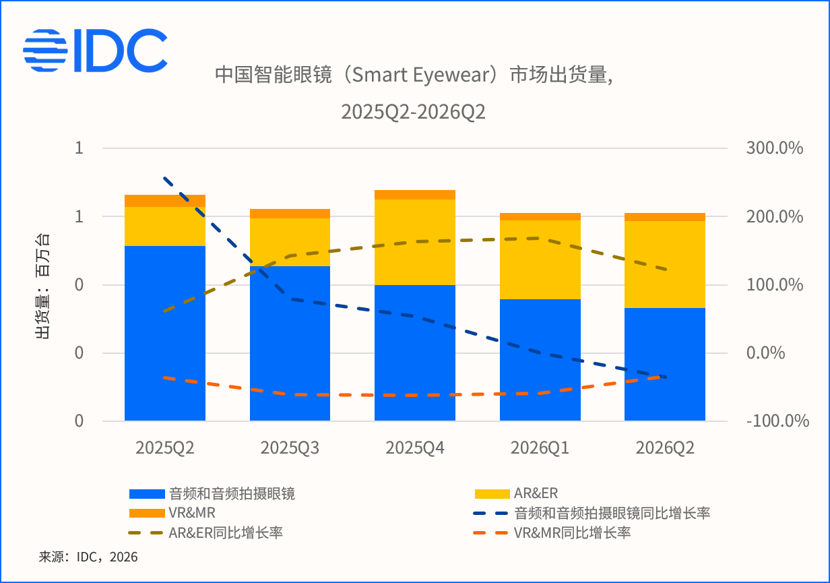
Overview of China's market segments and market pattern
The market for audio and audio shooting glasses
In the second quarter of 2026, the total shipment volume of China's audio and audio shooting glasses market was 332,000 units, a year-on-year decline of 35.4%. The market structure continues to upgrade. The market share of audio shooting glasses has surpassed that of audio glasses, accounting for 55.3%, an increase of 81.4% over the previous year.
The decline in the market this quarter was mainly due to leading brand products gradually entering the end of their life cycle, putting pressure on overall shipments, and new products launched on the market have yet to form an effective relay. At the same time, the problem of homogenization of audio eyewear products is prominent, and there is a lack of differentiated innovation, which further affects consumers' willingness to renew. Although the promotion season brought some attention, the impact on sales was limited. In this context, some new manufacturers have a wait-and-see attitude towards the market, and the pace of entry into the market is relatively slow. Whether the market can resume continuous growth in the future still depends on the implementation of innovative features and the further release of user demand.
AR/VR market
In the second quarter of 2026, China's AR/VR market shipped 279,000 units, an increase of 85.8% over the previous year.
The AR&ER eyewear market grew 123.0% year over year, benefiting from lightweight glasses with AI features as the main focus. The market share of monochromatic glasses surpassed full-color glasses for the first time, reaching 51.2%, represented by brands such as Qianwen, Rokid, and Inmo. The price segment covers the mainstream consumer range to meet the needs of different users. At the same time, judging from the “China Smart Glasses Market Monthly Tracking Report” data, iFLYTEK will begin shipping in July, which is expected to further drive changes in the market pattern. The industry as a whole is showing a positive trend of accelerated technological innovation and diversification of application scenarios. The deep integration of AI and AR&ER hardware has brought more room for imagination to the market.
Shipments in the VR & MR headset market fell 34.4% year on year in the second quarter, and the decline narrowed somewhat. With the continuous expansion of industry applications, Headphones is showing new growth opportunities in new scenarios such as large space commercial use, robot back-office data collection, and remote control, which helps digest part of the inventory. At the same time, Pico may release a new product at the end of the year, which will have a great impact on the market pattern and future trends. The industry will generally pay attention to the changes it may bring about in product scale and ecological construction. Overall, with the launch of new products and the deepening of industry applications, the headphone market is expected to pick up and usher in structural growth opportunities.
Future prospects and new opportunities
Ye Qingqing, a market analyst at IDC in China, believes that despite support from state compensation policies and promotional activities, smart glasses are still cautious in their purchasing decisions as emerging technology products. Currently, the potential value of smart glasses, as an important interactive portal for integrating terminal ecology and AI capabilities, has not been fully unleashed. Only when product experience, content ecology, and actual application scenarios are further enriched will industry chain participants and terminal consumer groups continue to expand.
Looking ahead to the second half of the year, the market will show the following trends:
First, product line differentiation and acceleration of innovation. In the second half of the year, manufacturers will accelerate product line differentiation and launch more combination solutions for different user needs in terms of color display, weight control, and wearing comfort. Lightweight full-color glasses will be the focus of the layout, which not only satisfies portability for everyday wear, but also enhances the visual experience. Some manufacturers will also explore multi-functional integration of AI, imaging, health, etc., to promote the transformation of products from a single function to multi-scenario applications, and further stimulate users' desire to renew.
Second, the pace of going out to sea is speeding up, and the global layout is deepening. As competition in the domestic market intensifies and growth space is limited in stages, more and more Chinese manufacturers are speeding up the expansion of overseas markets. Overseas market segments are not yet fully saturated. Especially in fields such as AR&ER, domestic brands have established popularity in some regions due to technology accumulation and cost performance advantages. The launch of lightweight products is expected to further open up overseas market space and reduce the pressure to compete head-on with major international manufacturers. In addition to scientific and technological innovation enterprises, some large traditional manufacturers are also actively laying out or focusing on overseas opportunities, and globalization will become the main theme of the industry.
Third, ecological construction and scenario implementation continue to advance. The improvement of the ecosystem and cross-border cooperation will be the key to the development of the smart glasses industry. Manufacturers will increase collaboration with ecological partners such as content, AI, payment, and e-commerce to promote the implementation of smart glasses in diverse scenarios such as office, entertainment, health, and education. The deep integration of AI models and terminal hardware will enhance the level of product intelligence and drive a new round of application innovation.