


European Undervalued Small Caps With Insider Action In September 2026
As European markets navigate the complexities of heightened inflation concerns and rising government bond yields, small-cap stocks have faced particular pressure. Despite these challenges, certain small-cap companies in Europe may present intriguing opportunities, especially when insider actions suggest confidence in their potential.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.0x | 2.2x | 39.12% | ★★★★★★ |
| Nyab | 17.2x | 0.8x | 34.21% | ★★★★☆☆ |
| Franchise Brands | 27.8x | 2.0x | 46.63% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 17.33% | ★★★★☆☆ |
| Saniona | 7.7x | 3.3x | 28.27% | ★★★★☆☆ |
| Linc | 12.6x | 13.1x | 32.18% | ★★★★☆☆ |
| Eurocell | 22.4x | 0.3x | 48.56% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 22.45% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -217.34% | ★★★☆☆☆ |
| Krona Public Real Estate | 8.7x | 4.9x | 35.67% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Advanced Medical Solutions Group (AIM:AMS)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Advanced Medical Solutions Group is a company specializing in the development and manufacturing of advanced wound care products and surgical solutions, with a market cap of approximately £0.75 billion.
Operations: The company generates revenue primarily from its Surgical and Woundcare segments, with the Surgical segment contributing significantly more. Over recent periods, the net profit margin has shown a downward trend, reaching as low as 1.58% in the latest quarter.
PE: 165.7x
Advanced Medical Solutions Group, a smaller European stock, has seen insider confidence with recent share purchases. Despite reporting a net loss of £0.065 million for the first half of 2026, down from a £6.21 million profit last year, earnings are forecast to grow by 60% annually. Sales increased slightly to £115.46 million from £110.77 million in the same period last year. The company faces challenges with high-risk external borrowing and one-off items affecting earnings quality but is expanding direct sales in Europe for potential growth opportunities.
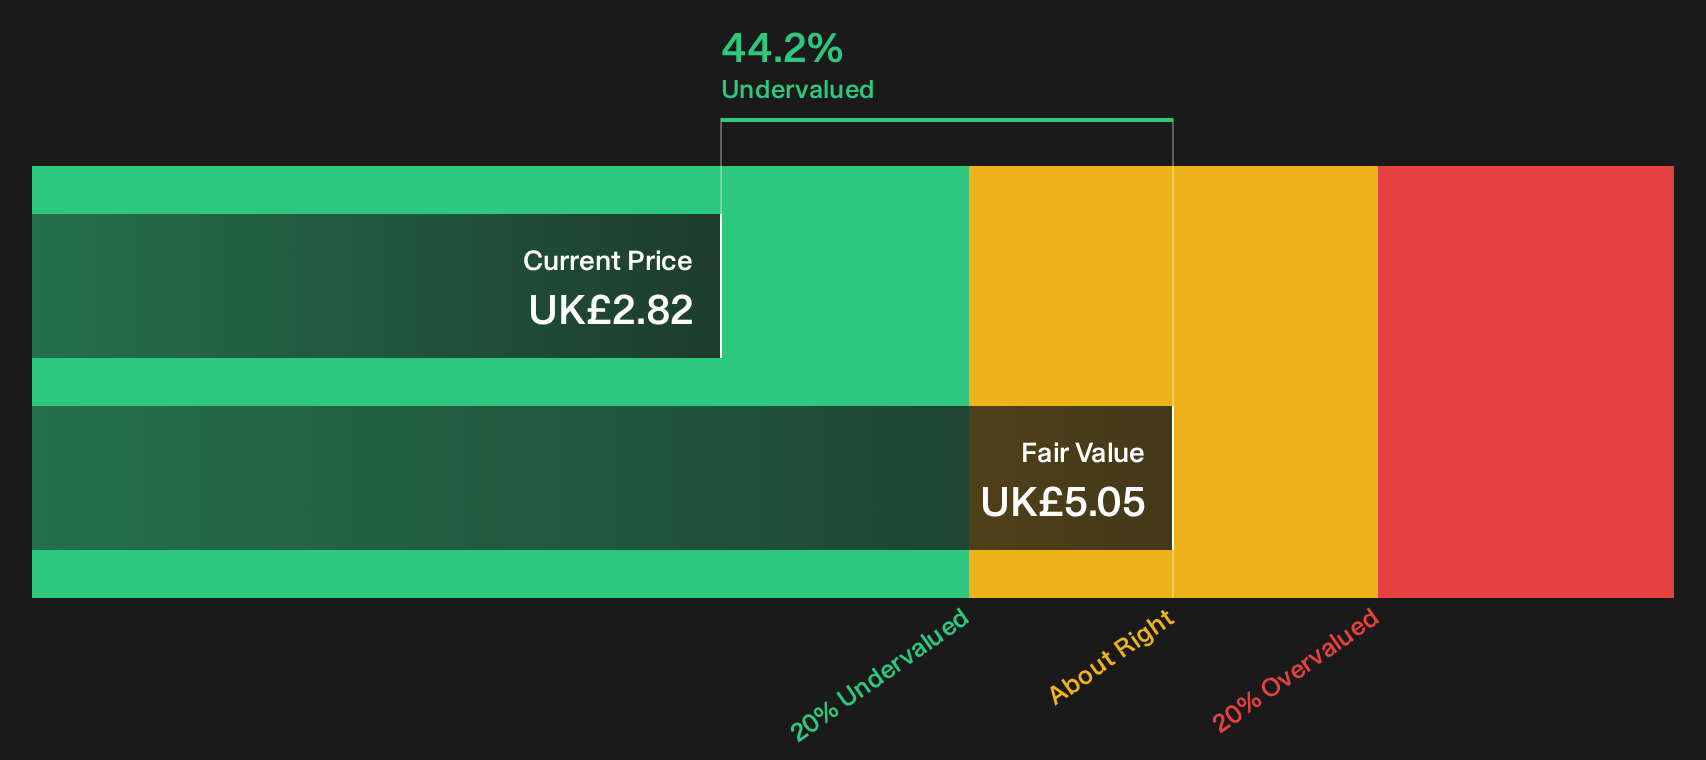
Genuit Group (LSE:GEN)
Simply Wall St Value Rating: ★★★★★★
Overview: Genuit Group is a UK-based company specializing in sustainable water, climate, and ventilation solutions with a market cap of approximately £1.03 billion.
Operations: The company generates revenue primarily from its Climate Division, with a significant segment adjustment impacting overall figures. Over recent periods, the net income margin has shown variability, reaching 8.35% in June 2025 and dipping to 5.60% by June 2026. Operating expenses are consistently driven by sales and marketing as well as general and administrative costs.
PE: 18.9x
Genuit Group, a smaller player in the European market, is catching attention with insider confidence shown through recent share purchases. Despite a dip in net income to £13 million for H1 2026 from £23.9 million the previous year, sales rose slightly to £307.8 million. The company maintains its interim dividend at 4.2 pence per share, signaling stability amidst fluctuating profit margins and reliance on external borrowing for funding. Earnings are projected to grow annually by over 20%, indicating potential future value growth despite current challenges.
- Click to explore a detailed breakdown of our findings in Genuit Group's valuation report.
Gain insights into Genuit Group's past trends and performance with our Past report.

Travis Perkins (LSE:TPK)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Travis Perkins is a leading UK-based company specializing in the distribution of building materials and home improvement products, with a market capitalization of approximately £1.80 billion.
Operations: The company generates revenue primarily from its Merchanting segment (£3.67 billion) and Toolstation (£849.4 million). The gross profit margin has shown significant fluctuations, reaching as high as 38.50% in some periods, while experiencing negative margins in others, such as -9.54%. Operating expenses are a substantial part of the cost structure, with notable amounts allocated to sales and marketing expenses across various periods.
PE: -7.4x
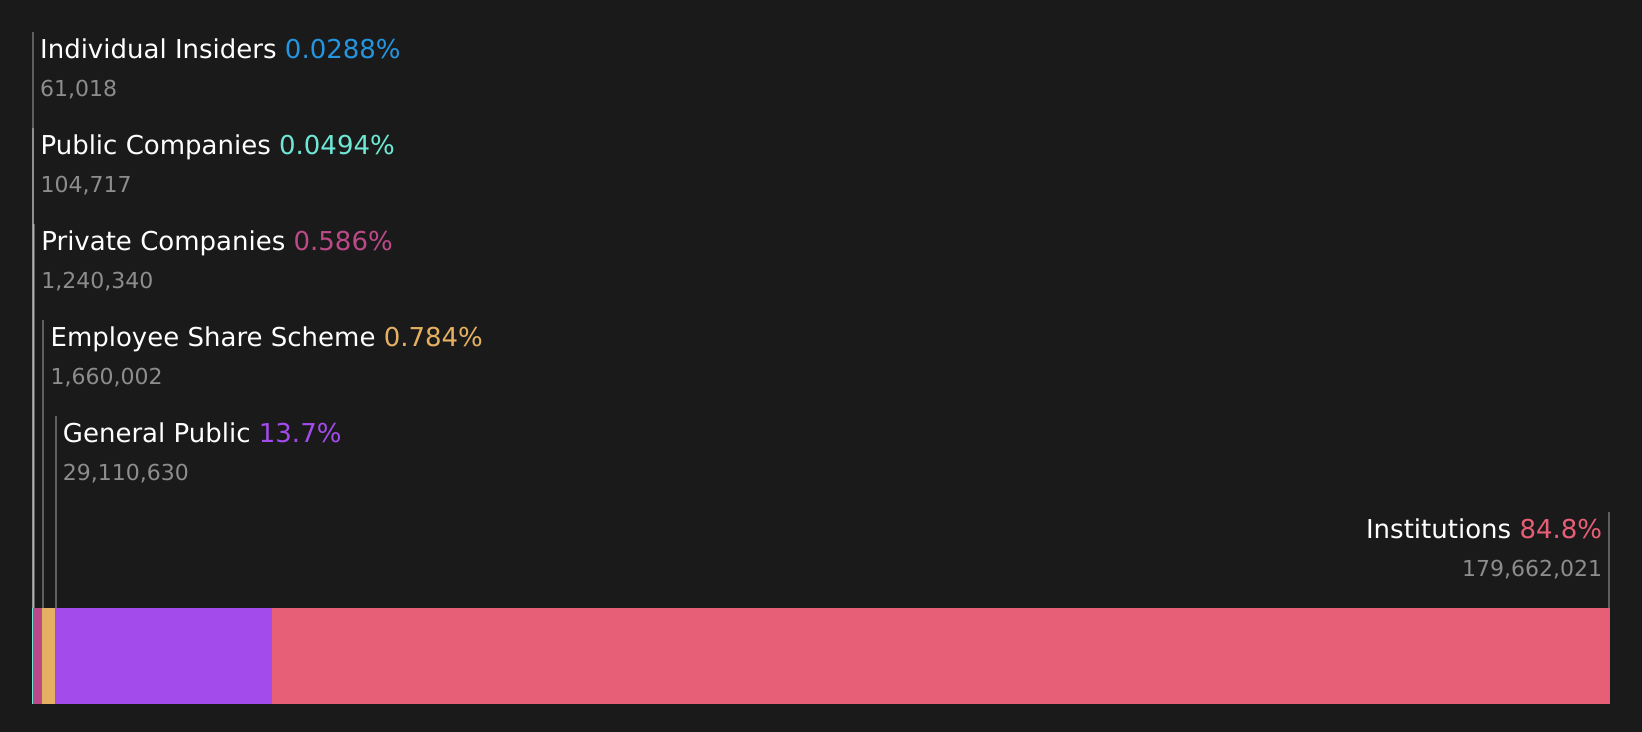
Travis Perkins, a smaller player in Europe's market, shows potential despite mixed signals. Their recent earnings report for H1 2026 revealed sales of £2.26 billion, slightly down from last year, yet net income rose to £30.3 million from £26.4 million. Insider confidence is evident with notable purchases over the past year, suggesting faith in future growth prospects—earnings are projected to grow annually by 89%. However, reliance on external borrowing poses some risk amidst these promising indicators.
- Dive into the specifics of Travis Perkins here with our thorough valuation report.
Gain insights into Travis Perkins' historical performance by reviewing our past performance report.
Key Takeaways
- Investigate our full lineup of 38 Undervalued European Small Caps With Insider Buying right here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com