


Will Higher Earnings And Dividend Lift Change Uniphar (ISE:UPR) Narrative
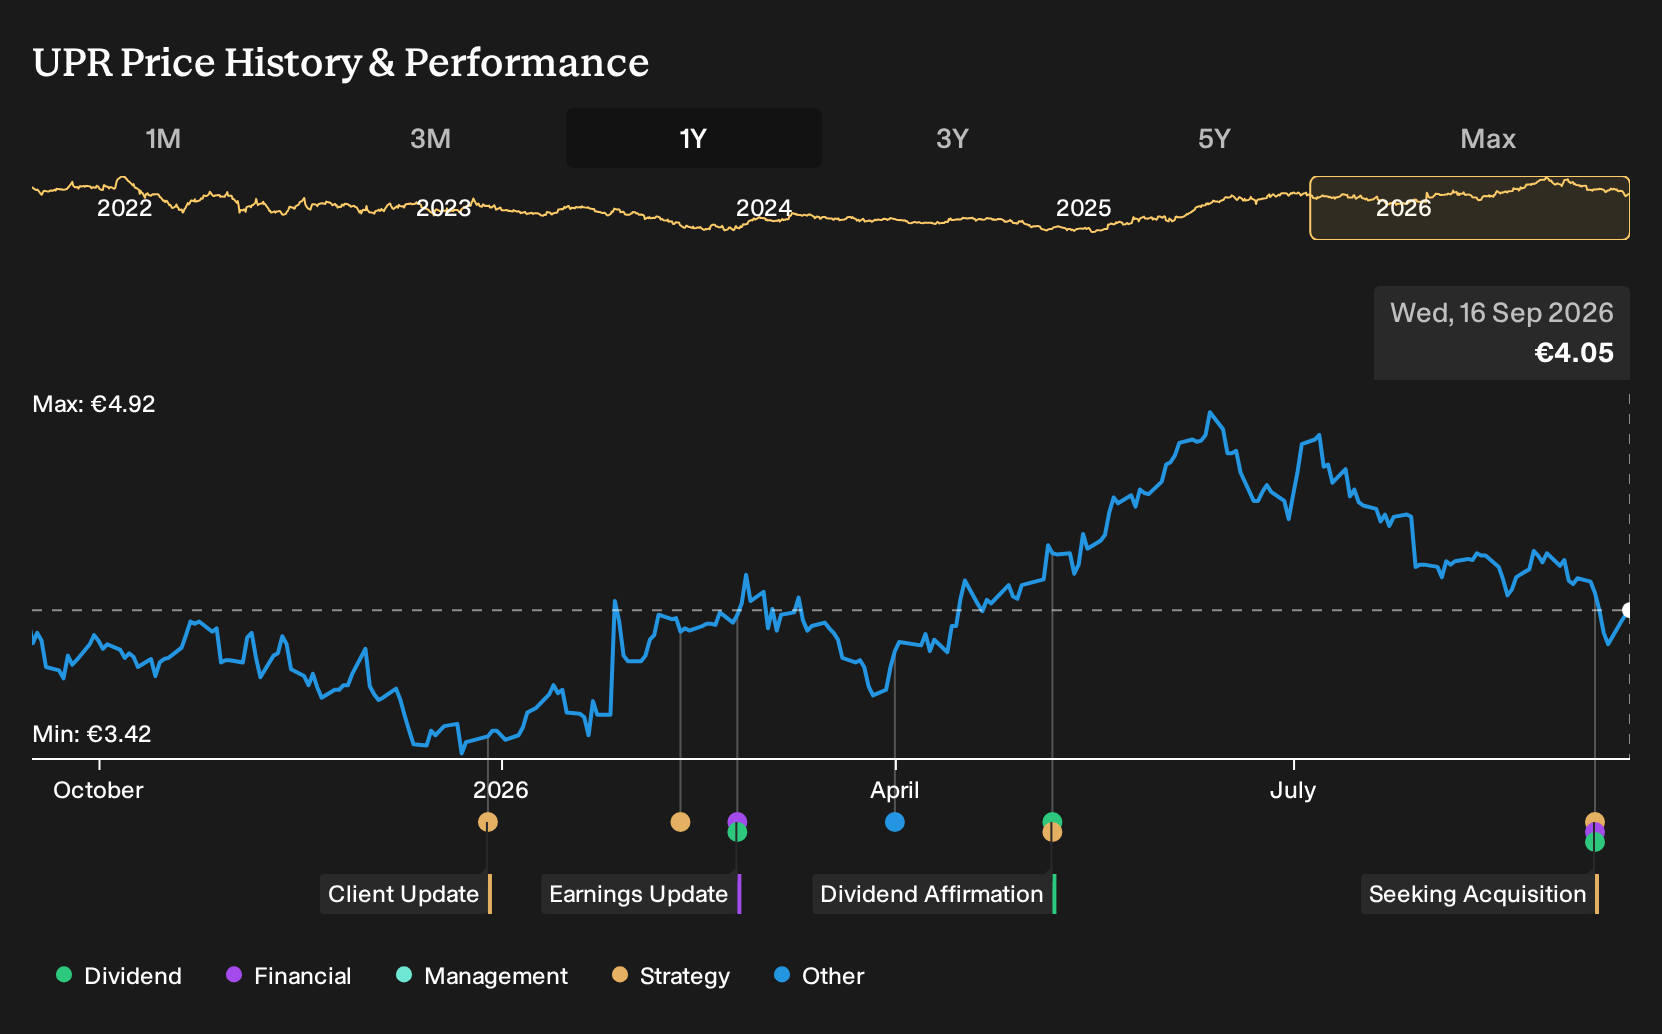
- Uniphar reported half year 2026 sales of €1,591.86 million and net income of €19.99 million, alongside basic EPS of €0.077 and a higher interim dividend of €0.0074 per share, paid on 9 October 2026.
- The combination of higher earnings and a 4.2% dividend uplift points to management prioritising both reinvestment and direct cash returns while pursuing an acquisition pipeline in pharma services and medtech.
- We will now see how Uniphar's investment narrative is affected by the higher interim dividend and the latest half year earnings.
Compare Uniphar's acquisition driven model with other potential breakout ideas by scanning our hand picked list of 619 high quality undiscovered gems in adjacent sectors and capital efficient niches.
Uniphar Investment Narrative Recap
To own Uniphar, you need to be comfortable with a healthcare services group that relies on both organic expansion and steady deal making in pharma and medtech. The recent half year numbers show higher sales and earnings, which supports the view that the current investment phase into infrastructure, technology and people is still feeding through to the income statement.
The short term swing factor remains execution on the new distribution and technology platforms, while protecting margins from being squeezed by dual running and field force build out. The biggest risk is that fresh acquisitions are layered onto this workload and stretch cash generation and integration capacity.
The most relevant update for that thesis is the management commentary on acquisitions and capital allocation. Uniphar is actively assessing targets across pharma services and medtech, while aiming for returns on capital employed at or above 12% to 15% and keeping net bank debt to EBITDA below 2.5x over the medium term.
For you, the operational question is whether Uniphar can keep hitting those hurdle rates while it beds in its new hubs and maintains a progressive dividend that already moved 4.2% higher for the interim period. If free cash flow lags operating profit, funding deals, infrastructure and shareholder distributions at the same time could become a pressure point.
Uniphar's narrative projects €3.5b revenue and €73.0 million earnings by 2029. This assumes annual revenue growth of 4.8% and an earnings increase of about €21.9 million from €51.1 million today.
Uncover how Uniphar's fair value indicates a 32% potential upside to its current price. This could narrow quickly if sentiment swings in Uniphar's favour.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a wide band, from about €5.34 to €17.63 per share, which shows how far opinions on Uniphar can stretch. Those views pre date the latest dividend uplift and acquisition push, so factor in that execution on M&A and the new hubs could shift sentiment.
Explore 2 other Uniphar fair value estimates, including one that suggests as much as 335% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Uniphar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Uniphar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Uniphar's overall financial health at a glance.
Looking for more investment ideas beyond Uniphar?
If Uniphar has sharpened your thinking about where capital can work hardest, casting the net wider can help you spot opportunities with different risk and income profiles across the market.
- For investors hunting for companies that may trade below what their fundamentals imply, scan our hand picked pool of 189 high quality undervalued stocks that combine quality with pricing that some might view as appealing.
- If capital preservation and resilience matter most to you, focus on businesses screened for robust finances and dependable metrics through our 104 resilient stocks with low risk scores that aim to keep downside risk in check.
- For those building an income oriented portfolio, zero in on cash generators offering stronger yields with our curated set of 161 dividend fortresses that meet a 5%+ payout hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com